Decoding Bond Credit Ratings: The Backbone of Fixed-Income Investing
Bond Credit Ratings: Understanding the Backbone of Fixed-Income Investing
Introduction:
When it comes to investing in fixed-income securities, one crucial aspect that investors must consider is the bond credit rating. Bond credit ratings provide an assessment of the creditworthiness and default risk associated with a bond issuer. These ratings are assigned by independent credit rating agencies and play a pivotal role in determining the interest rates, yield, and overall attractiveness of bonds in the market.
In this deep-dive article, we will explore what bond credit ratings are, how they work, why they matter to investors, and delve into some of the major credit rating agencies. By understanding these essential elements, investors can make more informed decisions about their fixed-income investments.
Understanding Bond Credit Ratings:
1. What Are Bond Credit Ratings?
Bond credit ratings provide an evaluation of an issuer’s ability to meet its financial obligations promptly. They aim to gauge the likelihood that a bond issuer will default on its payment obligations or fail to repay principal amount when due. These ratings serve as an indicator of investment risk and help investors assess whether a particular bond aligns with their risk appetite.
Credit rating agencies assign letter grades or symbols that represent different levels of creditworthiness for issuers based on extensive analysis of factors such as financial statements, economic outlooks, industry trends, management quality, debt structure, and other relevant data points.
2. How Do Bond Credit Ratings Work?
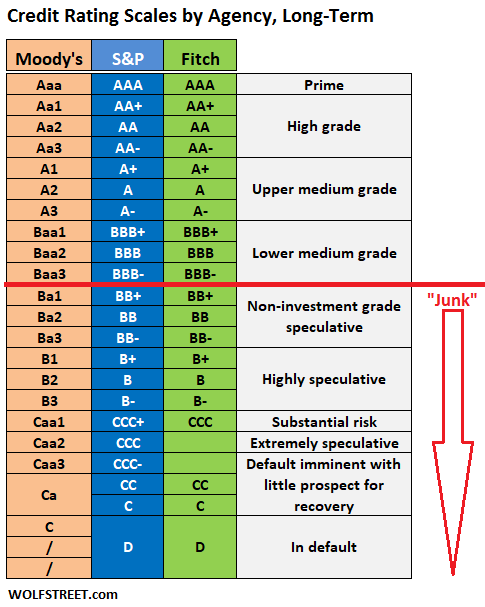
Credit rating agencies employ their own methodologies to evaluate bond issuers’ creditworthiness consistently. While each agency may have slight variations in their rating scales or terminologies used (AAA-rated vs., Aaa-rated), there is broad alignment across agencies regarding assigning higher ratings for lower-risk investments.
The three major global rating agencies are Standard & Poor’s (S&P), Moody’s Investors Service (Moody’s), and Fitch Ratings (Fitch). These agencies utilize various combinations of letters or symbols to classify bonds into different rating categories. For instance, S&P uses AAA, AA, A, BBB, BB, B, CCC, CC, C as their rating scale from the highest credit quality to speculative or default-prone bonds.
To further differentiate within each letter grade or category and provide a more nuanced assessment of risk levels within it, agencies may add “+” or “-” symbols (e.g., AA+, A-, etc.). Certain agencies may also have additional notations like “positive outlook,” “negative outlook,” or “watch” to indicate potential future changes in ratings.
3. Why Do Bond Credit Ratings Matter?
Bond credit ratings serve several important purposes for both issuers and investors:
a) Assessing Risk: Credit ratings help investors gauge the likelihood of bond defaults and make informed investment decisions that align with their risk tolerance.
b) Pricing Bonds: Ratings influence bond prices inversely – higher-rated bonds tend to have lower yields since they are considered safer investments. Conversely, lower-rated bonds offer higher yields due to increased default risk.
c) Accessing Capital Markets: Companies with stronger credit ratings can access capital markets at favorable interest rates compared to those with weaker ratings. This allows them to raise funds efficiently for business expansion or operational needs.
d) Regulatory Requirements: Many institutional investors are required by law or internal policies to invest only in securities meeting certain minimum credit rating thresholds.
4. The Major Credit Rating Agencies:
Let’s take a closer look at the three major global rating agencies:
a) Standard & Poor’s (S&P):
As one of the oldest and most widely recognized credit rating agencies globally established in 1860s New York City – S&P provides independent opinions about financial market participants’ creditworthiness. Their well-known AAA through D rating scale signifies varying levels of investment-grade (AAA-D), speculative-grade (BBB-D), and default-category (D).
b) Moody’s Investors Service:
Founded in 1909 by John Moody, this agency covers various aspects of credit analysis and has a reputation for providing in-depth research and ratings. Moody’s rating scale consists of Aaa through C, with the first three grades representing investment-grade bonds and the rest falling into speculative or default categories.
c) Fitch Ratings:
Fitch Ratings was established in 1913 and is known for its rigorous credit analysis across multiple sectors. Their rating scale mirrors S&P’s AAA through D system but also includes “+” or “-” symbols to indicate additional gradations within each category.
Conclusion:
Bond credit ratings are an essential tool for fixed-income investors to assess the risk associated with bond issuers. These ratings provide insights into default probabilities, influence pricing, enable access to capital markets, and help meet regulatory requirements. By understanding how bond credit ratings work and considering assessments from major rating agencies like Standard & Poor’s, Moody’s Investors Service, and Fitch Ratings, investors can make more informed decisions about their fixed-income investments. Remember that while bond credit ratings offer valuable guidance, they should be considered alongside other factors such as financial goals, time horizon, diversification needs, and macroeconomic conditions when constructing a well-balanced investment portfolio.