“Maximize Your Retirement Savings with the Benefits of a 401(k)”
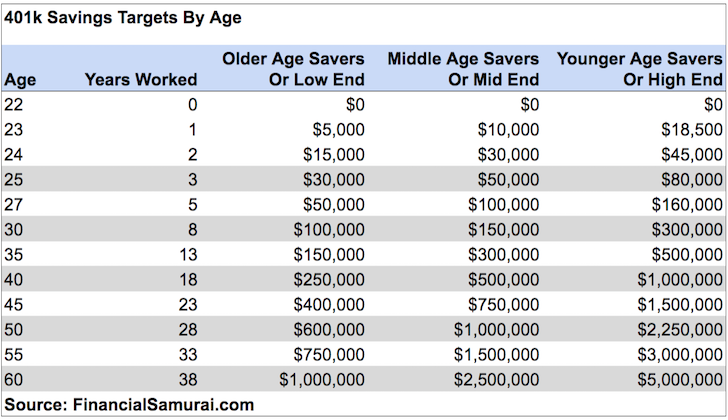
The 401(k) is a popular retirement savings plan offered by many employers in the United States. It allows employees to contribute a portion of their pre-tax income into an investment account, which can grow over time and provide them with funds for retirement.
One of the main advantages of a 401(k) is the ability to make pre-tax contributions. This means that the amount you contribute to your 401(k) is deducted from your taxable income, reducing your overall tax liability for the year. For example, if you earn $50,000 per year and contribute $5,000 to your 401(k), you will only be taxed on $45,000. This can help lower your current tax bill and potentially put more money in your pocket.
Another benefit of a 401(k) is employer matching contributions. Many employers offer a match program where they will match a certain percentage of an employee’s contributions up to a certain limit. For example, if your employer offers a dollar-for-dollar match up to 3% of your salary and you earn $60,000 per year, contributing at least $1,800 ($60,000 x 3%) will result in an additional $1,800 contributed by your employer. This essentially doubles your money without any extra effort on your part.
Additionally, one advantage of investing in a 401(k) is the potential for tax-deferred growth. The investments within the account can grow without being subject to capital gains taxes or dividend taxes until withdrawals are made during retirement. This allows for compounding growth over time as earnings are reinvested rather than being taxed each year.
However, there are some limitations and considerations when it comes to 401(k)s as well. One limitation is that there are annual contribution limits set by the IRS each year. As of 2022, individuals under age 50 can contribute up to $20,o00 annually while those over 50 can contribute an additional $6,500 as a catch-up contribution. It’s important to be aware of these limits and plan accordingly to maximize your savings.
Another consideration is that there may be restrictions on when you can access the funds in your 401(k) without penalty. Typically, withdrawals made before age 59½ are subject to a 10% early withdrawal penalty in addition to income taxes. However, there are some exceptions such as hardship withdrawals or loans against the account balance.
In conclusion, a 401(k) is a valuable retirement savings tool that offers tax advantages, potential employer matching contributions, and tax-deferred growth. While it comes with certain limitations and considerations, it remains one of the most popular ways for Americans to save for retirement. It’s important to take advantage of this benefit if offered by your employer and make regular contributions towards building a secure financial future.