“Unraveling the Complexities of Financial Statements: Understanding Deferred Tax Assets, AOCI, and More!”
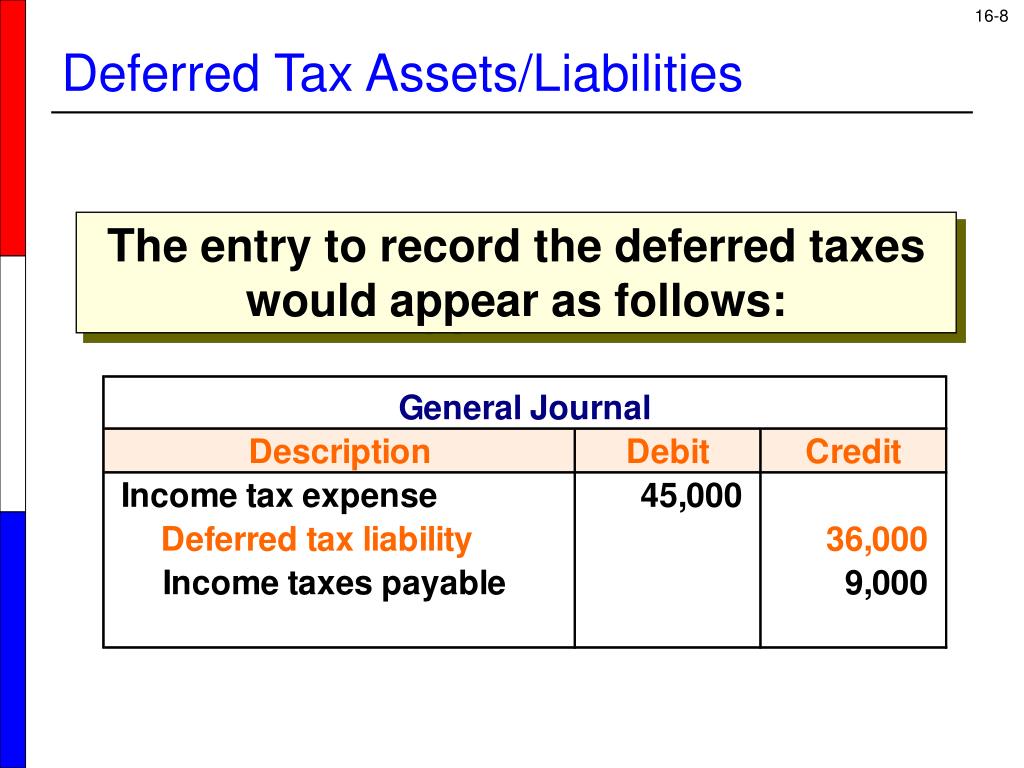
Deferred tax assets and liabilities are financial items that arise from the differences between taxable income and accounting income. These differences can occur due to timing or valuation discrepancies in recognizing revenues, expenses, and gains or losses for tax purposes versus book purposes.
Deferred tax assets represent future tax benefits that a company can claim when it has overpaid taxes in the past or incurred deductible expenses that have not yet been recognized for tax purposes. They are recorded as assets on the balance sheet until they can be utilized to offset future taxable income.
On the other hand, deferred tax liabilities arise when a company has underpaid taxes in the past or has recognized taxable revenues before they are included in its accounting income. These liabilities represent the amount of additional taxes that will be paid in future periods once these temporary differences reverse.
Accumulated other comprehensive income (AOCI) is a component of shareholders’ equity that includes unrealized gains and losses on certain investments, foreign currency translation adjustments, pension plan adjustments, and derivative instrument valuations. AOCI reflects changes in value that have not yet been realized through actual cash flows but may impact future earnings if those values change.
Contingent liabilities refer to potential obligations arising from uncertain events whose outcomes will only be confirmed by the occurrence or non-occurrence of one or more uncertain future events beyond a company’s control. Examples include pending lawsuits, warranties on sold products, or environmental cleanup costs resulting from prior operations. Companies must disclose these contingent liabilities in their financial statements along with an estimate of their likelihood and potential impact on their financial position.
Minority interest represents ownership stakes held by minority shareholders in subsidiaries owned by another entity. It represents the portion of a subsidiary’s net assets not attributable to majority shareholders (the parent company). Minority interest is reported as part of equity on the balance sheet since it represents outside ownership claims against consolidated net assets.
Goodwill impairment occurs when there is a decline in the fair value of goodwill associated with an acquisition. Goodwill is the excess of the purchase price over the fair value of identifiable net assets acquired. If the fair value of the reporting unit (the acquired business) decreases below its carrying amount, an impairment loss must be recognized, reducing the value of goodwill and impacting a company’s financial statements.
Long-term investments are financial instruments that a company holds for more than one year and intends to hold until maturity or sell in the future for gains. These investments can include bonds, stocks, mutual funds, or real estate holdings.
Intangible assets represent non-physical assets with no physical substance but have identifiable economic benefits and long-term value to a company. Examples include patents, trademarks, copyrights, franchises, customer lists, and intellectual property rights.
Treasury stock refers to shares of a company’s own stock that it has repurchased from shareholders but not retired. Treasury stock reduces shareholder equity on the balance sheet since it represents shares held by the company itself rather than outstanding shares owned by investors.
Capital lease obligations arise when a company leases an asset under terms that transfer substantially all risks and rewards associated with ownership to the lessee. Capital leases are recorded as both an asset (the leased item) and liability (the obligation to make lease payments) on a company’s balance sheet.
Pension and post-retirement benefit obligations refer to companies’ commitments to provide retirement benefits such as pensions or healthcare coverage for their employees after they retire. These obligations are recognized on the balance sheet based on actuarial estimates of future payouts required to fulfill these promises.
Noncurrent deferred revenue is revenue received in advance from customers for goods or services that will be provided in future periods beyond one year from the reporting date. This unearned revenue is initially recorded as liabilities on a company’s balance sheet until it is earned through performance or delivery of services/products.
Asset retirement obligations represent legal obligations associated with dismantling decommissioning or restoring long-lived assets to their original condition. Companies must recognize the fair value of these obligations on their balance sheets and record corresponding liabilities.
Share-based compensation expense refers to the cost incurred by a company for providing its employees with equity-based incentives, such as stock options or restricted stock units. These expenses are recognized over the vesting period of the awards and impact a company’s income statement.
Derivative financial instruments are contracts whose values are derived from underlying assets, indices, or benchmarks. They can be used for hedging purposes (to mitigate risks) or speculative purposes (to profit from price movements). Derivatives must be recorded at fair value on a company’s balance sheet, with changes in fair value impacting current earnings.
Fair value measurements refer to valuing financial assets and liabilities based on their estimated market prices at a given date. Fair value is determined using observable market inputs when available or through valuation techniques that incorporate assumptions about future cash flows.
Income taxes payable/receivable represent amounts owed to tax authorities or expected tax refunds by a company based on differences between taxable income calculated for accounting purposes versus taxable income reported to tax authorities.
Research and development costs include expenditures incurred in creating new products, processes, technologies, or improving existing ones. These costs are usually expensed as incurred unless they meet specific criteria for capitalization as an intangible asset under certain circumstances.
Restructuring charges occur when companies undertake significant changes in their operations, such as closing facilities, reducing staff levels, or changing product lines. These charges reflect the costs associated with these restructuring activities and may include severance payments, lease terminations fees, asset impairments, and other related expenses.
Gain/loss on disposal of assets represents the difference between the sale proceeds received from disposing of long-lived assets (such as property, plant equipment) and their carrying amount (net book value). Gains increase net income while losses decrease it and impact a company’s financial statements accordingly.
Impairment of long-lived assets occurs when the carrying amount of an asset exceeds its recoverable amount (the higher of fair value less costs to sell or its value in use). If this happens, a company must recognize an impairment loss, reducing the asset’s value and impacting its financial statements.