Payday Loans: The Vicious Cycle of Debt
Payday Loans: A Vicious Cycle of Debt
In today’s fast-paced world, financial emergencies can arise unexpectedly. Many people find themselves in need of immediate cash to cover unforeseen expenses like medical bills or car repairs. Payday loans have become a popular solution for those facing such situations. However, it’s important to understand the potential dangers and risks associated with these types of loans.
Payday loans are short-term, high-interest loans that are typically due on the borrower’s next payday. They offer quick access to cash without requiring a thorough credit check or extensive paperwork. While this may seem appealing at first glance, payday loans often trap borrowers in a cycle of debt that can be difficult to escape.
One significant concern with payday loans is their exorbitant interest rates. The annual percentage rate (APR) for these loans can range from 300% to 500%, making them one of the most expensive forms of borrowing available. For example, if you borrow $500 with a two-week repayment term and an APR of 400%, you would owe $615 at the end of those two weeks – an additional $115 purely in interest charges.
Another issue is that payday lenders often target vulnerable individuals who may not fully understand the terms and conditions associated with these loans. Low-income earners and people with poor credit scores are particularly susceptible because they may struggle to secure more traditional forms of credit.
The structure of payday loans also encourages borrowers to roll over their debts by taking out new loans to repay existing ones. This only adds to their overall indebtedness as each rollover incurs additional fees and interest charges. According to research conducted by the Consumer Financial Protection Bureau (CFPB), nearly 80% of payday loan borrowers find themselves trapped in this cycle, taking out multiple consecutive payday loans throughout the year.
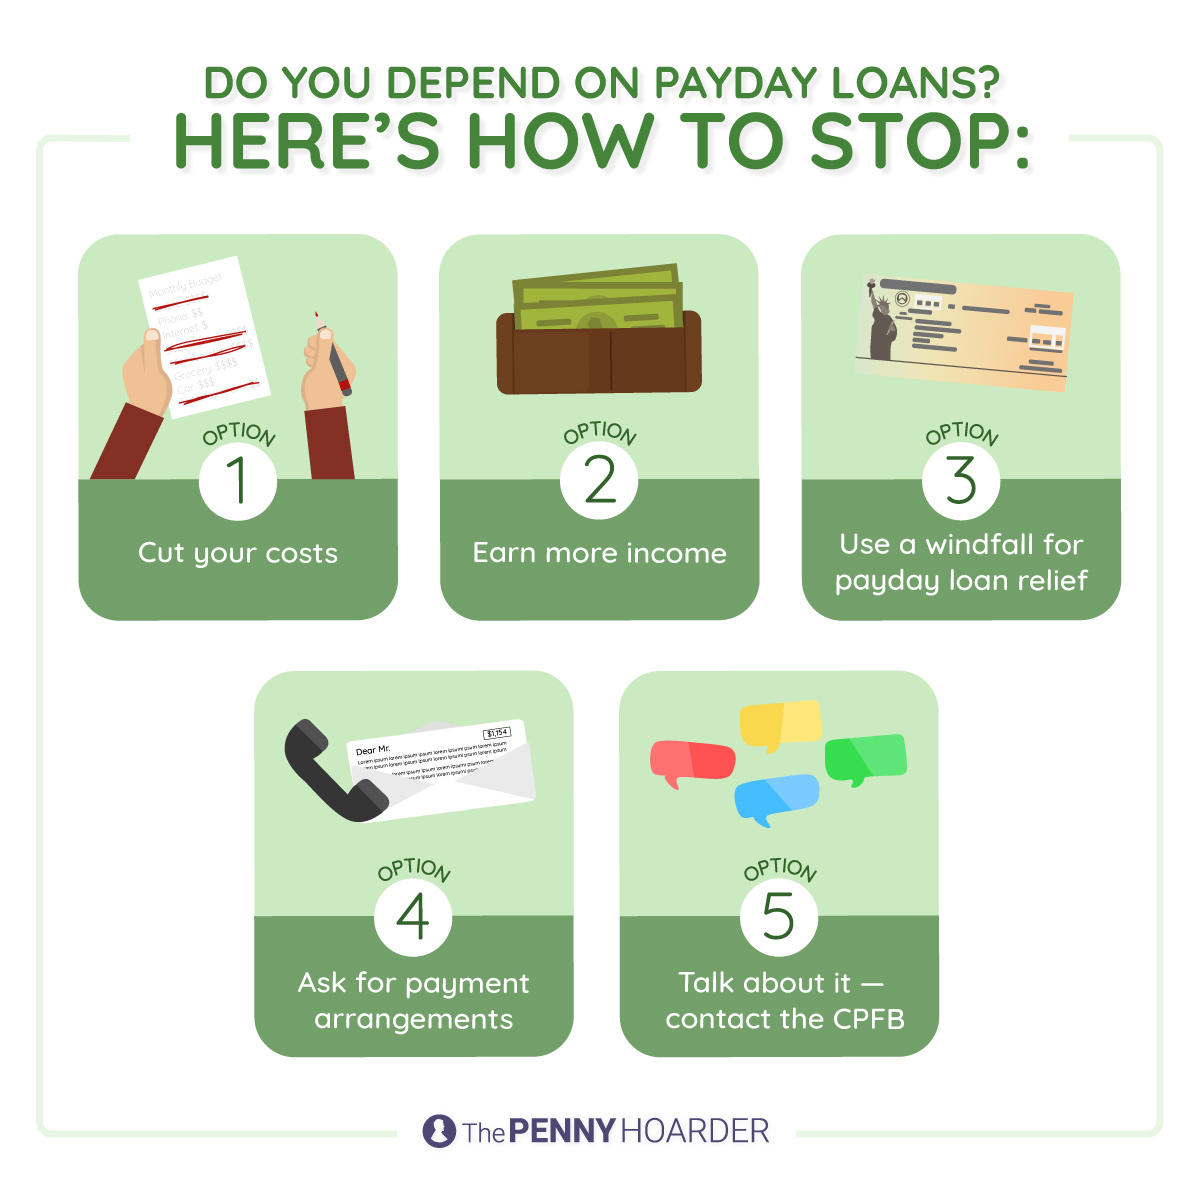
To break free from this vicious cycle, exploring alternative options is essential:
1. Establishing an emergency fund: Start putting aside a small amount each month to build up a financial safety net for unexpected expenses.
2. Seeking assistance from family and friends: Consider reaching out to loved ones who may be able to offer temporary financial support during tough times.
3. Exploring local community resources: Non-profit organizations and charities often provide emergency financial assistance or can connect individuals with additional resources in their area.
4. Negotiating payment plans with creditors: If you’re struggling to meet your existing obligations, contact your creditors directly to discuss alternative repayment options that may be more manageable for you.
5. Considering credit counseling services: Seek advice from accredited credit counseling agencies that can provide guidance on managing debt and creating a sustainable budget.
In summary, while payday loans may seem like a quick fix for urgent financial needs, they come with significant risks that often lead borrowers into an ongoing cycle of debt. It’s crucial to explore alternative solutions before resorting to these high-cost loans in order to protect your long-term financial well-being.