Demystifying Capital Gains: Your Comprehensive Guide
Calculating Capital Gains: A Comprehensive Guide
Introduction:
Capital gains are an important aspect of personal finance and investing. Understanding how to calculate them is crucial for individuals who own assets such as stocks, real estate, or other investments that may appreciate over time. This guide aims to provide a comprehensive overview of capital gains and the various factors involved in calculating them.
What are Capital Gains?
Capital gains refer to the profits made from selling an asset at a price higher than its purchase price. They are typically realized when an individual sells stocks, bonds, mutual funds, real estate properties, or any other asset that has increased in value since it was acquired.
Short-term vs. Long-term Capital Gains:
One key distinction in capital gains is whether they fall under short-term or long-term categories. Short-term capital gains apply to assets held for one year or less before being sold, while long-term capital gains apply to assets held for more than one year.
The tax treatment differs between short-term and long-term capital gains. In most countries including the United States, short-term capital gains are taxed at ordinary income tax rates whereas long-term capital gains generally have preferential tax rates which tend to be lower.
Calculating Capital Gains:
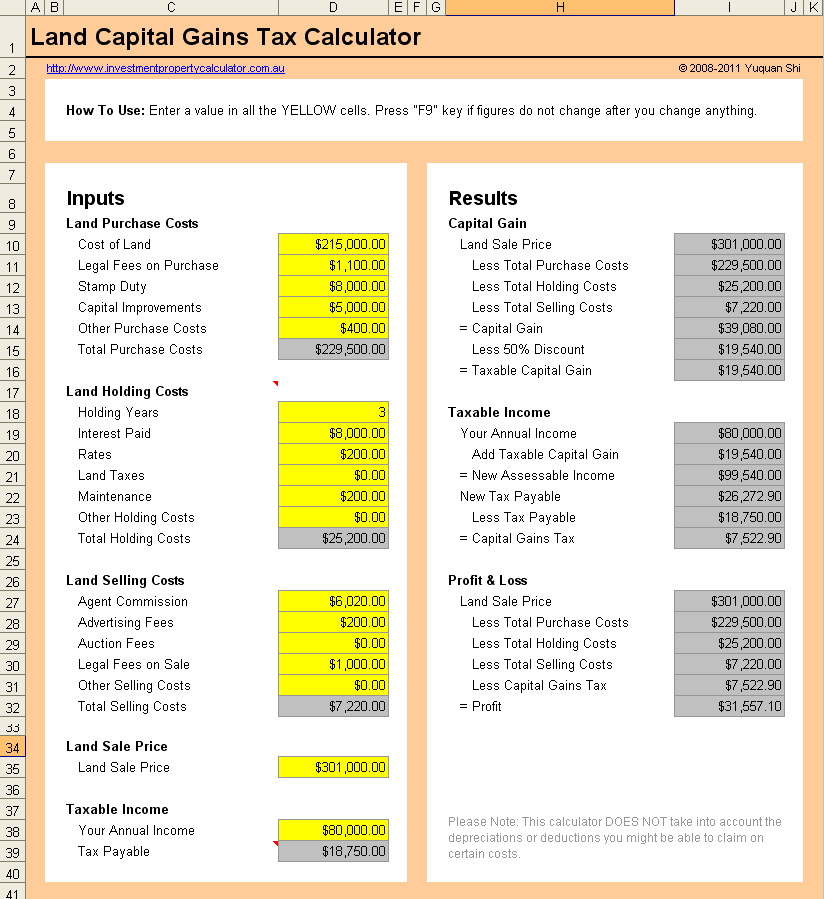
To calculate your capital gain accurately, you need to determine the cost basis of the asset you sold and subtract it from the sale price after adjustments for expenses like commissions or fees incurred during the transaction.
1. Determining Cost Basis:
The cost basis represents the original purchase price of an asset plus any additional costs associated with acquiring it (e.g., brokerage fees). To calculate your cost basis accurately, consider these factors:
a) Purchase Price: The initial amount paid when acquiring the asset.
b) Acquisition Costs: Expenses incurred during acquisition such as broker’s commission and legal fees.
c) Adjustments: Certain events may affect your cost basis over time; examples include stock splits or dividend reinvestment plans.
2. Adjusting Cost Basis:
In some cases, the cost basis may need adjustments to account for events that occurred after the initial purchase. Here are a few common scenarios:
a) Stock Splits: If you own stocks that undergo stock splits during your holding period, the number of shares will increase while the price per share decreases. To adjust your cost basis, divide your original purchase price by the new number of shares.
b) Dividend Reinvestment Plan (DRIP): If you participate in a DRIP where dividends are automatically reinvested to buy more shares, each additional share acquired should be added to your cost basis.
c) Capital Improvements: For real estate or other assets where improvements were made over time, these costs can be added to your cost basis.
3. Calculating Capital Gain:
Once you have determined your adjusted cost basis, subtract it from the sale price of your asset. The resulting figure represents your capital gain or loss. If it is a positive value, you’ve made a profit; if negative, you’ve incurred a loss.
4. Reporting and Tax Implications:
It’s essential to report all capital gains accurately on relevant tax forms such as Schedule D in the United States or their equivalents in other countries. Failure to report capital gains correctly may result in penalties or audits by tax authorities.
Tax Rates for Capital Gains:
As mentioned earlier, short-term and long-term capital gains often have different tax rates due to favorable treatment for long-term holdings. In many jurisdictions like the U.S., long-term capital gains are subject to lower tax rates compared to ordinary income tax rates applicable to short-term capital gains.
The specific tax rates depend on various factors such as an individual’s taxable income level and filing status (e.g., single versus married). It is advisable for individuals with significant capital gains exposure to consult with a qualified tax professional who can provide personalized advice based on their unique circumstances.
Offsetting Capital Gains:
Capital losses can be used to offset capital gains, reducing the tax liability for individuals. If an individual has more capital losses than gains in a given year, they may be able to use the excess loss to offset other taxable income up to a certain limit (e.g., $3,000 per year in the U.S.). Unused losses can also be carried forward into future years.
Conclusion:
Calculating capital gains is crucial for investors and individuals who own assets that appreciate over time. By understanding the various components involved in determining cost basis and factoring adjustments accurately, one can calculate their true capital gain or loss upon selling an asset. It’s important to keep proper records of all transactions and consult with a tax professional when needed to ensure compliance with relevant tax laws.