Cracking the Code: Decoding Credit Score Ranges
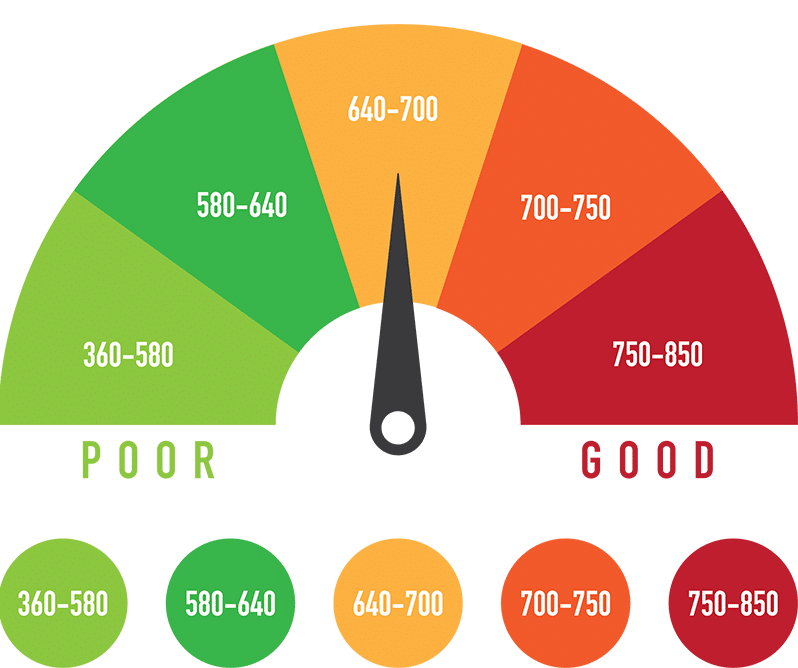
Credit Score Ranges and What They Mean
In the world of personal finance, credit scores play a crucial role in determining an individual’s financial health. A credit score is a numerical representation of a person’s creditworthiness based on their credit history. Lenders and creditors use this score to evaluate the risk associated with extending credit to an individual.
Understanding credit score ranges can help individuals gauge where they stand financially and make informed decisions about borrowing money or applying for loans. In this article, we will explore different credit score ranges, what they mean, and how they can impact your financial life.
FICO Score Range
The most commonly used scoring model is the FICO (Fair Isaac Corporation) score, which ranges from 300 to 850. It is important to note that different lenders may have varying criteria for evaluating credit scores, but generally speaking, here are the five broad categories into which these scores fall:
1. Poor Credit (300-579):
A poor credit score reflects a high level of risk for lenders. Individuals in this range may have a history of late payments, defaulted accounts, or even bankruptcy filings. Accessing new lines of credit at favorable terms becomes challenging with such low scores.
2. Fair Credit (580-669):
A fair credit score suggests some improvement compared to poor credit but still poses moderate risks for lenders. People with fair scores might have occasional late payments or higher utilization rates on their existing lines of credits.
3. Good Credit (670-739):
A good credit score indicates responsible financial behavior and demonstrates lower risks for lenders when extending new lines of credits or loans. Individuals in this range typically pay bills on time and maintain low levels of outstanding debt.
4. Very Good Credit (740-799):
With very good scores comes greater access to favorable interest rates and loan terms from lenders due to decreased perceived risk levels. These individuals usually have long-standing positive payment histories coupled with low utilization ratios.
5. Exceptional Credit (800-850):
An exceptional credit score puts individuals in the top tier of borrowers. Lenders view them as highly reliable and trustworthy, leading to preferential treatment such as lower interest rates, higher credit limits, and more favorable loan terms. Achieving an exceptional score requires a long track record of responsible financial management.
VantageScore Range
Apart from FICO scores, VantageScore is another popular scoring model used by lenders and creditors. While it uses a slightly different range from 300 to 850, the general categories are similar:
1. Poor Credit (300-499):
Similar to FICO scores, this range indicates high-risk borrowers with significant negative information on their credit reports that may include bankruptcies or multiple accounts in collections.
2. Fair Credit (500-600):
Individuals falling into this category have made some progress but still display signs of financial instability like late payments or high utilization ratios.
3. Good Credit (601-750):
A good VantageScore suggests stability and reliability when it comes to managing finances effectively. Borrowers with scores in this range are likely to be approved for credit at competitive rates.
4. Excellent Credit (751-850):
Those who fall within this range enjoy access to better terms on loans and lines of credit due to their low perceived risk level for lenders and creditors.
Credit Score Importance
Understanding the significance of credit scores is crucial because they impact various aspects of our financial lives:
1. Loan Approvals:
Lenders use your credit score as one factor among many when deciding whether or not to approve a loan application. A higher score increases your chances of getting approved while also potentially securing better interest rates.
2. Interest Rates:
Having a good or excellent credit score can save you thousands of dollars over time by qualifying you for lower interest rates on mortgages, auto loans, or personal loans compared to someone with poor or fair credit.
3. Credit Card Applications:
Credit card issuers evaluate your credit score to determine whether you are eligible for their cards and what interest rates they can offer you. Higher scores increase your chances of being approved for premium credit cards with better rewards and benefits.
4. Rental Applications:
Landlords often run credit checks on prospective tenants to assess their financial responsibility. A higher credit score can improve your chances of securing a rental property over someone with a lower score.
5. Insurance Premiums:
In some cases, insurers consider credit scores when calculating premiums for auto or home insurance policies. Individuals with higher scores could benefit from lower insurance costs.
Improving Your Credit Score
If you find yourself in the poor or fair credit range, there are steps you can take to improve your score:
1. Pay Bills on Time: Consistently paying bills by their due dates helps establish a positive payment history, which is one of the most significant factors impacting your credit score.
2. Reduce Debt: Lowering outstanding balances on loans and lines of credits decreases your overall utilization ratio, improving your creditworthiness.
3. Avoid New Credit Inquiries: Multiple inquiries within a short period can negatively impact your score as it may appear that you are seeking excessive amounts of new credit.
4. Monitor Your Credit Report: Regularly review your credit report to ensure its accuracy and address any errors promptly.
Conclusion
Credit scores have become an essential tool in evaluating an individual’s financial health and determining their eligibility for various forms of borrowing or lending opportunities. Understanding the different ranges and what they mean helps individuals make informed decisions about managing their finances effectively while striving towards achieving excellent financial standing through responsible behavior and practices.