The Importance of Liquidity in Personal Finance: Exploring Key Concepts and Strategies
Liquidity is a fundamental concept in finance that refers to the ease with which an asset or security can be bought or sold without causing significant price movement. It plays a crucial role in maintaining financial stability and ensuring the smooth functioning of capital markets. In this article, we will explore various subtopics related to liquidity and discuss their significance in personal finance.
1. Illiquid Assets:
Illiquid assets are those that cannot be easily converted into cash without causing substantial delays or losses. Examples include real estate, private equity investments, and certain types of bonds. Investing in illiquid assets can offer higher potential returns but comes with the risk of limited marketability. Individuals must carefully consider their investment horizon and financial needs before allocating funds to illiquid assets.
2. Liquidity Risk Management:
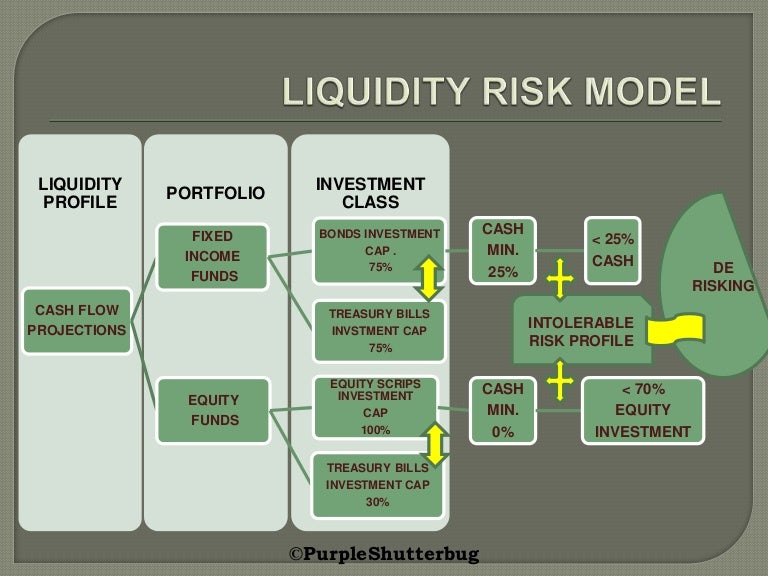
Liquidity risk management involves assessing and managing the potential risks associated with a lack of liquidity on both individual and systemic levels. Financial institutions employ various strategies, such as maintaining sufficient reserves or establishing contingency funding plans, to mitigate this risk effectively.
3. Cash Flow Forecasting:
Cash flow forecasting is an essential tool for individuals and businesses alike to monitor their inflows and outflows of cash over a specific period. By accurately projecting future cash flows, individuals can make informed decisions regarding budgeting, spending, saving, and investing.
4. Emergency Funds:
Emergency funds serve as a safety net during unexpected financial crises or emergencies such as job loss or medical expenses. These funds should ideally cover three to six months’ worth of living expenses and be readily accessible in highly liquid accounts like savings accounts or money market funds.
5. Liquidation Value:
Liquidation value represents the estimated amount that could be realized from selling an asset quickly at current market prices under distress conditions (such as bankruptcy). It provides an indication of the minimum value investors may expect to receive if forced to sell off assets hastily.
6. Liquidity Ratios:
Liquidity ratios are financial metrics used to assess an individual’s or company’s ability to meet short-term obligations. Common liquidity ratios include the current ratio (current assets divided by current liabilities) and the quick ratio (liquid assets divided by current liabilities).
7. Liquidity Preference Theory:
The liquidity preference theory, proposed by economist John Maynard Keynes, suggests that individuals prefer to hold cash rather than risky investments due to uncertainty about future events. This theory helps explain why interest rates may fluctuate based on changes in demand for money.
8. Market Liquidity vs Funding Liquidity:
Market liquidity refers to the ease with which a security can be bought or sold without significantly impacting its price, while funding liquidity pertains to an entity’s ability to obtain financing or sell assets quickly at minimal cost. Both types of liquidity are crucial for financial stability and efficient market functioning.
9. Liquidity Traps:
Liquidity traps occur when central banks’ efforts to stimulate economic growth through monetary policy become ineffective because interest rates are already near zero, reducing the incentive for individuals and businesses to borrow and spend.
10. Liquidity Black Holes:
Liquidity black holes represent situations where there is a severe lack of market participants willing to buy certain assets or provide funding, leading to illiquid markets and potentially exacerbating financial crises.
11. Contingency Funding Plans:
Contingency funding plans outline strategies that financial institutions have in place during times of stress or crisis when regular sources of funding become limited or unavailable. These plans ensure that institutions can continue operating smoothly even under adverse conditions.
12. Liquidity Stress Testing:
Liquidity stress testing involves assessing how well an individual or organization could withstand severe shocks in terms of liquidity needs and potential cash flow disruptions. The tests help identify vulnerabilities and develop appropriate risk management strategies.
13. Asset-Liability Mismatch and Liquidity Gaps:
An asset-liability mismatch occurs when the maturity profile of an institution’s assets does not align with its liabilities. This mismatch can create liquidity gaps, where the institution may struggle to meet funding requirements or face difficulties in selling assets to generate cash.
14. Liquidity Coverage Ratio (LCR):
The liquidity coverage ratio is a regulatory requirement that mandates financial institutions to maintain sufficient high-quality liquid assets to meet their short-term obligations during a specified stress period. It aims to enhance banks’ resilience and reduce the risk of liquidity problems.
15. Collateralized Loan Obligations (CLOs) and Liquidity Concerns:
Collateralized loan obligations are structured financial products backed by pools of loans, often including corporate debt or mortgages. Concerns about CLOs arise when there is limited demand for them due to concerns about credit quality or market conditions, leading to potential liquidity issues.
16. Secondary Market Liquidity for Bonds and Stocks:
Secondary market liquidity refers to the ease with which bonds and stocks can be traded on exchanges or other platforms after their initial issuance. High secondary market liquidity ensures that investors can easily buy or sell securities at fair prices.
17. Illiquidity Discounts in Valuation:
Illiquidity discounts reflect the reduced value assigned to an asset due to its lack of marketability or difficulty in finding buyers willing to pay full price promptly. These discounts are applied during valuation exercises, such as determining the worth of shares in private companies or certain illiquid investments.
18.Impact of Interest Rates on Liquidity:
Changes in interest rates have significant implications for overall market liquidity as they influence borrowing costs and individual preferences for holding cash versus investing in higher-yielding assets like stocks or bonds.
19.Cross-Asset Liquidity Correlations:
Cross-asset liquidity correlations refer to how changes in the liquidity of one asset class affect others across different markets. Understanding these correlations is crucial for diversification strategies and risk management efforts.
20.Role of Central Banks in Maintaining Market Liquidity:
Central banks play a vital role in maintaining market liquidity by providing liquidity support to financial institutions during times of stress, managing interest rates, and implementing monetary policies aimed at promoting stability and economic growth.
In conclusion, understanding the various aspects of liquidity is crucial for individuals managing their personal finances. From assessing risk to planning for emergencies, considering factors such as illiquid assets, cash flow forecasting, and different types of liquidity ratios can help individuals make informed decisions about their financial well-being. Moreover, comprehending broader concepts like market liquidity versus funding liquidity or the role of central banks in maintaining market stability helps individuals navigate an increasingly complex financial landscape.