“Unlocking Home Equity: Choosing Between Loans and Mortgages for Extra Cash”
Home Equity Loans vs. Second Mortgages: Understanding the Differences and Choosing Wisely
When homeowners find themselves in need of extra cash, they often turn to their home’s equity as a potential solution. Two common options that people consider are home equity loans and second mortgages. While these terms are sometimes used interchangeably, it’s important to understand that they refer to two distinct financial products. In this article, we will explore the differences between home equity loans and second mortgages, along with their pros and cons, helping you make an informed decision about which option is right for you.
Understanding Home Equity Loans
A home equity loan is a type of loan where borrowers use the equity built up in their homes as collateral. Equity represents the portion of your property that you truly own – the difference between its market value and any outstanding mortgage balance.
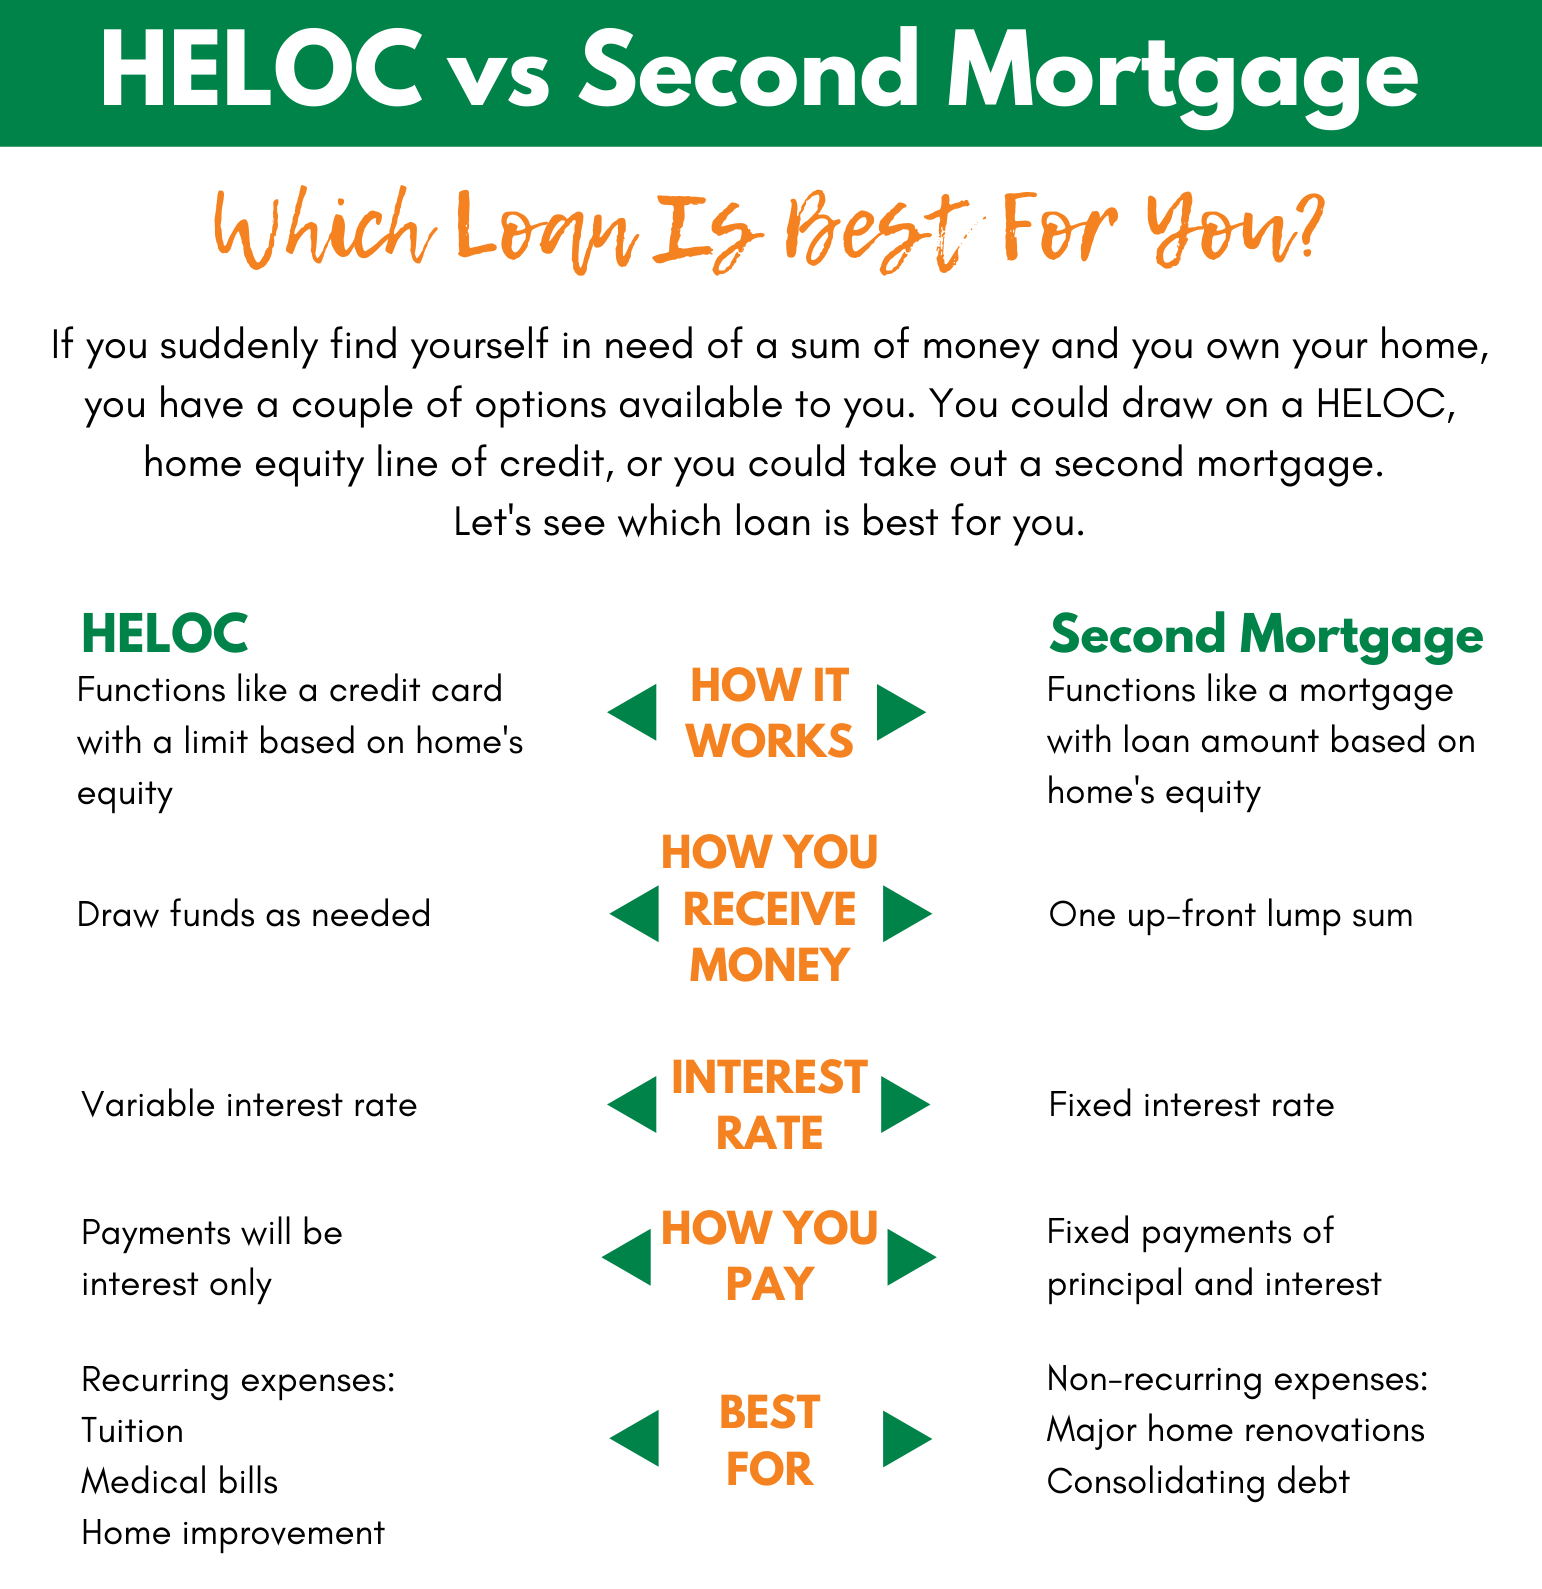
Home equity loans typically come with fixed interest rates and are disbursed as lump-sum payments at the beginning of the loan term. These loans have a predetermined repayment period ranging from five to thirty years, during which borrowers make monthly payments until the debt is fully paid off.
The Pros of Home Equity Loans:
1. Fixed Interest Rates: One significant advantage of a home equity loan is having a fixed interest rate throughout the entire repayment term. This stability allows borrowers to budget effectively without worrying about fluctuating monthly payments.
2. Lump-Sum Disbursement: With a home equity loan, you receive all funds upfront after approval, giving you immediate access to capital for large expenses such as medical bills or home renovations.
3. Tax Deductibility: In many cases (subject to local tax laws), interest paid on home equity loans may be tax-deductible if used for specific purposes like improving your primary residence or investing in real estate.
4. Lower Interest Rates than Credit Cards: Compared to credit cards or personal loans, home equity loans generally offer lower interest rates due to using your property as collateral.
The Cons of Home Equity Loans:
1. Risking Your Home: By using your home as collateral, you are putting it at risk. If you fail to repay the loan as agreed, your lender can initiate foreclosure proceedings and take possession of your property.
2. Closing Costs: Similar to when taking out a mortgage, home equity loans involve closing costs such as application fees, appraisal fees, and attorney fees. These costs can add up and must be factored into the overall financial decision.
3. Inflexible Repayment Terms: Once you sign the loan agreement for a home equity loan, the repayment terms are fixed and cannot be changed easily. This lack of flexibility may limit your ability to adjust payments based on unforeseen circumstances or changes in income.
Understanding Second Mortgages
A second mortgage is another type of loan that allows homeowners to tap into their property’s equity while keeping their existing first mortgage intact. Unlike refinancing options that replace the original mortgage with a new one, second mortgages are additional loans taken out alongside the primary mortgage.
Second mortgages come in two main types: home equity lines of credit (HELOCs) and closed-end loans (also known as installment loans). Each has its own features and repayment structures.
HELOCs:
Home equity lines of credit function similarly to credit cards but with much lower interest rates due to being secured by your property’s value. With a HELOC, borrowers have access to a predetermined line of credit which they can draw from whenever needed during an initial “draw period” (typically 5-10 years). During this time, borrowers only pay interest on the amount withdrawn rather than the entire line of credit available.
Closed-End Loans:
Closed-end second mortgages operate more like traditional installment loans where borrowers receive funds upfront and make regular monthly payments over a set term until fully repaid. Interest rates for closed-end loans tend to be higher than those of HELOCs, but borrowers have the advantage of knowing exactly when the debt will be paid off.
The Pros of Second Mortgages:
1. Flexibility in Usage: With a second mortgage, you can use the funds for any purpose, including consolidating high-interest debts, funding education expenses, or investing in home improvements.
2. Lower Interest Rates: Similar to home equity loans, second mortgages generally offer lower interest rates compared to credit cards or personal loans because they are secured by your property’s value.
3. Potential Tax Benefits: Depending on local tax laws and specific circumstances, interest paid on second mortgages may be tax-deductible under certain conditions.
The Cons of Second Mortgages:
1. Increased Debt Burden: Taking on a second mortgage means increasing your overall debt load and potentially extending your repayment period. It is important to carefully consider whether you can afford the additional monthly payments.
2. Risking Your Home: Just like with home equity loans, failure to meet repayment obligations can result in foreclosure proceedings initiated by the lender.
3. Closing Costs and Fees: When taking out a second mortgage, borrowers need to factor in closing costs such as application fees, appraisal fees, and attorney fees.
Choosing Between a Home Equity Loan and a Second Mortgage
To make an informed decision about whether a home equity loan or second mortgage is right for you, consider the following factors:
1. Financial Needs:
– Do you need immediate access to a large lump sum (home equity loan) or prefer flexibility with ongoing access to funds (HELOC)?
– Are you looking for funds primarily for one-time expenses (closed-end loan) or anticipate ongoing needs over an extended period?
2. Repayment Ability:
– Can you comfortably manage fixed monthly payments that come with a home equity loan?
– Are you confident in your ability to manage variable interest rates during the draw period if considering a HELOC?
3. Risk Tolerance:
– Are you comfortable using your home as collateral?
– Do you have a stable income and emergency savings to mitigate any potential risks associated with borrowing against your property?
4. Long-term Financial Goals:
– How does taking on additional debt align with your overall financial plans?
– Will the benefits of accessing funds through a home equity loan or second mortgage outweigh the costs in achieving your goals?
Ultimately, choosing between a home equity loan and a second mortgage depends on individual circumstances, preferences, and financial goals. It is crucial to carefully consider all aspects before making a decision. Consulting with an experienced mortgage professional or financial advisor can provide valuable insights tailored to your specific situation.
Conclusion
Whether it’s funding home improvements, consolidating debts, or covering unexpected expenses, tapping into the equity accumulated in your home can be an attractive option for homeowners needing extra cash. Home equity loans and second mortgages provide viable solutions with their own advantages and considerations.
A home equity loan offers a fixed interest rate and lump-sum disbursement but comes with inflexible repayment terms and potential foreclosure risk if payments are not met. On the other hand, second mortgages offer more flexibility in usage but involve higher interest rates than some home equity loans.
To choose wisely between these options, evaluate your needs, repayment ability, risk tolerance, and long-term financial goals carefully. By understanding the nuances of each product while considering personal circumstances, homeowners can make informed decisions that best suit their specific needs while leveraging their most significant asset – their homes.