Maximizing Your Investments: Mastering the Art of Calculating Cost Basis for Capital Losses
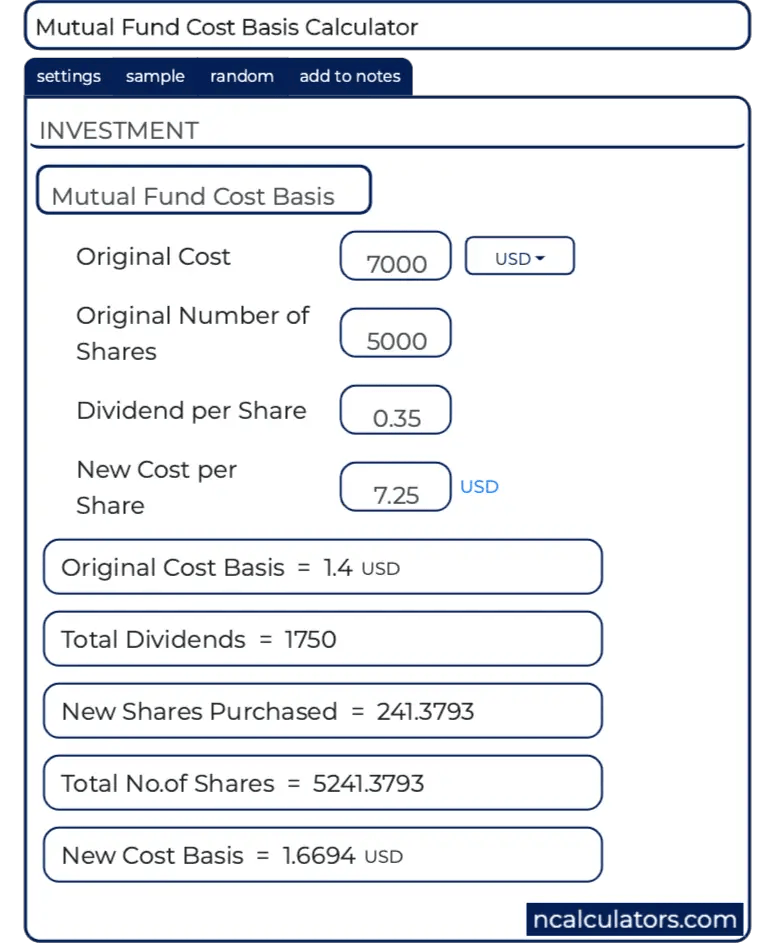
When it comes to investing, understanding how to calculate the cost basis of a sold asset with a capital loss is crucial. Not only does it help you track your investment performance accurately, but it also allows you to optimize your tax liabilities. In this article, we will provide an overview of what cost basis is, why it matters in calculating capital losses, and how you can determine the cost basis for a sold asset.
Cost basis refers to the original value of an asset for tax purposes. It includes the purchase price along with any additional costs incurred during the acquisition process, such as broker fees or commissions. This figure is essential because it is used to determine capital gains or losses when selling an investment.
Calculating the cost basis becomes particularly important when dealing with capital losses. A capital loss occurs when you sell an investment at a lower price than its original cost basis. By properly calculating your capital loss, you can potentially offset taxable gains from other investments and reduce your overall tax liability.
To calculate the cost basis of a sold asset with a capital loss, start by gathering all relevant information related to its acquisition. This includes the purchase price and date, as well as any additional expenses incurred during the transaction. It’s important to keep accurate records of these details for future reference.
Once you have gathered all necessary information, subtract any depreciation or amortization claimed on the asset from its original purchase price. These adjustments reflect changes in value over time and should be factored into determining your adjusted cost basis.
Next, add any additional costs associated with acquiring the asset that were not included in the initial purchase price. These may include broker fees or commissions paid at the time of acquisition.
After determining your adjusted cost basis using these calculations, subtract the final sale price from this figure to arrive at your realized capital loss amount. This result represents how much money was lost on that particular investment.
It’s worth noting that there are different methods available for calculating cost basis, such as the first-in, first-out (FIFO) method or specific identification. The FIFO method assumes that the first assets purchased are also the first ones sold, while specific identification allows you to choose which assets are being sold based on individual purchase prices.
It’s important to consult with a tax professional or financial advisor when calculating your cost basis and capital losses. They can provide guidance tailored to your specific situation and help ensure compliance with tax regulations.
In summary, accurately calculating the cost basis of a sold asset with a capital loss is crucial for both tracking investment performance and optimizing tax liabilities. By gathering all relevant information about the acquisition and applying appropriate adjustments, you can determine your adjusted cost basis. Subtracting the final sale price from this figure will yield your realized capital loss amount. Remember to consult professionals in order to make informed decisions regarding these calculations and optimize your financial outcomes.