Rebuilding Credit: Overcoming Setbacks and Securing Your Financial Future
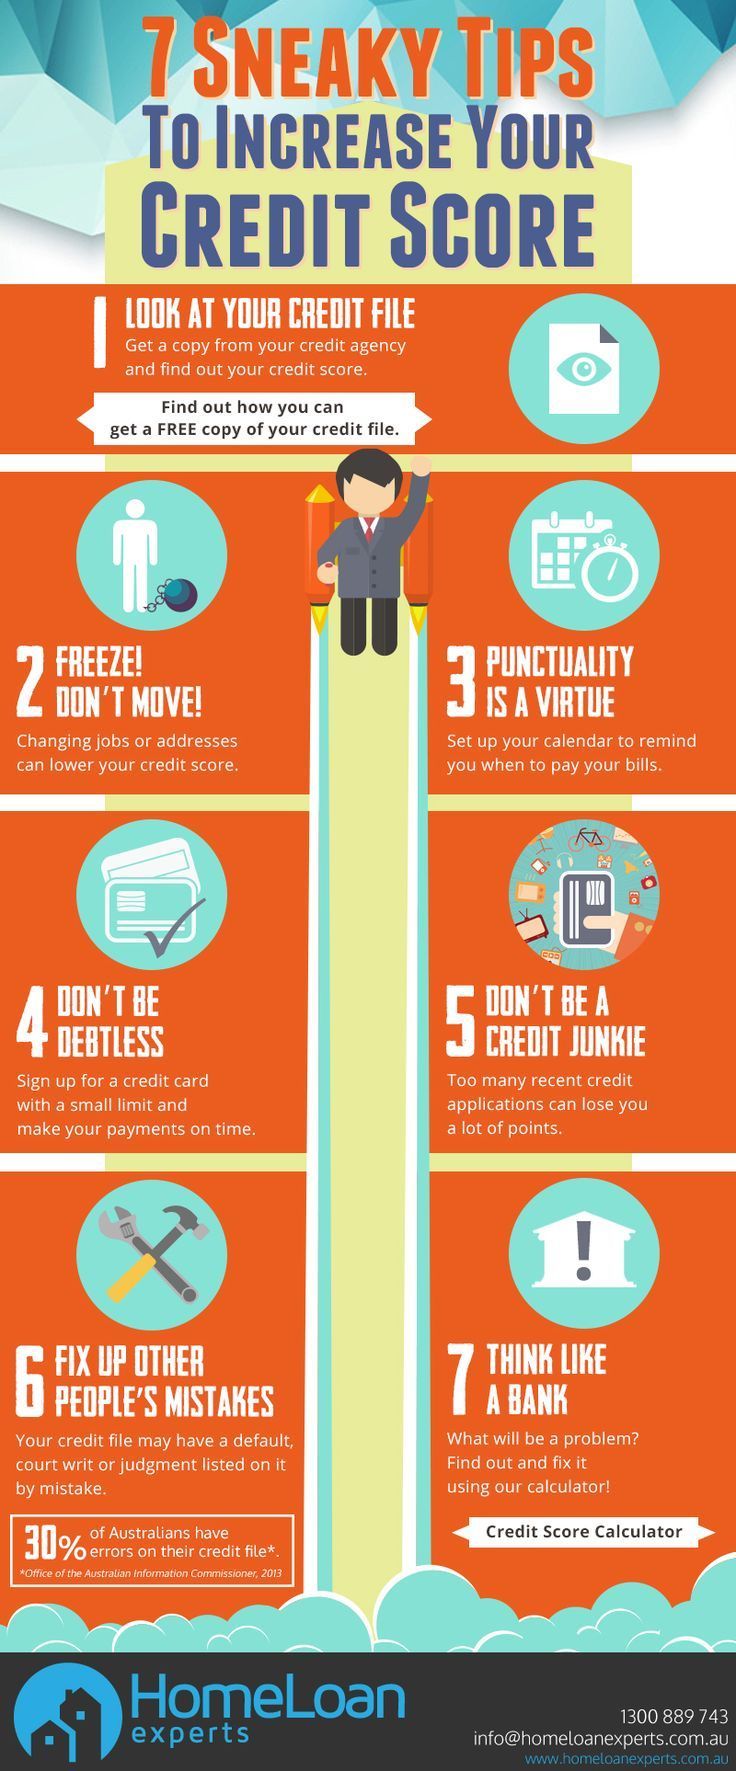
Rebuilding Credit After Financial Setbacks
Financial setbacks can happen to anyone at any time. Whether it’s due to unexpected medical expenses, job loss, or poor financial decisions, a damaged credit score can make it difficult to secure loans, rent an apartment, or even get approved for a credit card. However, with patience and perseverance, it is possible to rebuild your credit and regain control of your financial future.
1. Assess the damage: The first step in rebuilding your credit is to understand where you currently stand. Obtain copies of your credit reports from all three major credit bureaus – Equifax, Experian, and TransUnion – and carefully review them for errors or inaccuracies. Dispute any discrepancies you find and work towards resolving them as quickly as possible.
2. Create a budget: Developing a realistic budget is crucial when rebuilding your credit score. Evaluate your monthly income and expenses to determine how much money you have available to pay off debts or save for emergencies. Prioritize paying down high-interest debt first while ensuring that you continue making minimum payments on other accounts.
3. Make timely payments: Consistently making on-time payments is one of the most effective ways to rebuild your credit history over time. Paying bills before their due date demonstrates responsibility and improves your payment history – an essential factor in determining your creditworthiness.
4. Reduce outstanding debts: High levels of debt can significantly impact your credit score negatively. Develop a plan to reduce outstanding balances by paying more than the minimum amount due each month whenever possible. Consider strategies like the snowball method (paying off smaller debts first) or the avalanche method (paying off higher interest rate debts first) based on what works best for you.
5. Build new positive lines of credit: If you’ve had difficulty obtaining traditional forms of credit after facing financial setbacks, consider alternative options such as secured cards or becoming an authorized user on someone else’s account. Secured credit cards require a cash deposit upfront, which serves as collateral. By using the card responsibly and making timely payments, you can gradually rebuild your creditworthiness.
6. Seek professional help if needed: If you’re overwhelmed or struggling to navigate the process of rebuilding your credit on your own, consider seeking guidance from a reputable credit counseling agency. These organizations can offer personalized advice and assistance in creating a debt management plan tailored to your specific needs.
7. Stay patient and persistent: Rebuilding credit takes time; there are no quick fixes or shortcuts. It requires discipline to consistently make responsible financial choices over an extended period. Remember that negative information typically remains on your credit report for seven years but has less impact on your score as time goes by.
8. Monitor progress regularly: As you work towards rebuilding your credit, it’s essential to monitor your progress regularly. Keep track of changes in your credit scores and review updated copies of all three major credit reports at least once per year to ensure accuracy.
In conclusion, rebuilding credit after financial setbacks may seem like an uphill battle, but it is entirely possible with determination and careful planning. By assessing the damage, creating a budget, making timely payments, reducing outstanding debts, building new positive lines of credit, seeking professional help if needed, staying patient and persistent, and monitoring progress regularly – you can take significant steps towards improving your financial standing and securing a better future.