Mastering Your Auto Loan Principal Balance: Strategies for Debt Management
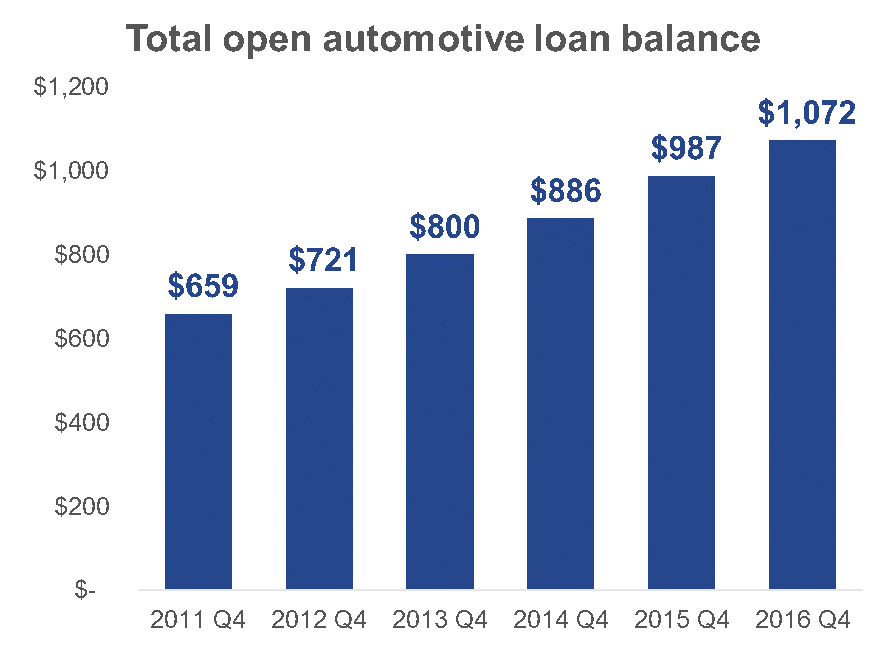
Auto Loan Principal Balance: Understanding and Managing Your Debt
When it comes to financing a car, most people opt for an auto loan. Auto loans allow individuals to purchase a vehicle without having to pay the full amount upfront. Instead, they make monthly payments over a specified period of time until the loan is fully repaid. One important concept in understanding auto loans is the principal balance.
What is Auto Loan Principal Balance?
The principal balance refers to the remaining amount owed on an auto loan at any given time. It represents the original loan amount minus any repayments made towards the principal, excluding interest charges and fees.
For example, if you took out an auto loan for $20,000 and have made payments totaling $5,000 so far, your principal balance would be $15,000 ($20,000 – $5,000). This figure decreases as you continue making regular payments toward your loan.
It’s crucial to understand that while each payment reduces your overall debt burden (the principal balance), a portion of each payment also goes towards paying off accrued interest charges associated with the loan.
How Does Interest Affect Your Principal Balance?
Interest is an additional cost imposed by lenders when providing funds through auto loans. It serves as compensation for lending money and can significantly impact your total repayment amount over time.
In simple terms, when you first take out an auto loan, most of your initial payments go towards paying off accumulated interest rather than reducing the actual principal balance. As more payments are made over time and more interest has been paid off initially; less will be allocated toward interest charges in subsequent months or years.
To better understand how much of each payment goes toward interest versus reducing the principal balance; it’s helpful to review an amortization schedule provided by your lender. This schedule outlines all scheduled monthly payments throughout the duration of your loan term along with their respective allocation between interest charges and reducing outstanding debt.
Managing Your Auto Loan Principal Balance
Now that we understand what the principal balance is and how it can be affected by interest charges let’s explore some strategies for managing your auto loan effectively:
1. Make Regular Payments: Consistently making on-time monthly payments is crucial to reducing your principal balance over time. Late or missed payments not only incur additional fees but also prolong the repayment period.
2. Pay More Than the Minimum: Whenever possible, consider paying more than the minimum required payment. By doing so, you can chip away at your principal balance faster and potentially save money on accumulated interest charges in the long run.
3. Refinance Your Loan: If market conditions have changed since you initially took out your auto loan; such as lower interest rates becoming available, it might be worth considering refinancing your loan. This process involves obtaining a new loan with better terms to replace your existing one, which could help reduce both monthly payments and the overall principal balance.
4. Avoid Extending Loan Terms: While extending the term of an auto loan may result in lower monthly payments; it also means a longer repayment period and potentially higher accumulated interest costs over time. It’s generally advisable to avoid extending the length of your loan term if possible unless there are significant financial constraints.
5. Consider Making Lump Sum Payments: If you come into extra funds through bonuses or windfalls, consider using them to make lump sum payments towards your principal balance rather than spending them elsewhere. Doing so will significantly reduce both total debt and future interest charges associated with your auto loan.
6. Keep Track of Your Credit Score: Maintaining a good credit score is essential when managing any type of debt, including auto loans. A higher credit score can often allow you to secure more favorable lending terms or refinance options down the line, ultimately helping manage and reduce your principal balance effectively.
Conclusion
Understanding and actively managing your auto loan principal balance is crucial for anyone looking to finance a car purchase. By making regular payments, paying more than the minimum required amount, and considering refinancing options, you can effectively reduce your principal balance over time. Remember to track your credit score and avoid extending loan terms unless necessary. With careful planning and financial discipline, you can successfully manage your auto loan debt and move towards a debt-free future.