“Unlocking the Secrets to Better Credit Scores and Lower Interest Rates”
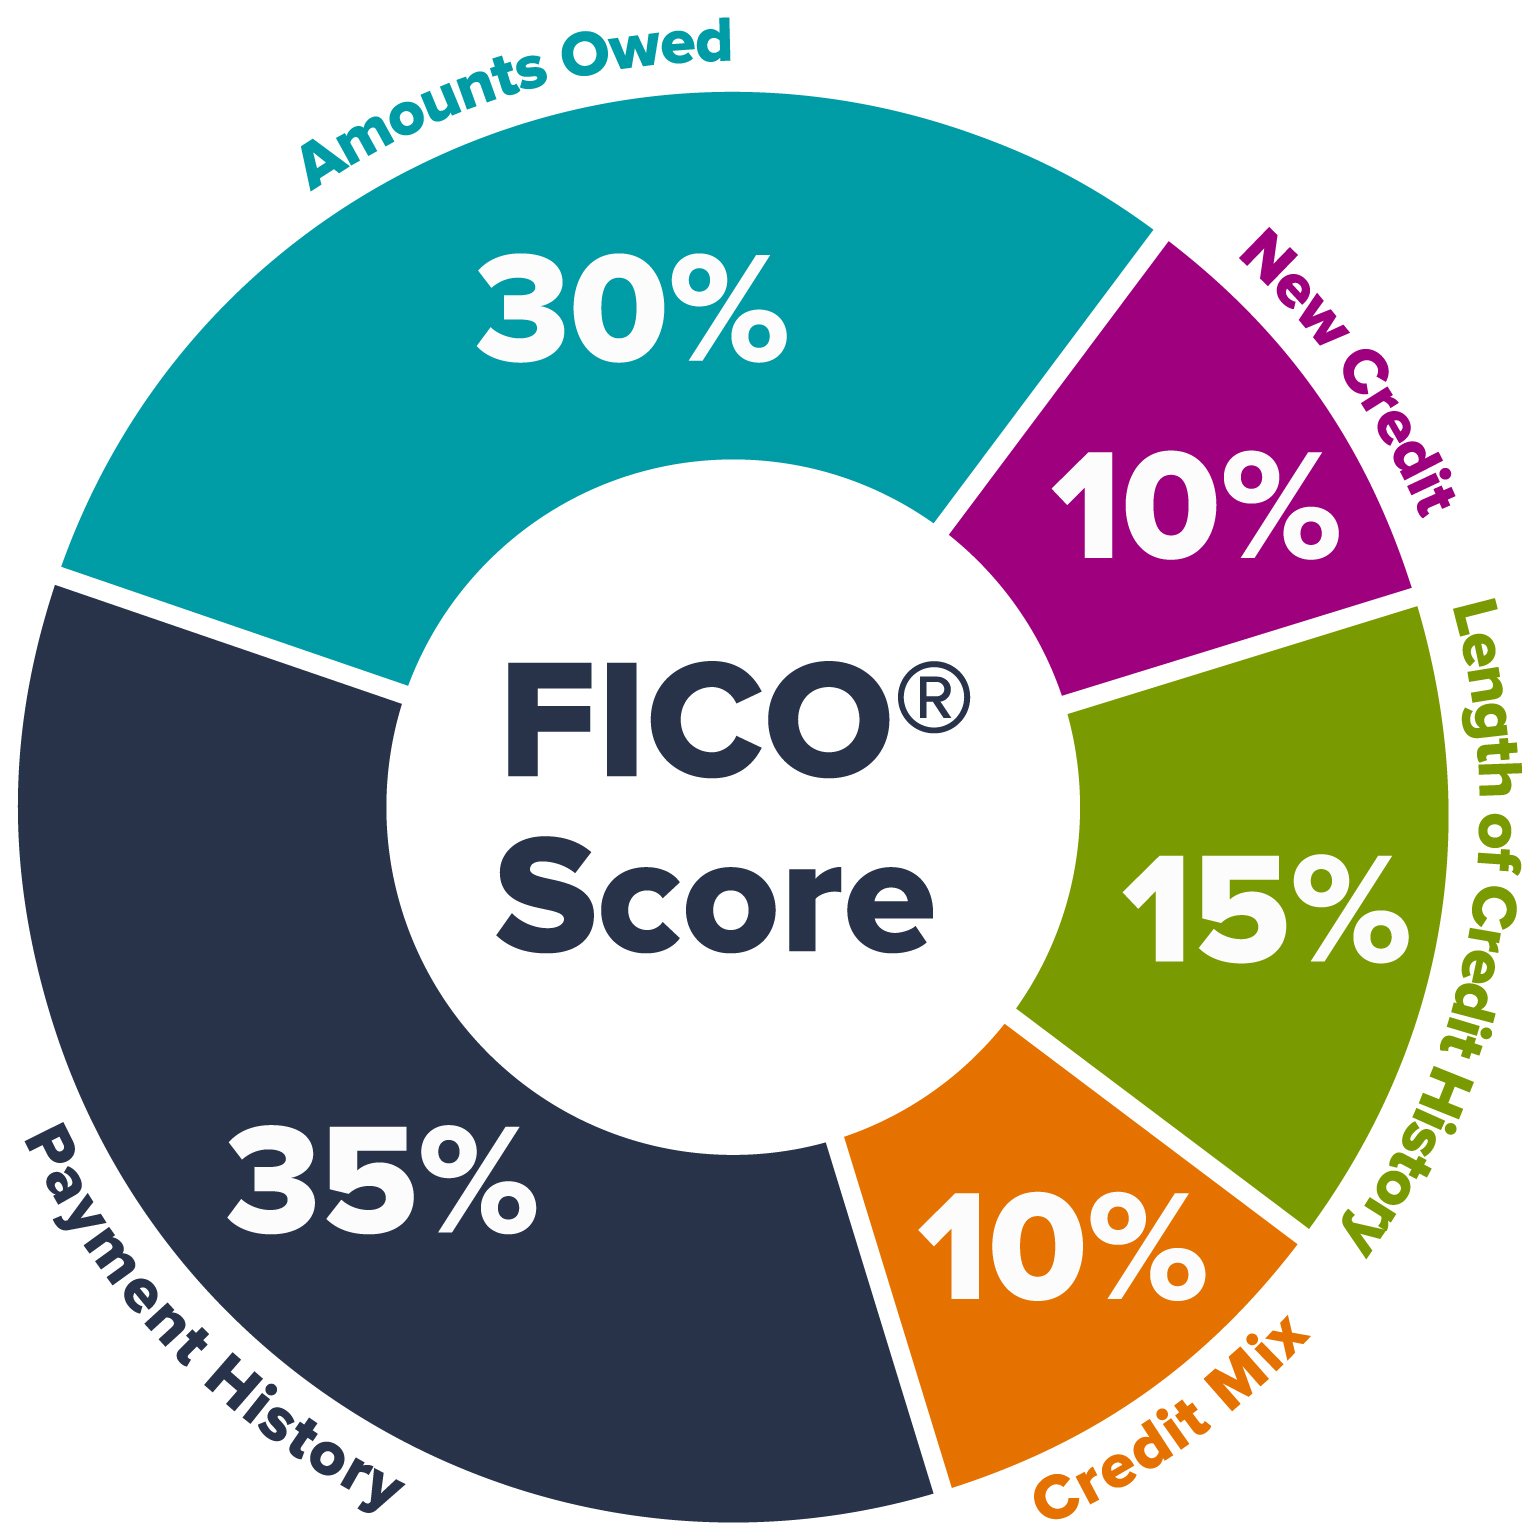
When it comes to personal finances, credit scores play a crucial role in determining an individual’s financial health. A credit score is a numerical representation of an individual’s creditworthiness and is used by lenders to assess the risk associated with lending money to someone. Understanding the factors that affect your credit score can help you make informed decisions about managing your finances and ultimately influence the interest rates you receive on personal loans.
One of the most significant factors affecting your credit score is payment history. Making timely payments on all your debts, such as credit cards, mortgages, and loans, demonstrates responsible financial behavior and positively impacts your credit score. On the other hand, missing payments or defaulting on loans can severely damage your creditworthiness and result in higher interest rates for future borrowing.
Another factor that influences your credit score is the amount of debt you owe compared to your available credit limit – also known as utilization ratio. Maintaining low balances on revolving accounts like credit cards indicates responsible usage of available credits. Higher utilization ratios suggest a greater reliance on borrowed funds and may indicate financial instability to potential lenders, resulting in higher interest rates.
The length of time you’ve had established lines of credit also affects your credit score. The longer you have successfully managed different forms of debt – be it student loans, car loans or mortgages – the more reliable you appear to creditors. This longevity reflects stability in handling various types of debt responsibly over time and can lead to lower interest rates on personal loans.
Credit mix refers to having a diverse range of debts such as installment loans (car loan) versus revolving accounts (credit card). Having a healthy mix shows that you can handle different types of obligations responsibly which often results in better terms for personal loan interests.
Lastly, new applications for additional lines of credits are considered when calculating an individual’s overall risk profile during lending decisions. Applying for multiple new lines within a short period may raise concerns among lenders regarding potential overextension or financial instability. Frequent applications for new credit can result in a lower credit score and higher interest rates on personal loans.
In conclusion, several key factors affect an individual’s credit score and consequently influence the interest rates offered by lenders. Maintaining a strong payment history, managing debt responsibly, having a long-established credit history, maintaining a diverse mix of debts and avoiding frequent applications for new lines of credit are all vital components to improving your creditworthiness. By understanding these factors and taking steps to improve your overall financial health, you can work towards securing better terms for personal loans in the future.