Unlocking Home Equity: Exploring the Pros and Cons of Reverse Mortgages
Reverse Mortgages: Understanding the Pros and Cons
Introduction:
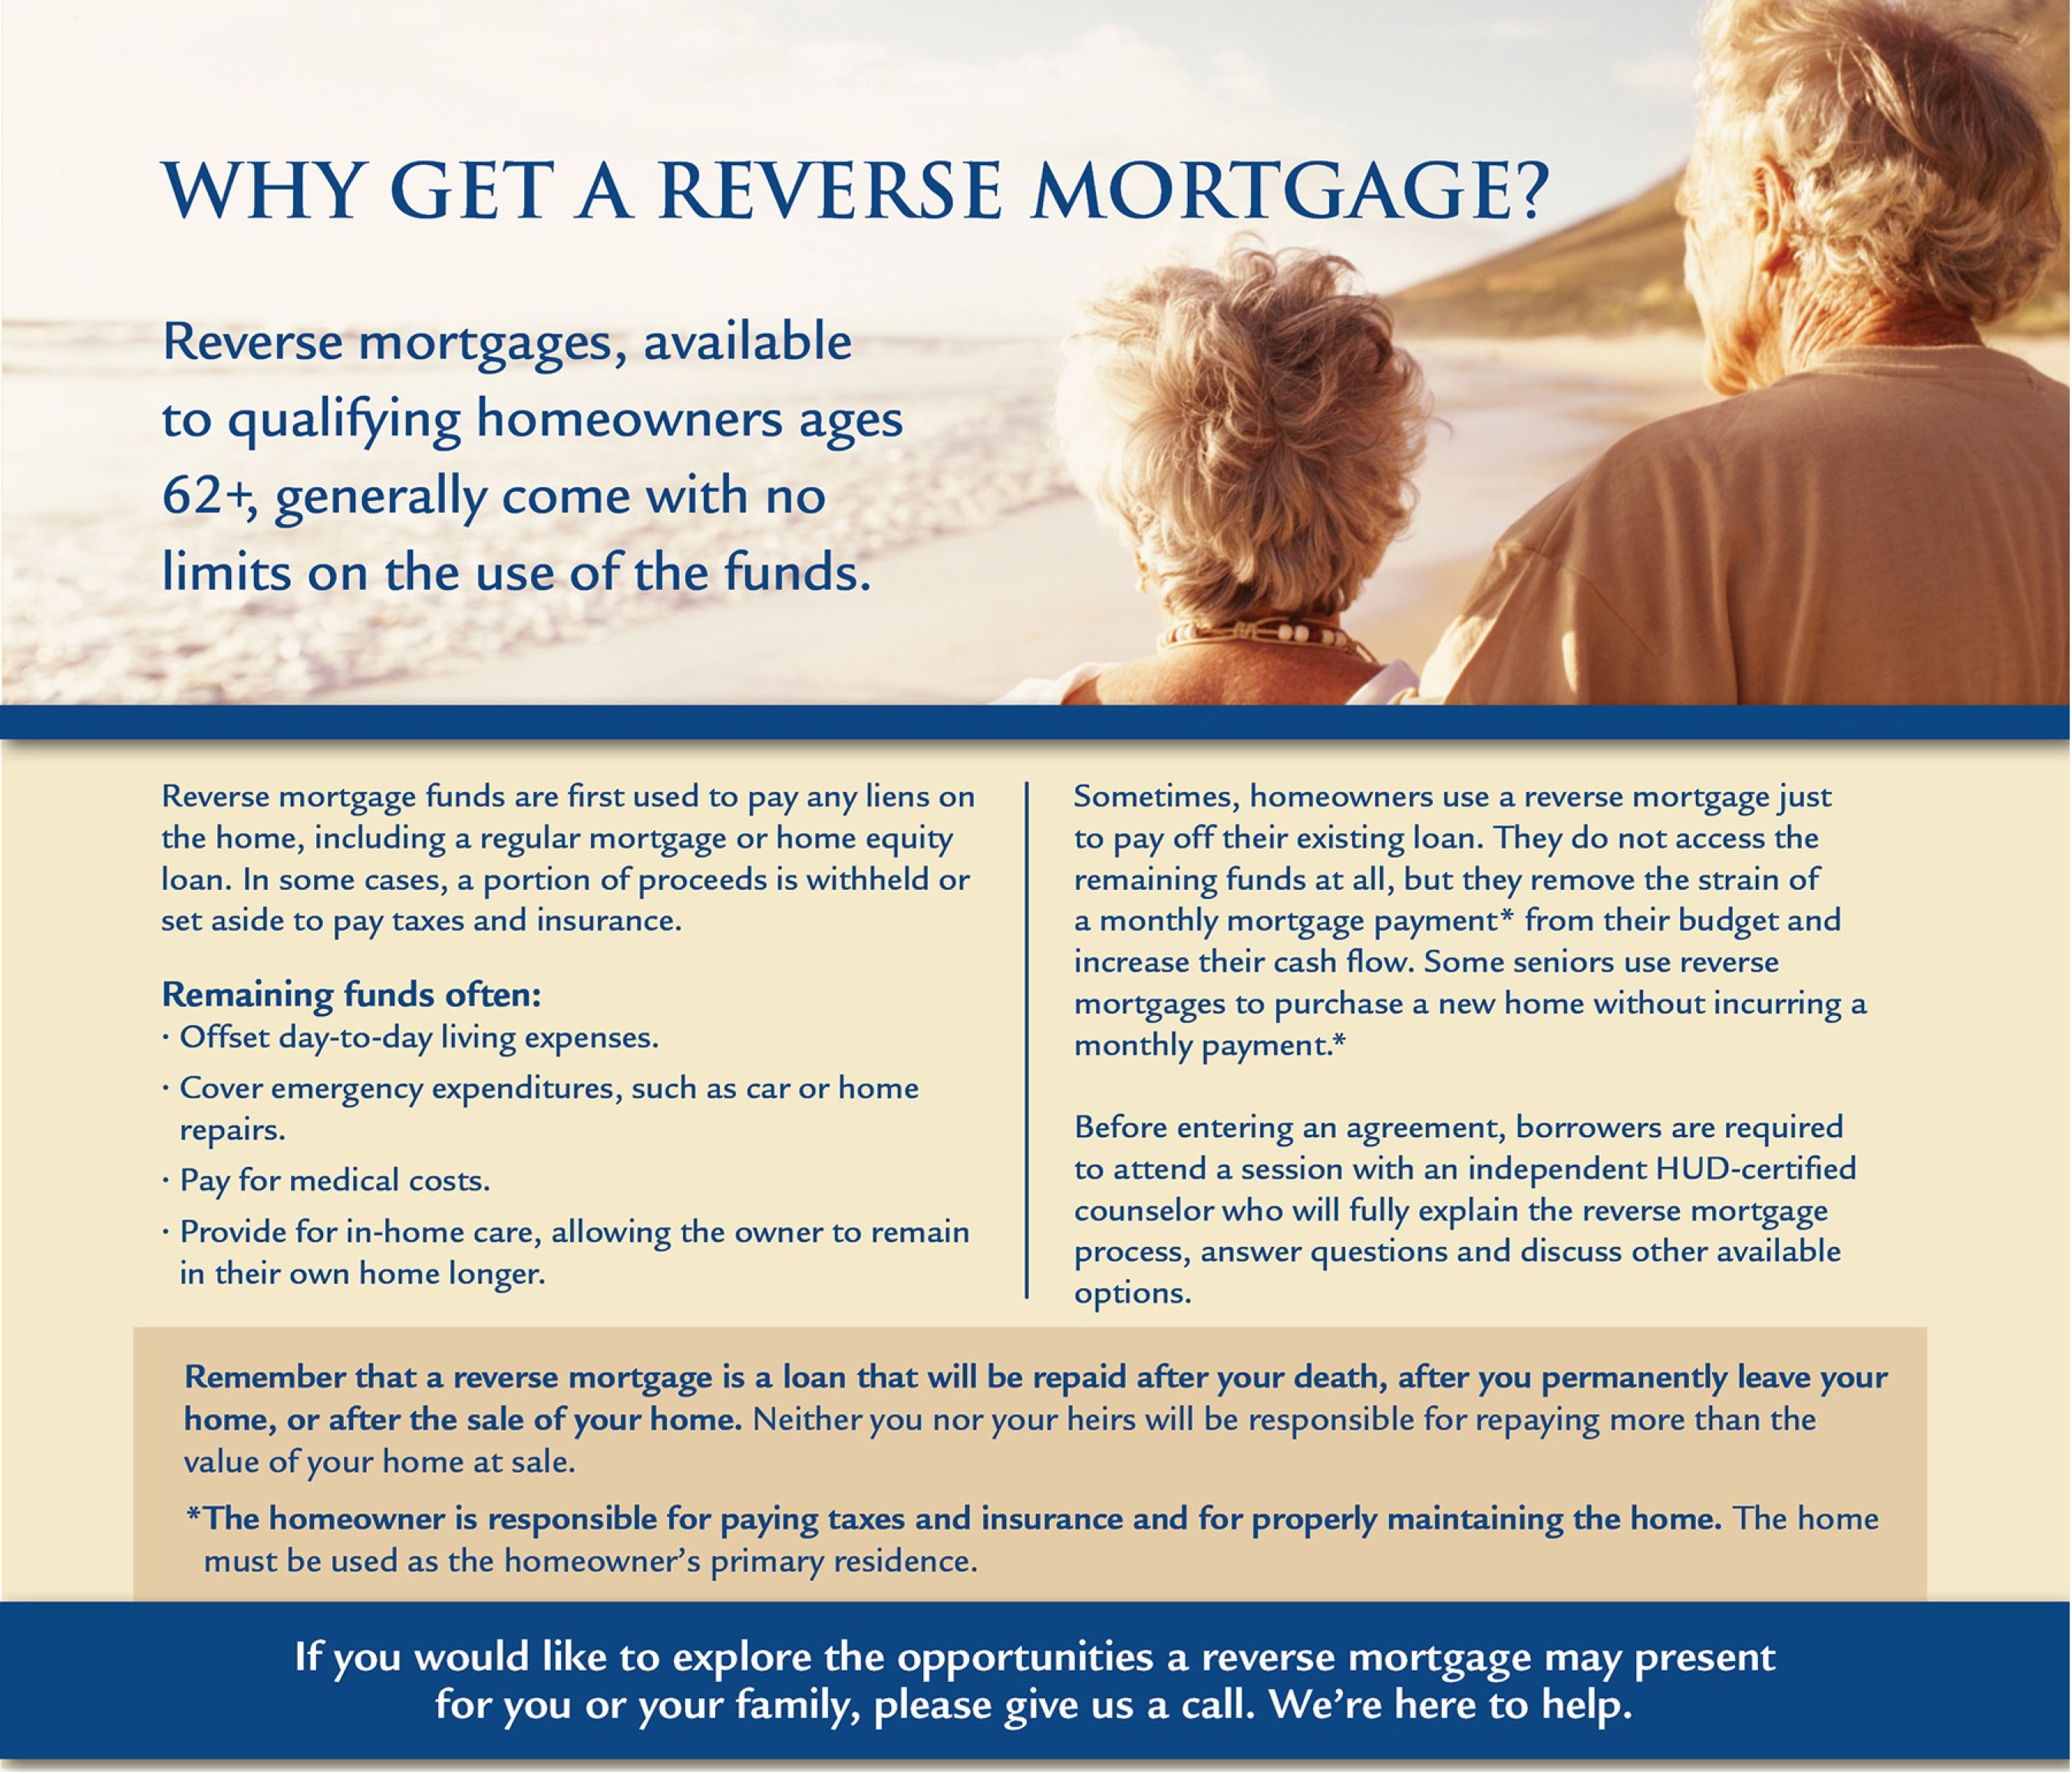
As retirement approaches, many individuals find themselves in need of additional funds to support their lifestyle. One option that has gained popularity in recent years is a reverse mortgage. A reverse mortgage allows homeowners who are aged 62 or older to convert part of their home equity into cash without having to sell or move out of their homes.
While reverse mortgages can provide a valuable source of income for retirees, it’s important to understand both the advantages and disadvantages before making a decision. In this article, we will explore how reverse mortgages work, the potential benefits and drawbacks, as well as alternative options for supplementing retirement income.
How do Reverse Mortgages Work?
A reverse mortgage is essentially a loan that enables homeowners to borrow against the equity they have built up in their homes over time. Unlike traditional mortgages where borrowers make monthly payments to reduce debt, with a reverse mortgage, the lender makes payments to the borrower based on either a lump sum payment, monthly installments, or through a line of credit.
The loan amount is determined by factors such as the age of the borrower(s), current interest rates, and the appraised value of the home. The homeowner retains ownership but must continue paying property taxes and maintaining insurance on the property.
Pros of Reverse Mortgages:
1. Supplemental Income: One major advantage of a reverse mortgage is that it provides retirees with an additional source of income during their retirement years when other sources may be limited.
2. No Monthly Payments: Unlike traditional loans where borrowers have monthly repayment obligations, with a reverse mortgage there are no required monthly payments.
3. Flexibility: Borrowers have flexibility in choosing how they receive funds – whether as lump sum payment(s), regular installments or through establishing a line of credit.
4. No Risk Of Losing Ownership: As long as borrowers meet certain conditions like living in the house and keeping up with property taxes and insurance, they can remain in the home for as long as they wish without fear of foreclosure.
Cons of Reverse Mortgages:
1. Accumulating Interest: The interest on a reverse mortgage accumulates over time and is added to the loan balance. This means that the total amount owed by borrowers increases over time, potentially reducing the equity left in their homes.
2. High Fees: Reverse mortgages often come with high upfront fees, including origination fees, closing costs, and insurance premiums. These costs can significantly impact the amount of funds available to borrowers.
3. Potential Impact on Heirs: Upon the death of the borrower(s), heirs may need to repay the loan or sell the property to settle it, which could reduce or eliminate any inheritance they were expecting.
4. Limited Eligibility: To qualify for a reverse mortgage, homeowners must be aged 62 or older and have sufficient home equity. If there is an existing mortgage on the property, it must be paid off using some of the proceeds from the reverse mortgage.
Alternatives to Reverse Mortgages:
While a reverse mortgage can be beneficial for some retirees facing financial challenges during retirement, it’s important to consider alternative options before making a decision.
1. Home Equity Line of Credit (HELOC): A HELOC allows homeowners to access their home’s equity through a line of credit that can be drawn upon when needed but does not require immediate repayment.
2. Downsizing: Selling one’s current home and moving into a smaller or less expensive property can provide additional funds while also potentially reducing expenses associated with maintenance and property taxes.
3. Renting Out Part of Property: Homeowners who have extra space in their homes may consider renting out rooms or portions of their properties as short-term rentals through platforms like Airbnb.
4. Personal Savings/Investments: Building up personal savings and investments throughout one’s working years can provide an alternative source of income during retirement.
Conclusion:
Reverse mortgages can be a valuable financial tool for retirees, providing them with the opportunity to tap into their home equity and supplement their retirement income. However, they come with potential risks and costs that need to be carefully considered.
Before deciding on a reverse mortgage, it’s crucial to explore other options, such as downsizing or utilizing personal savings. Consulting with a financial advisor who specializes in retirement planning can help individuals make an informed decision based on their unique circumstances.
Remember, the goal of any retirement plan is to ensure financial security while maintaining control over one’s assets. Understanding all available options and weighing the pros and cons will empower retirees to make the best choices for themselves and their families during their golden years.