From Ancient Civilizations to Modern Times: The Fascinating Evolution of Mortgages and Interest Rates
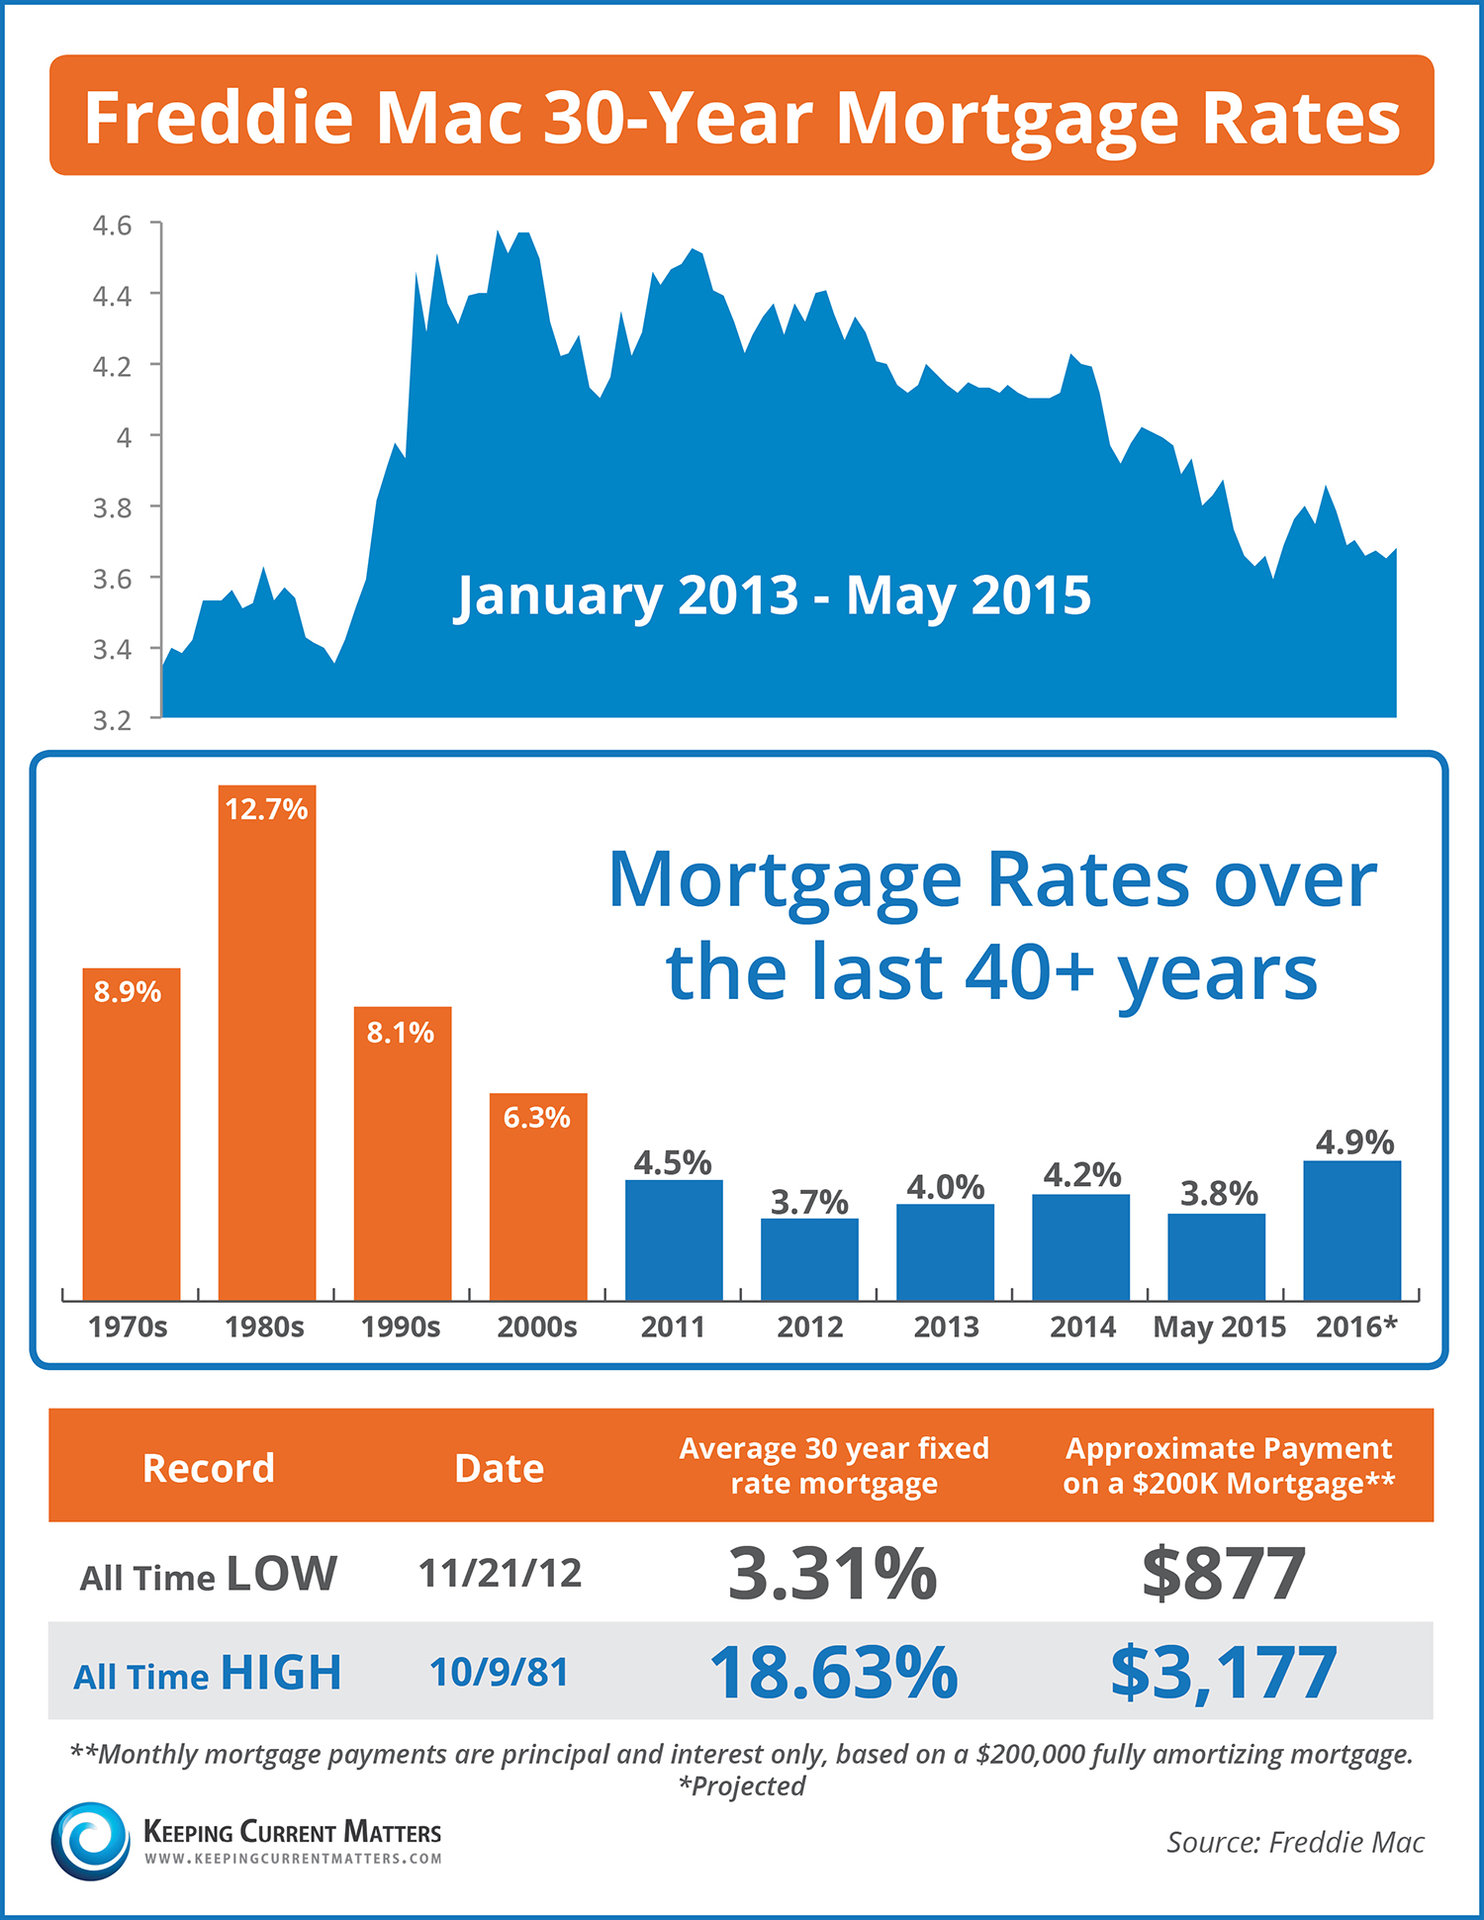
Mortgages and Interest Rates: A Historical Perspective
In today’s modern world, mortgages have become an integral part of the homebuying process. However, the concept of borrowing money to purchase a property is not a recent phenomenon. Throughout history, people have sought financial assistance to fulfill their dream of homeownership. This article aims to explore the historical development of mortgages and delve into the fascinating evolution of interest rates.
The origins of mortgages can be traced back thousands of years ago to ancient civilizations such as Mesopotamia and Egypt. In these early societies, loans were granted for various purposes, including land purchases. These loans were often provided by wealthy individuals or institutions like temples or palaces in exchange for collateral security.
Fast forward to medieval Europe, where landowners faced financial challenges due to wars and economic instability. It was during this time that mortgage contracts emerged as a way for borrowers to secure funds against their properties while still maintaining ownership. These agreements typically involved interest payments but lacked standardized terms and conditions.
It was not until the 17th century that formalized mortgage systems began appearing in countries like England and France. The British Statute of Frauds in 1677 laid down legal requirements for written mortgage agreements, ensuring transparency between lenders and borrowers. As banks started entering the lending market during this period, interest rates became more structured based on supply and demand dynamics.
Moving into the 19th century, several significant developments shaped the modern mortgage landscape we recognize today. The Industrial Revolution brought about rapid urbanization and increased demand for housing loans among the growing middle class population. Financial institutions adapted by offering longer loan durations with higher interest rates but also introduced default penalties as a safeguard against non-payment.
The early 20th century witnessed further refinements in mortgage practices following two World Wars and economic recessions that impacted global markets significantly. Governments around the world recognized housing as a crucial factor driving economic growth; thus, they implemented policies to encourage homeownership. This included the establishment of government-backed mortgage programs and institutions like the Federal Housing Administration (FHA) in the United States.
Interest rates during these times were influenced by various factors, including inflation, monetary policy decisions, and market forces. For instance, after the Great Depression in the 1930s, governments sought to stimulate economic recovery by maintaining low-interest rates. Conversely, periods of inflation often led to higher interest rates as a means to control spending and stabilize prices.
The late 20th century witnessed further advancements that revolutionized the mortgage industry. The advent of computer technology allowed lenders to automate processes and streamline loan approvals. This increased efficiency resulted in greater access to credit for borrowers while also enabling financial institutions to expand their offerings.
Interest rates continued fluctuating throughout this period due to global events such as oil crises, recessions, and political developments. However, central banks played an increasingly significant role in influencing interest rate movements through monetary policy tools. Governments aimed at striking a balance between stimulating economic growth and curbing inflationary pressures.
In recent years, we have seen historically low-interest rates following the global financial crisis of 2008-2009. Governments worldwide implemented expansionary monetary policies with reduced interest rates as a way to boost struggling economies. These measures significantly impacted mortgage lending by making borrowing more affordable for homebuyers.
Looking ahead into the future, it is challenging to predict how mortgages and interest rates will evolve over time accurately. However, one thing remains certain – mortgages will continue being an integral part of homeownership aspirations worldwide. As economies change and societies evolve further still, so too will our approaches towards lending practices adapt accordingly.
In conclusion, mortgages have come a long way since their inception thousands of years ago. From ancient civilizations seeking loans against property collateral to modern-day systems backed by government programs; they have undergone substantial transformations over time. Interest rates have been intricately tied with historical events and economic conditions, shaping the affordability and accessibility of mortgage loans. As we move forward, understanding this historical perspective helps us navigate the ever-changing landscape of homeownership with confidence.