Interest Rate Hikes and Cuts: Your Comprehensive FAQ Guide
Interest Rate Hikes and Cuts: A Comprehensive FAQ Guide
Introduction:
Central banks play a crucial role in the economy by regulating interest rates. When central banks increase or decrease interest rates, it affects various aspects of personal finance, including borrowing costs, savings returns, and investment opportunities. This comprehensive FAQ guide aims to provide clarity on interest rate hikes and cuts by central banks.
1. What are interest rate hikes and cuts?
Interest rate hikes occur when central banks raise the benchmark lending rates to control inflation or slow down economic growth. Conversely, interest rate cuts happen when central banks reduce lending rates to stimulate economic activity during periods of low growth or recession.
2. Why do central banks change interest rates?
Central banks use monetary policy tools such as interest rate adjustments to influence borrowing costs and money supply within an economy. By changing interest rates, they aim to manage inflation levels, stabilize currency values, promote employment growth, and regulate overall economic stability.
3. How do changes in interest rates impact borrowers?
When central banks hike interest rates, borrowing becomes more expensive. This means that loans for mortgages, car financing, personal loans become costlier for consumers as lenders pass on increased costs to borrowers. On the other hand, when central banks cut interest rates, borrowing becomes cheaper as lenders reduce their lending charges.
4. How do changes in interest rates affect savers?
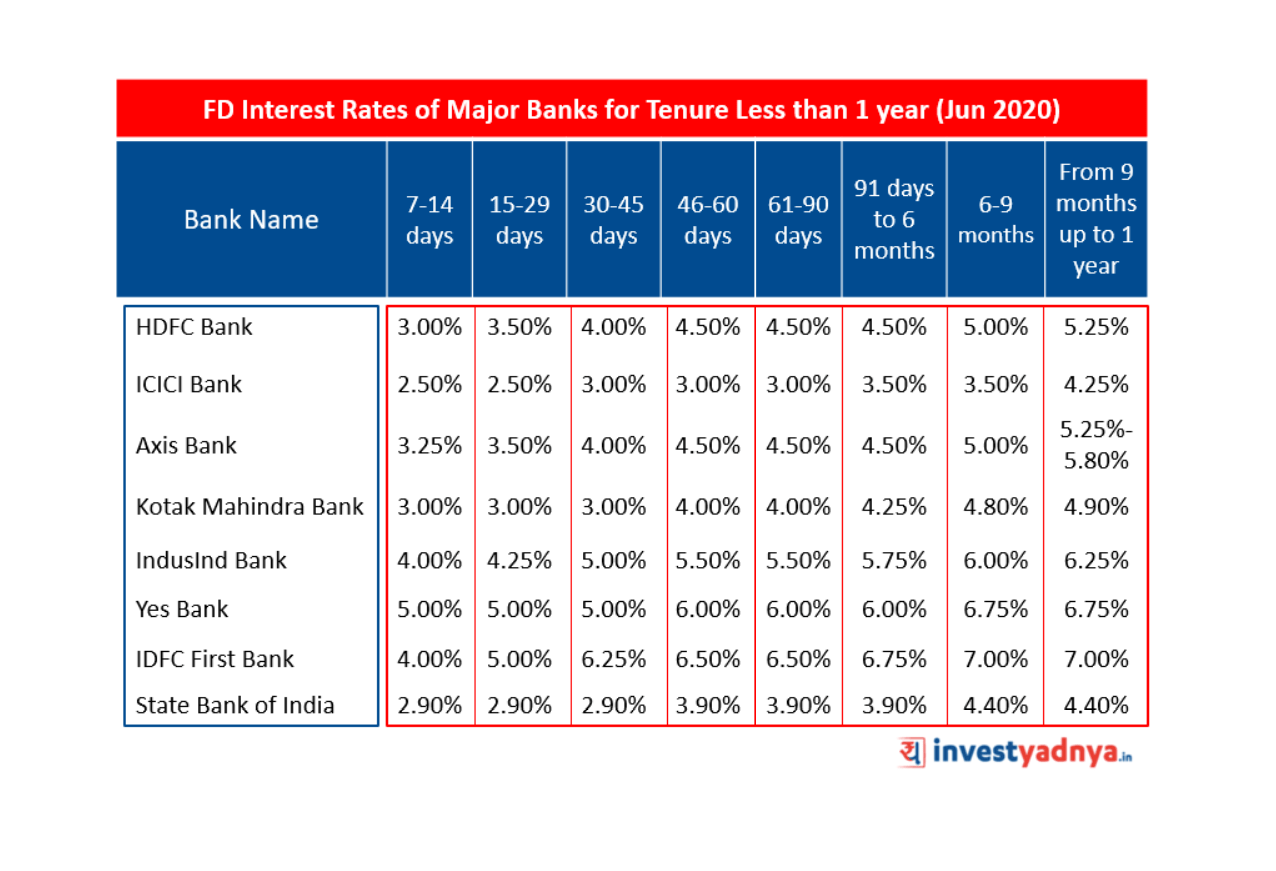
Higher interest rates can benefit savers as they receive better returns on their savings accounts or fixed deposits offered by financial institutions. However, lower interest rates mean reduced earnings on savings accounts and term deposits.
5. How do changes in interests affect investments?
Interest rate movements significantly impact different types of investments:
– Bonds: Bond prices move inversely with changes in market-interest-rates – rising yields lead to falling bond prices.
– Stocks: Changes in lending costs can influence stock market performance indirectly through effects on consumer spending patterns.
– Real estate: Higher lending costs due to increased interest rates may slow down the real estate market, leading to lower demand and potentially impacting property values.
6. How frequently do central banks change interest rates?
Central banks’ decisions on interest rate changes depend on economic conditions and objectives. They typically meet regularly, and their monetary policy committees assess economic indicators before making any adjustments. Some central banks might make frequent changes while others prefer gradual adjustments over time.
Conclusion:
Interest rate hikes and cuts by central banks have a significant impact on personal finance matters like borrowing costs, savings returns, and investment opportunities. Understanding how these changes affect different areas of personal finance can help individuals make informed financial decisions during various economic cycles. It is essential to stay updated with the latest developments in monetary policy to manage your finances effectively.