“Secure Your Future: The Ultimate Guide to Building an Emergency Fund”
Introduction:
Welcome to our comprehensive guide on emergency funds! In this article, we will delve into the importance of emergency funds, how to build one, and how it can provide financial security during unexpected situations. Whether you’re just starting your financial journey or looking for ways to improve your current situation, understanding the significance of an emergency fund is crucial.
What is an Emergency Fund?
An emergency fund is a dedicated savings account set aside for unforeseen expenses such as medical emergencies, job loss, car repairs, or home repairs. It acts as a safety net by providing immediate access to cash without relying on credit cards or loans during stressful times.
The Importance of Having an Emergency Fund:
1. Financial Security: An emergency fund creates peace of mind knowing that you have enough money to cover unexpected costs. It prevents you from falling into debt when life throws curveballs your way.
2. Job Loss and Income Disruption: Losing a job can be overwhelming both emotionally and financially. With an emergency fund in place, you can navigate through unemployment with less stress while searching for new opportunities.
3. Medical Emergencies: Health issues can arise at any time and may require costly treatments or surgeries not fully covered by insurance. An emergency fund ensures that you don’t compromise your health due to financial constraints.
4. Home Repairs: Owning a house comes with its fair share of maintenance costs. From leaky roofs to malfunctioning appliances, having funds readily available allows you to address these issues promptly without affecting your daily life.
5. Car Troubles: Unexpected car repairs are not only inconvenient but also expensive. By having an adequate emergency fund, you won’t find yourself scrambling for transportation options while waiting for necessary repairs.
How Much Should You Save?
Determining the ideal amount for your emergency fund depends on various factors such as monthly expenses, income stability, family size, and individual circumstances like healthcare needs or vehicle age/maintenance history.
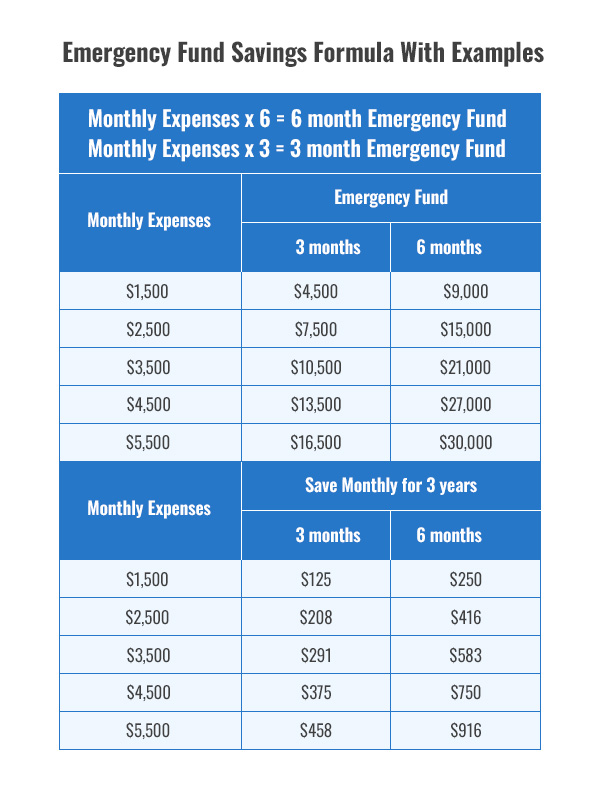
1. Basic Rule of Thumb: Financial experts often recommend saving three to six months’ worth of living expenses in your emergency fund. This range aims to cover most unforeseen circumstances and provide a sufficient buffer until you stabilize your financial situation.
2. Customize Based on Your Needs: While the general guideline is helpful, it’s essential to assess your personal circumstances as well. If you have dependents or work in an industry with limited job prospects, saving towards the higher end of the spectrum may be prudent.
3. High-Risk Professionals or Business Owners: Individuals who have jobs with irregular income streams or entrepreneurs running their own businesses might consider having a more substantial emergency fund—typically closer to 12 months’ worth of expenses—to account for potential fluctuations in earnings.
Building Your Emergency Fund:
Now that we understand why an emergency fund is crucial let’s explore practical steps to build one:
1. Set Realistic Goals: Start by determining how much money you need based on your monthly expenses and any specific risks associated with your lifestyle (e.g., health conditions, job volatility). Break this amount down into manageable milestones to make saving less overwhelming.
2. Create a Budget: Review your income and expenditure carefully. Identify areas where you can cut back on unnecessary spending and allocate those savings towards building your emergency fund.
3. Automate Savings: Make use of technology and set up automatic transfers from your primary account into a dedicated emergency fund account each time you receive a paycheck or at regular intervals (e.g., monthly). This way, saving becomes effortless and consistent.
4. Minimize Debt: Prioritize paying off high-interest debt while simultaneously contributing to your emergency savings—this will prevent interest charges from eroding progress made towards building the fund.
5. Earn Extra Income: Consider taking up side gigs or freelancing opportunities during evenings or weekends to accelerate the growth of your emergency fund further.
Where Should You Keep Your Emergency Fund?
Apart from the amount you save, where you keep your emergency fund is equally important. Here are some suitable options:
1. High-Yield Savings Account: A high-yield savings account offers a higher interest rate than traditional savings accounts, allowing your emergency fund to grow over time. These accounts usually have low minimum balance requirements and easy accessibility.
2. Money Market Accounts: Similar to high-yield savings accounts, money market accounts offer competitive interest rates while providing enhanced liquidity. They often come with check-writing abilities and debit card access for quick fund retrieval during emergencies.
3. Certificates of Deposit (CDs): If you don’t anticipate needing immediate access to your funds, CDs can be an option as they tend to offer higher interest rates than regular savings accounts or even money markets. However, be mindful of early withdrawal penalties associated with CDs if you need the cash before maturity.
Conclusion:
Building an emergency fund is a vital step towards gaining financial security and peace of mind in today’s unpredictable world. By setting realistic goals, making consistent contributions, and choosing appropriate account types for your needs, you can establish a safety net that will protect you during unexpected challenges along life’s journey. Remember, it’s never too late to start saving for emergencies – take action now and secure your financial future!