The Impact of Closing a Credit Card on Utilization Ratio: What You Need to Know
The Impact of Closing a Credit Card on Utilization Ratio
When it comes to managing your credit, understanding how different actions can affect your credit score is crucial. One such action that often raises concerns among individuals is closing a credit card account. Many people worry about the potential negative impact on their utilization ratio, which is an essential factor in determining creditworthiness. In this article, we will delve into the intricacies of the utilization ratio and explore how closing a credit card can influence it.
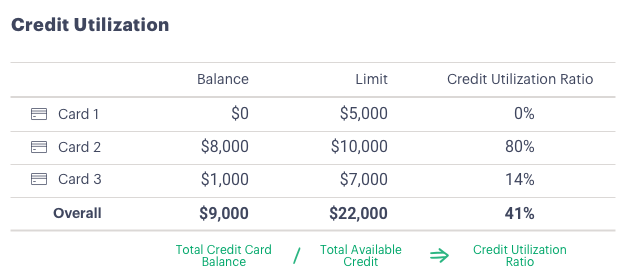
Before we dive into the details, let’s first understand what utilization ratio means and why it matters. Your utilization ratio refers to the amount of revolving credit you are currently using compared to your total available revolving credit limit. It is typically expressed as a percentage and plays a significant role in determining your overall credit score.
Lenders consider borrowers with lower utilization ratios more responsible and less risky because they demonstrate restraint in utilizing their available credits. Consequently, maintaining a low utilization ratio (generally under 30%) is advisable if you want to maintain or improve your creditworthiness.
Now that we have established the importance of keeping our utilization ratio low let us examine how closing a credit card account may impact this crucial metric:
1. Reducing Available Credit:
Closing an active credit card account reduces your total available revolving credit limit. This reduction directly affects your utilization ratio since it decreases the denominator (the total available limit). For instance, if you had three cards with $10,000 limits each ($30,000 combined), and decided to close one account, your total available limit would drop to $20,000.
Suppose you were using $3,000 across all three cards before closing one; after closure, that same balance would now represent 15% rather than 10% of your total available limit ($3,000 / $20,000 instead of $3,000 / $30,000). This increase in percentage could negatively impact your utilization ratio and potentially lower your credit score.
2. Shifting Balance Distribution:
Closing a credit card account can also disrupt the balance distribution across your remaining cards. If you had balances on multiple cards but decided to close one, the remaining cards may experience an increase in their individual utilization ratios.
For example, if you had three cards with $10,000 limits each and carried a $3,000 balance solely on one card before closing another account, your utilization ratio for that specific card would have been 30% ($3,000 / $10,000). However, after closing one account and redistributing the balance evenly across two remaining cards (i.e., $1,500 per card), both cards would now have a 15% utilization ratio ($1,500 / $10,000).
While this may seem insignificant at first glance since the overall utilization remains unchanged (30% before and after closure), certain scoring models might penalize higher individual card balances even if the total utilization is within an acceptable range. Therefore, it’s important to consider this aspect when deciding whether or not to close a credit card.
3. Impact on Credit History:
Another factor affected by closing a credit card is the length of your credit history. The age of your oldest credit account and average age of all accounts play roles in determining your credit score. Closing an old credit card can reduce both these factors.
If you decide to close an older account while keeping relatively newer ones open, it could significantly shorten your average age of accounts. This reduction may have adverse effects on your overall score as creditors typically view longer-established accounts more favorably than newer ones.
4. Potential Future Consequences:
Closing a credit card today might not only affect your current utilization ratio but also pose potential challenges down the line. For instance:
a) Loss of Credit Mix: Your mix of different types of credits (e.g., revolving vs installment loans) is considered while calculating your credit score. Closing a credit card account could reduce the diversity in your credit mix, potentially impacting your future creditworthiness.
b) Increased Credit Utilization: If you close a credit card but continue using similar or higher amounts of revolving credit on remaining cards, it will increase their individual utilization ratios. This increase can negatively impact your overall utilization and subsequently lower your credit score.
c) Impact on Available Credit: In certain situations, closing a particular card may result in losing access to valuable benefits or rewards programs associated with that specific account. Hence, before deciding to close a card, carefully evaluate its potential long-term consequences beyond just the immediate impact on your utilization ratio.
In conclusion, closing a credit card account can have several implications for your utilization ratio and overall credit score. While there might be valid reasons for wanting to close an account (such as excessive fees or poor customer service), it’s essential to weigh the potential negative impacts against these considerations.
Before making any decision regarding closure, consider alternative options such as reducing usage on the targeted card without completely shutting it down. Maintaining a good utilization ratio by responsibly managing all your accounts is key to maintaining healthy financial habits and ensuring favorable lending opportunities in the future.