Unlocking the Mystery: What Factors Influence Credit Card Limits?
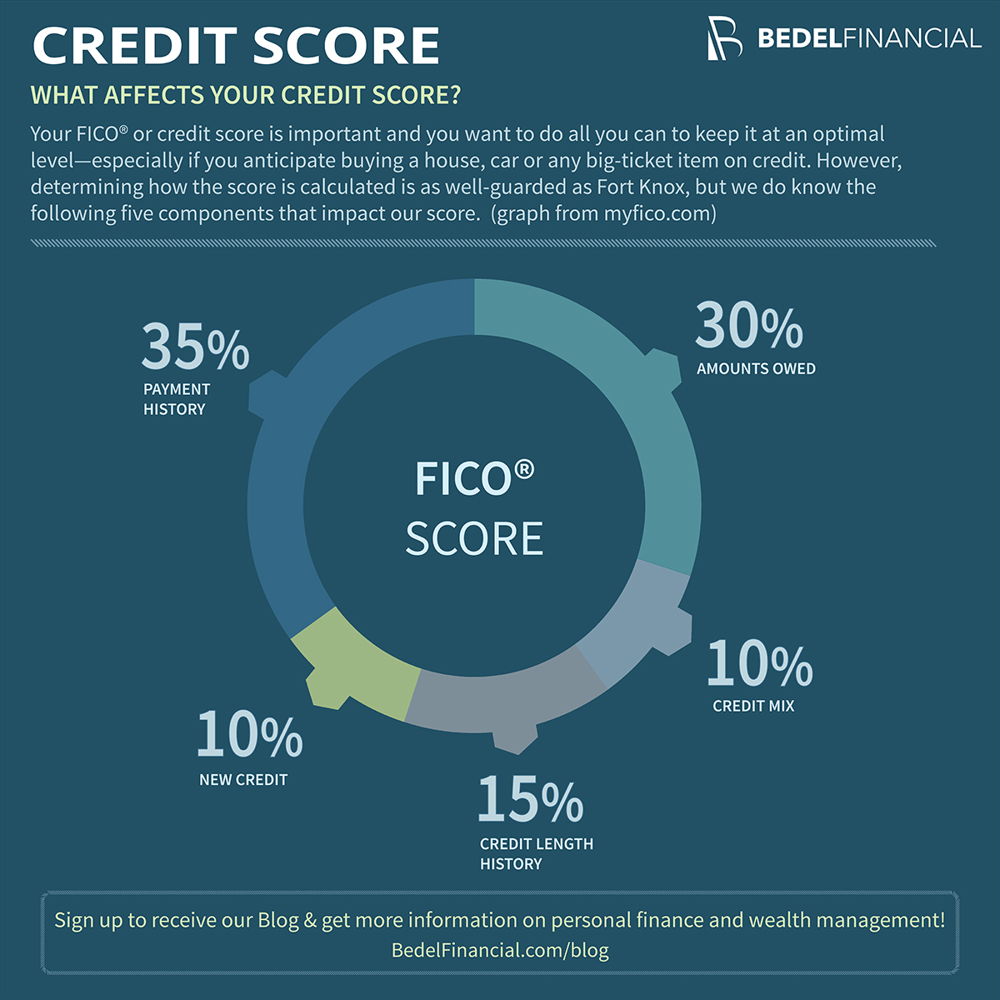
Credit card issuers’ policies on setting credit limits can vary greatly from one company to another. While there are no hard and fast rules, certain factors tend to influence their decisions.
Firstly, a primary consideration for credit card issuers is an applicant’s credit history. They will assess the individual’s credit score, payment history, and overall financial stability. Someone with a higher credit score and a demonstrated ability to manage debt responsibly is more likely to receive a higher credit limit.
Income level also plays a role in determining the credit limit. Higher income generally suggests greater repayment capacity, which makes applicants more attractive to lenders. However, many companies have minimum income requirements that must be met before granting larger limits.
Existing relationship with the issuing bank or institution can sometimes impact the decision as well. Individuals who already hold accounts with the bank or have proven loyalty may be offered higher limits as an incentive to continue using their services.
It’s important to note that some companies use internal algorithms and proprietary models when assessing applications for credit cards. These models take into account various data points such as age, employment status, and even spending habits gathered from alternative sources like social media platforms.
Lastly, regulatory guidelines play a part in determining how much risk banks are comfortable taking on when extending lines of credit. These regulations aim to prevent excessive borrowing and protect both consumers and lenders.
Ultimately, each issuer has its own specific criteria for setting credit limits based on these factors mentioned above or others they consider relevant. It is always wise for potential cardholders to research different options thoroughly before applying for new lines of credit