Unlocking Financial Potential: How Personal Loans Can Empower Your Goals
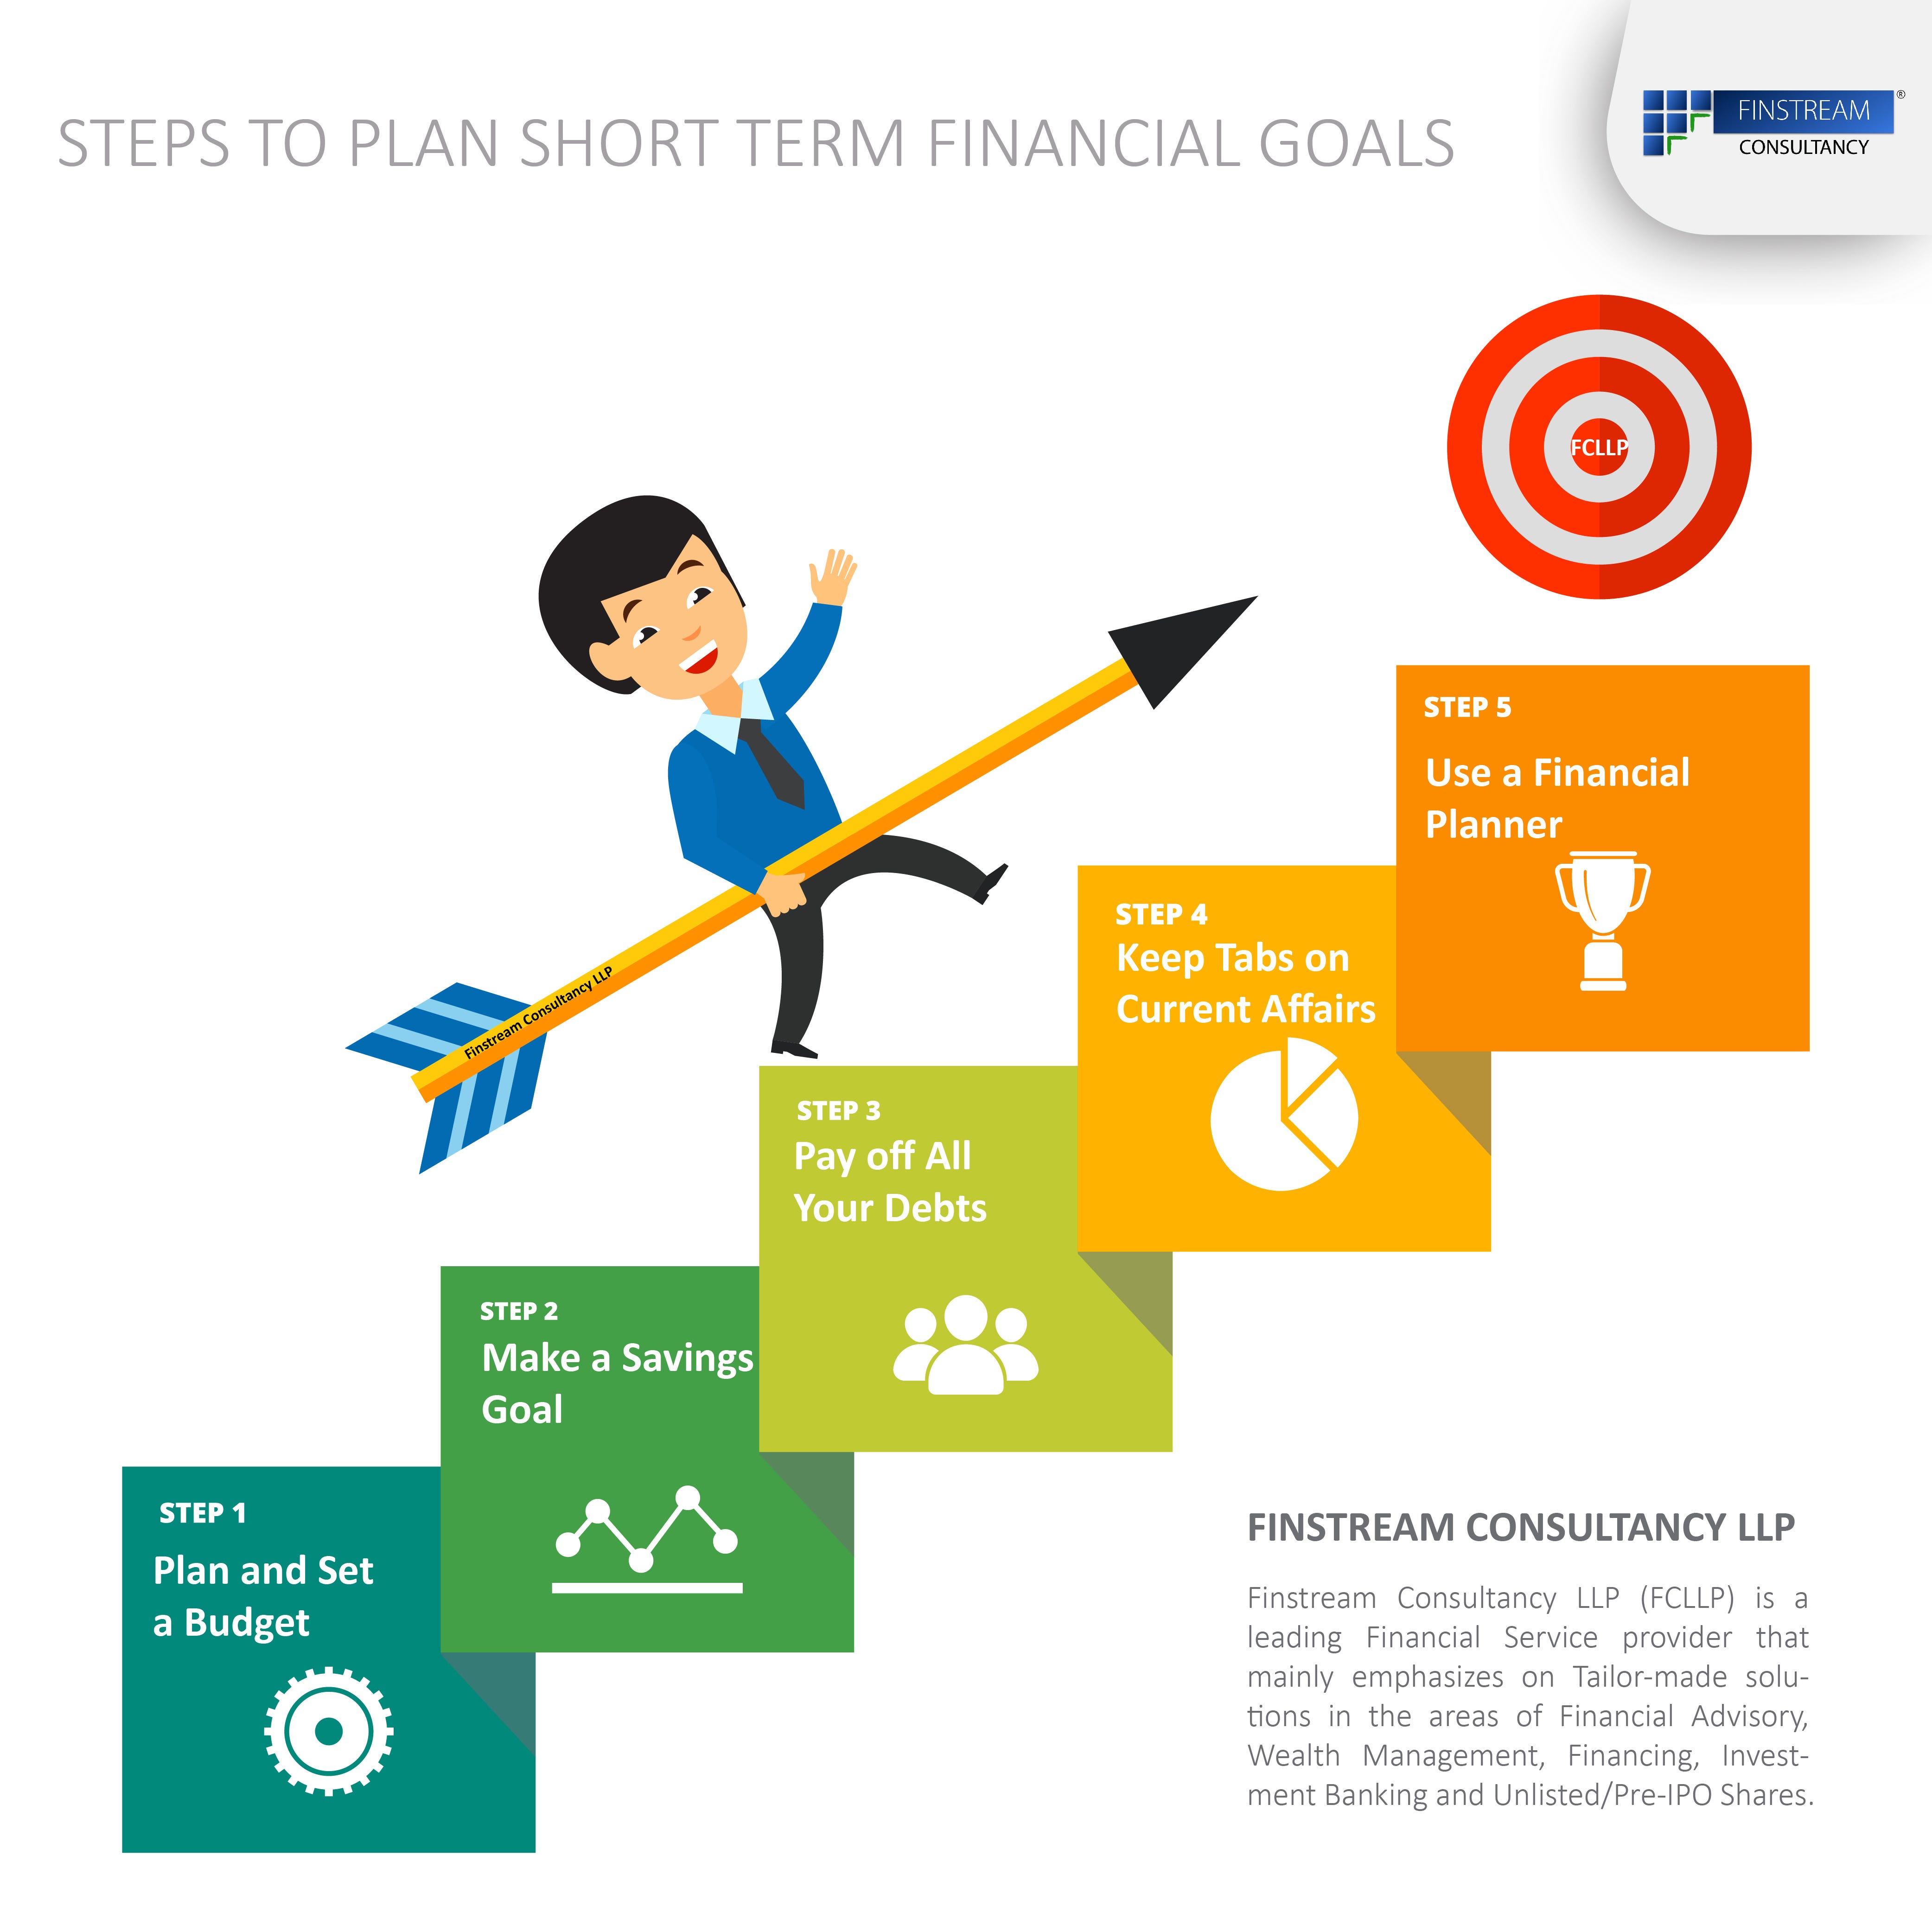
Personal loans can be a valuable financial tool for individuals looking to achieve their goals, cover unexpected expenses, or consolidate debt. While some may view personal loans as a last resort due to the associated interest rates and fees, when used wisely, they can actually provide a way to accomplish important milestones and improve your financial situation.
One of the key benefits of personal loans is their versatility. Unlike specific-purpose loans like auto loans or mortgages, personal loans can be used for a variety of purposes. Whether you need funds for home improvements, education expenses, medical bills, or even a dream vacation, a personal loan provides you with the flexibility to use the money as you see fit.
Additionally, personal loans offer predictable monthly payments over a fixed period of time. This can make budgeting easier since you know exactly how much you need to pay each month and for how long. Compared to credit cards with fluctuating interest rates and minimum payments that could keep you in debt for years, personal loans provide clarity and structure to help you manage your finances effectively.
Consolidating high-interest debt is another popular reason why people turn to personal loans. By taking out a personal loan at a lower interest rate than what they are currently paying on credit card balances or other debts, individuals can save money on interest charges and pay off their debt faster. This not only helps improve their credit score by reducing overall debt but also simplifies their repayment process by combining multiple debts into one single payment.
Moreover, applying for a personal loan is typically quick and convenient compared to other types of financing options such as mortgages or business loans which involve more complex processes and requirements. Many online lenders now offer fast approval times and funding within days, making it an appealing choice for those who need immediate access to funds without extensive paperwork or waiting periods.
When considering whether to take out a personal loan, there are several factors that individuals should keep in mind:
1. **Assess Your Financial Situation:** Before applying for a personal loan, evaluate your current income sources, expenses, existing debts, credit score, and financial goals. Understanding your financial position will help determine whether taking on additional debt through a loan is the right decision at this time.
2. **Compare Lenders:** Research different lenders including banks, credit unions,
online lenders,and peer-to-peer platforms to find the best terms that suit your needs.
Compare interest rates,payment terms,and fees before making
any decisions about where
to borrow from.
3. **Check Your Credit Score:** A higher credit score often leads
to better loan offers with lower interest rates.
If your credit score is less than ideal,
work on improving it before applying
for a personal loan to get access
to more favorable terms.
4 .**Understand the Terms: Read the fine print carefully**
and make sure you understand all aspects
of the agreement including
interest rates,costs,fixed vs variable rates,
prepayment penalties,and any other fees involved.
Ask questions if anything seems unclear
or seek advice from a financial advisor.
In conclusion,personalloanscanbeapowerfultoolforenhancingyourfinancesandachievingyourgoalswhenusedresponsibly.Byunderstandingtheprosandcons,makinganinformeddecisionaboutborrowing,andmanagingrepaymentswisely,youcancapitalizeonthebenefitsofpersonalloanswhileavoidingpotentialpitfalls.Thinkcarefullyaboutyourspecificfinancialneedsandconsiderhowapersonalloancouldhelpyoureachyourobjectives.Whetherit’sconsolidatingdebt,makingahomeimprovementinvestment,fundinganeducationortrainingprogram,startingsmallbusinessventureorpursuingadreamproject,personalloanscanbeyourallyinmakingithappen.Whenusedstrategicallyandwithcaution,personalloanscanempoweryoutotakecontrolofyourfinancesandleadyoutowardsagreaterleveloffinancialstabilityandachievement