Simplify Your Finances with Loan Consolidation: A Guide to Managing Multiple Loans
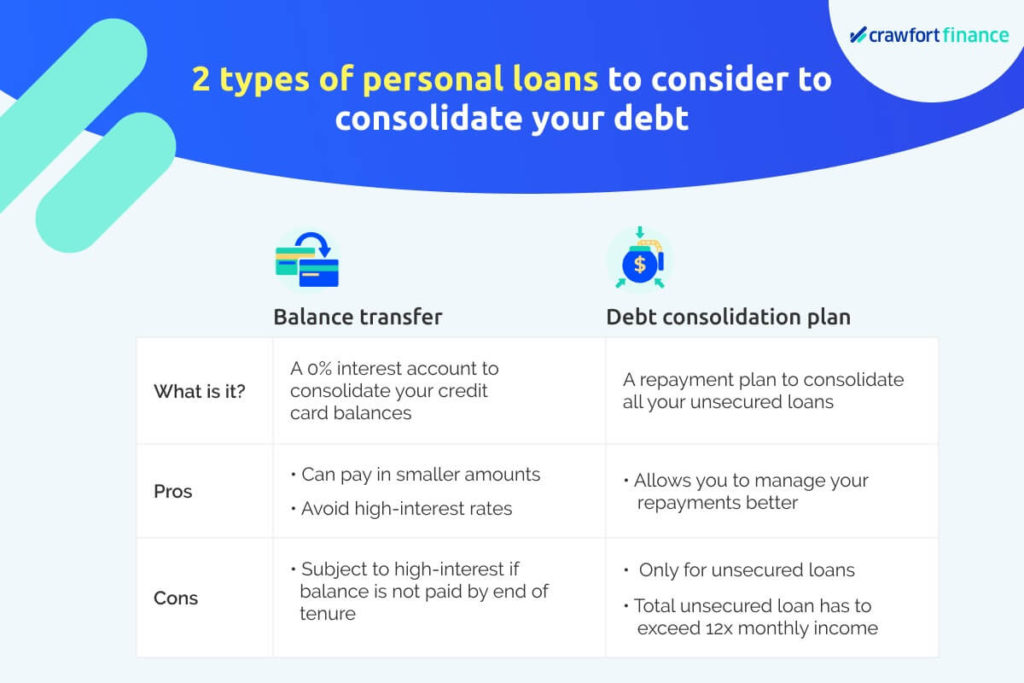
When it comes to managing multiple loans, loan consolidation can be a helpful solution to simplify your finances and potentially save money in the long run. Loan consolidation involves combining several debts into one single loan with a fixed interest rate, making it easier to keep track of payments and potentially lowering your overall monthly payment amount.
There are various options available for consolidating loans, depending on the type of debt you have and your financial situation. One common method is through a personal loan, where you borrow a lump sum from a lender to pay off all your existing debts. Personal loans typically have fixed interest rates and terms, which can provide predictability in your repayment schedule.
Another popular option for loan consolidation is through balance transfer credit cards. With this method, you transfer balances from high-interest credit cards onto a new card with an introductory 0% APR period. By consolidating your credit card debt onto one card with lower or no interest for a limited time, you may be able to pay off the balance more quickly without accruing additional interest charges.
For those with federal student loans, consolidating through a Direct Consolidation Loan can be beneficial. This type of consolidation combines multiple federal student loans into one new loan with an average interest rate based on the original loans’ rates. While this option simplifies repayment by having just one monthly payment, it’s essential to note that the new interest rate will be rounded up slightly.
If you have private student loans or want more flexible repayment options than what federal consolidation offers, refinancing through a private lender could be worth considering. Refinancing allows borrowers to consolidate both federal and private student loans into one new loan with potentially lower interest rates or more favorable terms based on their creditworthiness.
Homeowners may also explore home equity loans or lines of credit as a form of loan consolidation. By leveraging the equity in their home, borrowers can secure funds at potentially lower interest rates compared to other types of unsecured debt consolidation options like personal loans or credit cards.
Before choosing any loan consolidation option, it’s crucial to assess your current financial situation carefully. Consider factors such as total outstanding debt amounts, individual interest rates on each account being consolidated, fees associated with the chosen method of consolidation, and any potential impact on long-term financial goals before making a decision.
While loan consolidation can streamline your repayment process and possibly save money over time by reducing overall interest costs or monthly payments; it’s important not only to focus on short-term benefits but also consider the potential drawbacks such as extending the repayment term resulting in paying more over time if not managed carefully.
It’s advisable always do thorough research before committing to any form of loan consolidation so that you fully understand how each option works within your unique financial circumstances.