Mastering the Art of Amortization: Key Concepts for Financial Success
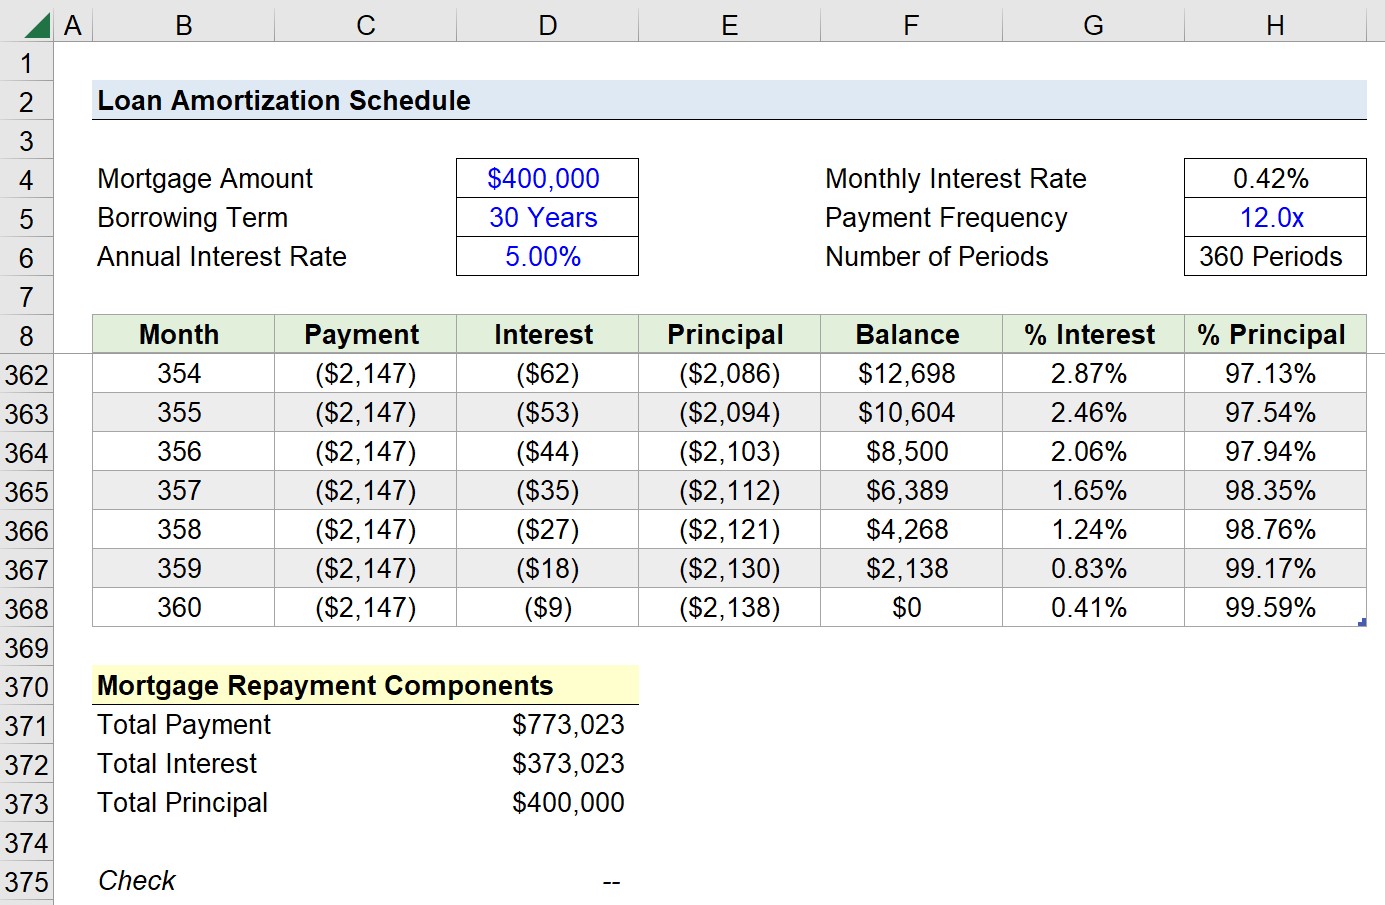
Amortization is a crucial concept in the world of finance and accounting, playing a significant role in various aspects of borrowing, investing, and business operations. Understanding different types of amortization schedules and methods can help individuals and businesses make informed financial decisions.
Accelerated amortization involves paying off a loan more quickly than the standard schedule requires. This can result in substantial interest savings over the life of the loan. By making extra payments or increasing the regular payment amount, borrowers can reduce their principal balance faster, leading to earlier debt payoff.
On the other hand, negative amortization occurs when the monthly payments on a loan are insufficient to cover both the principal and interest due. As a result, the unpaid interest gets added to the loan balance, causing it to increase over time rather than decrease. This type of arrangement is commonly seen in adjustable-rate mortgages with payment caps.
Amortization schedules outline how loans are repaid over time by breaking down each payment into portions that go towards reducing principal and paying interest. Different loan types such as fixed-rate mortgages, variable-rate mortgages, car loans, student loans, personal loans, and business loans have specific amortization schedules tailored to their terms and conditions.
Some loans come with balloon payments where a large lump sum is due at the end of the term. Balloon payment loans often have lower monthly payments initially but require borrowers to either pay off or refinance the remaining balance when the balloon payment comes due.
Bi-weekly mortgage amortization involves making half of your monthly mortgage payment every two weeks instead of once per month. This results in 26 half-payments each year (equivalent to 13 full payments), helping borrowers save on interest costs by accelerating debt repayment.
Car loans follow an amortization schedule similar to other installment loans but typically have shorter terms ranging from three to seven years based on factors like vehicle price and borrower creditworthiness.
Student loans also adhere to specific amortization schedules designed for educational financing needs with options for income-driven repayment plans that adjust based on income levels after graduation.
Personal loans may have fixed or variable rates with corresponding amortization schedules outlining how payments are applied towards principal reduction and interest accrual over time.
Intangible assets like patents or trademarks undergo amortization based on their useful life expectancy rather than physical depreciation like tangible assets such as equipment or buildings.
Tax implications play a vital role in determining deductible expenses related to business asset acquisition through depreciation or goodwill write-offs under specific guidelines outlined by tax authorities within different jurisdictions globally.
Straight-line versus accelerated methods compare evenly distributed depreciation expense against front-loaded values aligning with asset usage patterns affecting taxable income calculations annually.
Prepaid expenses impact future period financial statements through gradual recognition via systematic allocation across successive periods reflecting benefits derived from advanced expenditures incurred prior.
Leasehold improvements undergo depreciative treatment over lease duration mirroring cost recovery associated with tenant-specific enhancements made toward leased property enhancing overall rental value propositioned.
Software development costs allocate capital outlays systematically matching revenue recognition timelines following completion benchmark milestones met during software product lifecycle management phases implemented.
Goodwill impairment testing assesses intangible asset valuation adjustments periodically required contingent upon market conditions influencing fair value determinations necessitating write-downs impacting company financial health assessments evaluated.
Mortgage points amass upfront fees paid securing favorable lending terms negotiated directly correlating reduced long-term borrowing costs facilitating buyer affordability enhancement strategies implemented earlier post-purchase closing transactions finalized.
Closing costs allocated proportionally across specified timeframe intervals spreading transactional expenses incurred encompassing origination services rendered coordinating real estate purchase agreements executed efficiently facilitated.
Partially-amortized Loans structure partial repayments mitigating total outstanding balances deferred beyond agreed-upon maturity dates stipulated obligating borrowers fulfilling residual amounts owed promptly
Reverse Mortgage Amortizations accommodate senior citizens requiring supplemental income streams leveraging home equity conversions deferring repayment obligations until subsequent events transpire warranting accrued balances settled effectively
In conclusion,
the intricate nature surrounding various forms of ammortizations encapsulates multifaceted interpretations guiding prudent fiscal decisions undertaken thoughtfully deliberated ensuring optimal resource utilization achieving strategic objectives envisioned comprehensively realized proficiently operationalized seamlessly incorporating sound principles governing organizational wealth management methodologies employed