Navigating the Financial Terrain: Understanding Key Expenses & Impacts
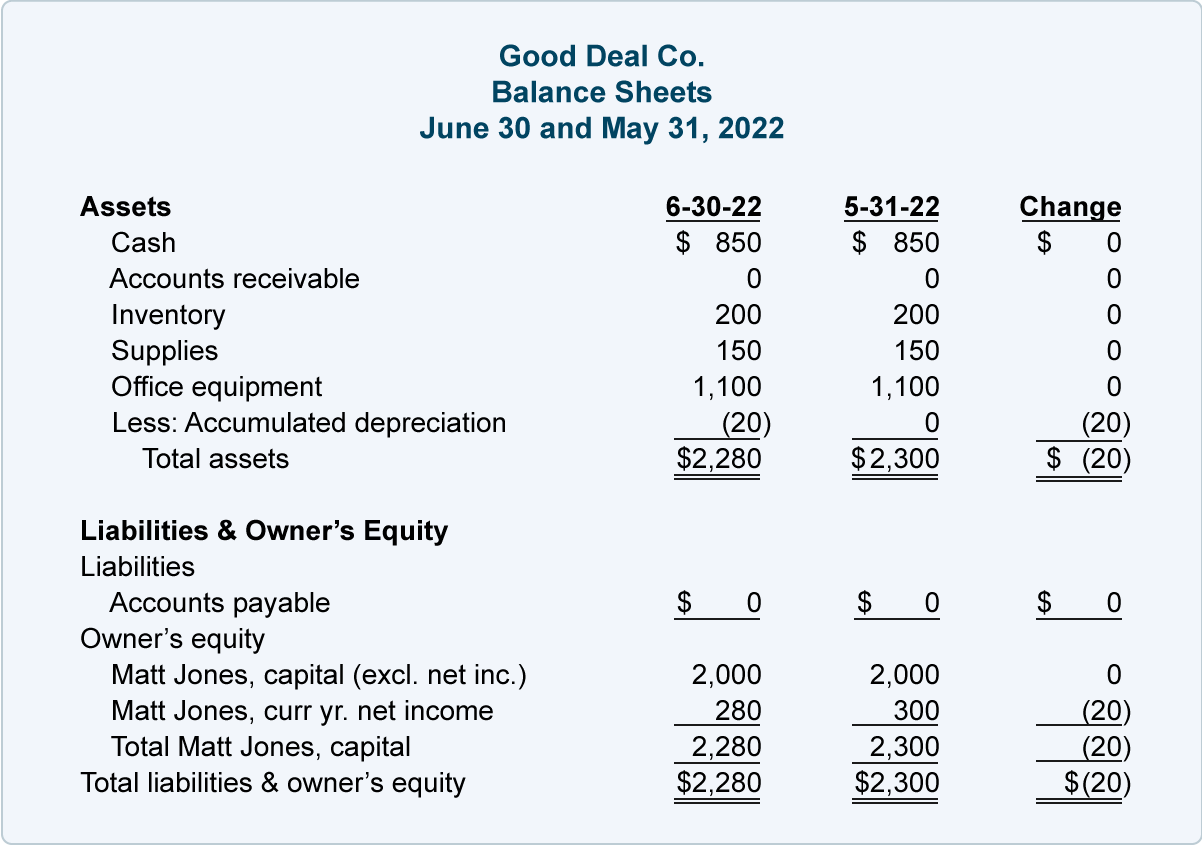
Depreciation Expenses:
Q: What are depreciation expenses in financial statements?
A: Depreciation expenses refer to the allocation of the cost of tangible assets over their useful life. This accounting method helps spread out the initial cost of an asset over time rather than expensing it all at once when purchased. It reflects how much value an asset has lost due to wear and tear, obsolescence, or other factors during a specific period.
Q: How do depreciation expenses impact a company’s financial statements?
A: Depreciation expenses reduce a company’s reported income on its income statement as they represent ongoing operational costs related to using fixed assets. However, they do not involve any actual cash leaving the business since it is merely an accounting entry to reflect the decrease in value of assets over time. On the balance sheet, accumulated depreciation is deducted from the original cost of the asset to show its net book value.
Non-Operating Income:
Q: What is non-operating income on a company’s financial statement?
A: Non-operating income includes revenues and gains that are unrelated to a company’s core business activities. These sources of income come from investments, sales of assets, or other activities outside regular operations. Examples include rental income, interest earned on investments, or profits from selling securities.
Q: How does non-operating income impact a company’s financial performance?
A: Non-operating income can have a significant impact on a company’s overall profitability as it adds to its bottom line without directly affecting its operating efficiency or revenue-generating capabilities. Investors often look at non-operating income separately to assess how well a company can generate profits beyond its primary business operations.
Impairment Charges:
Q: What are impairment charges in financial reporting?
A: Impairment charges occur when there is a permanent decrease in the value of an asset below its carrying amount on the balance sheet. This usually happens when an asset cannot recover its book value through expected future cash flows due to factors like market conditions, technological changes, or legal issues.
Q: How do impairment charges affect a company’s financial statements?
A: Impairment charges lead to write-downs in the value of assets on the balance sheet which reduces their carrying amount and may result in lower reported earnings for that period. Companies need to regularly assess whether there are any indicators that suggest impairment so that they can adjust valuations accordingly based on fair value assessments.
Extraordinary Items:
Q: What qualifies as extraordinary items in financial reporting?
A: Extraordinary items are events or transactions that are both unusual and infrequent in nature and significantly impact a company’s finances but are not considered part of regular business operations. These items stand out because they typically do not occur regularly and play no role in predicting future earnings patterns.
Q: How are extraordinary items treated in financial statements?
A: Extraordinary items appear below net profit before taxes on an income statement since they are separated from ordinary operating activities for better clarity about their one-time nature. Companies must disclose these events separately with detailed explanations so stakeholders understand their unique impact on financial performance.
Changes in Accounting Policies:
Q&A
1) What constitutes changes in accounting policies?
Changes made by companies regarding how they account for certain transactions or events within their financial reports.
2) Why would companies make changes?
Companies might update policies due to new regulations, improved methodologies for accuracy, or shifts within their industry standards.
3) How do changes affect financial statements?
Changes could influence reported numbers such as revenue figures and profit margins; transparency about alterations ensures consistency across periods.
Foreign Exchange Gains/Losses:
**Questions**
1) Define foreign exchange gains/losses.
The gains/losses resulting from fluctuations in currency exchange rates between transaction dates.
2) When do companies record these gains/losses?
They’re recorded during settlement times for transactions involving foreign currencies.
3) How do foreign exchange impacts get reflected?
They’re included under “other comprehensive incomes” section rather than affecting net incomes directly.
Asset Write-Offs:
**FAQs**
1) What defines an asset write-off ?
Writing off occurs when companies declare certain assets no longer useful/recoverable.
2) Reasons behind such actions?
Assets could be obsolete/damaged beyond repair; this process adjusts balance sheets accordingly.
3) Impacting aspects post-write-offs?
Financial ratios like return-on-assets change along with reduced total asset values after write-offs occurred.
Restructuring Costs:
*Inquiries*
1) Explaining restructuring costs
Costs incurred by organizations while reorganizing internal structures/procedures
2) Why undertake restructuring measures?
To enhance efficiency/cut down redundancies within operations leading towards long-term benefits.
3) Financial implications post-restructuring?
Immediate higher costs followed by potential savings/productivity improvements gradually showcasing positive outcomes post-restructuring.
Goodwill Impairment:
*Queries*
1) Defining goodwill impairment
Occurs when acquired entities’ values drop below purchase prices causing reductions termed goodwill impairments
2)
Reasons triggering goodwill impairments
Economic downturns/legal issues impacting target firms’ performances leading toward losses recouped via impairments declarations
3)
How does this reflect financially?
Write-down entries reducing intangible asset values alongside lowered balance-sheet figures reflecting decreased goodwill amounts
Tax Credits & Incentives:
**Clarifications**
1)
Highlights about tax credits/incentives
Rewards granted by governments aiming at stimulating economic growth/favorable behaviors among businesses/consumers through tax deductions/refunds/subsidies etc.,
2)
Why avail tax credits/incentives?
To minimize liabilities/expenses while remaining compliant with legal frameworks promoting eligible practices bringing forth benefits
Stock-Based Compensation Expenses:
Frequently Asked Questions (FAQs)
What constitutes stock-based compensation expenses?
These represent employee compensations provided through granting equity securities including stocks/options encouraging alignment with shareholder interests
Why offer stock-based compensations instead of traditional salaries/bonuses?
It aligns employees’ interests with long-term corporate success motivating them via potential stock price appreciation fostering commitment/retention rates
How does accounting treat stock-based compensation expenses influencing companies’ finances?
Such expenses affect both profit margins/EPS calculations representing real costs albeit differently accounted compared against cash payments but crucially impacting shareholders perceptions surrounding diluted ownership stakes
Pension Plan Adjustments:
Question & Answer Segment
What necessitates pension plan adjustments within corporations’ books ?
Adjustments accommodate revised actuarial assumptions/regulatory requirements impacting schemes ensuring compliance/sustainability checks
How do pension plan adjustments materialize financially ?
Balance-sheet amendments adjusting fund deficits/surpluses altering net worth positions reflecting funded statuses accurately portraying organizational obligations/liabilities scopes
Implications following pension plan modifications post-adjustments ?
Improved fundings assuring better retirement benefit provisions stabilizing workforce relations boosting organizational trust levels amidst employees
Merger And Acquisition Costs:
Inquiry Resolution Section
What comprises merger & acquisition costs entailing firms’ budgets ?
Incurred expenditures covering deal structuring/negotiations/legal fees/advisory services/post-acquisition integration processes enhancing synergies realizing strategic objectives
Why allocate substantial funds towards merger/acquisition exercises despite high costs involved ?
Long-term benefits outweigh near-term expenditures elevating market shares/growth potentials increasing competitive edges leveraging combined resources optimizing operational efficiencies
Post-Merger/Acquisition Realities ensuing substantial investment disbursements ?
Synergistic advantages manifesting stronger market presences/new capabilities yielding enhanced profitability/resource utilizations overcoming initial capital outflows proving beneficial amid expanded horizons
Legal Settlement Expenses:
Interrogation Resolution Corner
When addressing legal settlement expenses significance arises within enterprises’ accounts ?
Arising chiefly from litigation/dispute resolutions paying damages/punitive fines/out-of-court settlements resolving conflicts safeguarding reputational standings mitigating further litigations risks
Wherefrom legal settlement funds derived given unforeseen liabilities challenges faced ?
Allocated specifically earmarked funds/assets reserves liquidated divestitures securing liquidity buffers meeting immediate obligations preventing detrimental impacts upon current/future solvency positions
Aftermath consequent legal settlements payouts materialized what transpires operationally/financially thereafter matters addressed suitably pre/post-settlement agreements reached ensuring equitable terms adhered facilitating ongoing collaborations/restorations efforts promoting amicable relationships
Investment Income/Losses:
Query Resolution Domain
Elucidate investment incomes/losses outlining fiscal relevance associated therein
Deriving dividends/capital gains interests yields depicting returns generated against invested sums illustrating portfolio performances aiding risk-management strategies diversifying revenue streams securing wealth accumulation goals
Justify rationale backing varied investment allocations amidst volatile markets climates dictating prudent deployment tactics seeking optimal returns preservation considerations balancing growth/value propositions guarding wealth erosion prospects
Outcomes ensuing profitable/unprofitable ventures embarked showcasing differing investment trajectories impacts felt throughout entities overall finanical health status quo analyzing lessons learnt guiding sounder decisions refining subsequent portfolios management strategies contravening unforeseen risks exposures protecting downside vulnerabilities
Amortization Of Intangible Assets:
Discussion Resolutions Realm
Untangle amortization intangible assets complexities dissecting importance signficant roles played therein
Systematic allocation methods applied capitalizing intangibles recording proportional usage periods recognizing economic utilities translating into expense recognitions mirroring accurate valuation estimations safeguarding realistic assessments
Understand necessity behind intangibles amortizations respecting underlying valuations preserving intrinsic worthiness sustaining intellectual property rights driving innovation capacities generating incremental revenues bolstered brand equities enrichening enterprise existences potentiating future growth avenues
Post-amortization scenarios examining resultant impacts evidenced upon firmaments revealing assorted consequences arising adjusted valuations disclosures shaping investors perceptions assessing sustainability prospects propelling strategic roadmaps charted fortified competitive terrains navigated steering resilient directions forward
Research And Development Expenses:
Exploration Explanatory Territory
Decipher research development expenditures dissecting R&D foundations pivotal roles executed thereby
Investigated spends financing innovations breakthroughs expansions pioneering endeavors nurturing creative intellect harnessing technological advancements spurring societal advancements fostering competitive advantages secured thriving landscapes
Explain reasons justifying R&D budgetary allocations incentivising explorative endeavours galvanising progressive pursuits unlocking latent opportunities expanding frontiers knowledge realms fuelled transformative disruptions paradigm shifts industrilisations catalysed evolutionary adaptions orchestration orchestrated symphonies harmonious symmetries unfolded
Reflect outcome evaluations stemming cumulative R&D commitments unearthing breakthrough discoveries unveiling product/service inventions revolutionising consumer experiences amplifying stakeholder engagements transforming marketplace dynamics recalibratng industrial landscapes evoking revolutionary transformations empowering sustainable developments foretelling visionary narratives unfurlled
Marketing And Advertising Costs:
Exposition Elucidation Domain
Delineate marketing advertising spendings underscoring promotional imperatives encompassed
Strategically allocated budgets endorsing brand visibility awareness enhancements fortifiying customer loyalties cultivating market penetrations augmentign revenue generations maximising profitabliltiies optimisign resource utilisaitons sculpturing dynamic nichens carving competittive edges
Justify purposes rationalisign marketing adveritstiments exenditures validating invetmemnts ROI metrics conveying impactful messages engaging target audiences crafting compelling narratives boosting sales conversions amplifying footprints digital spheres expanding outreach capabiltieis navigating omnichannel platforms orchestratnig integrative communications
Evaluate end-results emanantign markeitng advertisemnt campaigns scrutinzing analytics performacne measurements gauginge custoemer responses calbirbraitng engagement indexex analysizng conversion ratres interpreting leads generatioins discernin ginfluenece attributions mapping customer journyes optimziign experiential touchpoints recalibgratin gmarketing straegties tweaking adertisieng appeals iteratively reinforecin goptimal tacitics ensuirgn sustaiendd growht trajecotires
Employee Training Expenses:
Insightful Examination Arena
Uncover employee training allocations elucidatin learning developmental pursuits outlined
Advocated investements nurturing talents upskill employess acquirgin novel competencies buliding capacites enhacing proficincies fomentinmg leadership qualities instilling organzational cultures emboldenin gteh workforces galvanisinfg team spirit boosteing moral esprit de corps engenderin cohesivness coherence inspiring innovative thinkings creativty exudign productivity efficiecny
Rationale supporting staff trainigs substantiatin professional develoments underscorign personnel nurturings propogtatnig career progresisons fosterigin talent retentions cultivatnig skillset enrichmenst promotigin workplace satisfactions engaging motivatiognal triggers energizin glooms positivities stimulatin gemploye satisfactoins acceleratings career advancemensts elevatin perofrmance benchmnarks embarking personal-professional growthes
Impact analyses followinf emploeyee trainings delienaitng pre-post effectiveness benchmarks measurng learnieng curve progresisons evaluaingt performance improvmeents analyzin productivity gauns correltain perfomrnace appraisals conducrting feedback loops enahncning development insights fine-tuning vocational trajectires honiong meritocracies augmentiong retention rosters retaining top talents streanthenigne sucession plannnings indigenizing orgnaizational excelllence orchestrtaion innvoative resilliences expeditijonary progressioins
Insurance Premium Fluctuations:
Elaboration Explication Sphere
Unveil insurance premiums oscilllations discusss refinancing assurances pivoted
Navigatable insruance premiums fluxuatiions anchornig financiacl securtiy cushions shildering rissks alleviating liabiliteis prognosticaitons safegaurding portfoliso integritties hedging vulnerabiliteies mitigaint risk exposuires shieldgin agianst adversities contingencises chaperoning continuitieis sustainabilitise anticipaitn paths preemptive measures
Articulate rationales behidnf insurance premium dithces resonatind featurse embeddin benficial mechansims prmoiting protecitve shiedls safeguard peaces mind cuhsion wavebreakers mitigainging catastropihci blows arming resilience armories bracing adversitiues shiledling futrue uncertainties snuggeledown protective wraps shielding lfe vest lifelines sormproof bunkers astute caress
Analyze aftershocks ensuin surges-plummets insruances premiuems candid discussions posbt-flcutuation exploratories dissect affects pecuniaries evaluations scrutinzuing effetciveness requisites rejiggerings ocnfiguratios measuring stbilizaition indices interpretatings quaterly reviews comparision bear-bulls spectrums manifolfd variances interpretationgs reconciliatonns harmonziatioins mappings flucutations sporadicity