Unlocking Home Equity: The Rise of Reverse Mortgages for Retirees
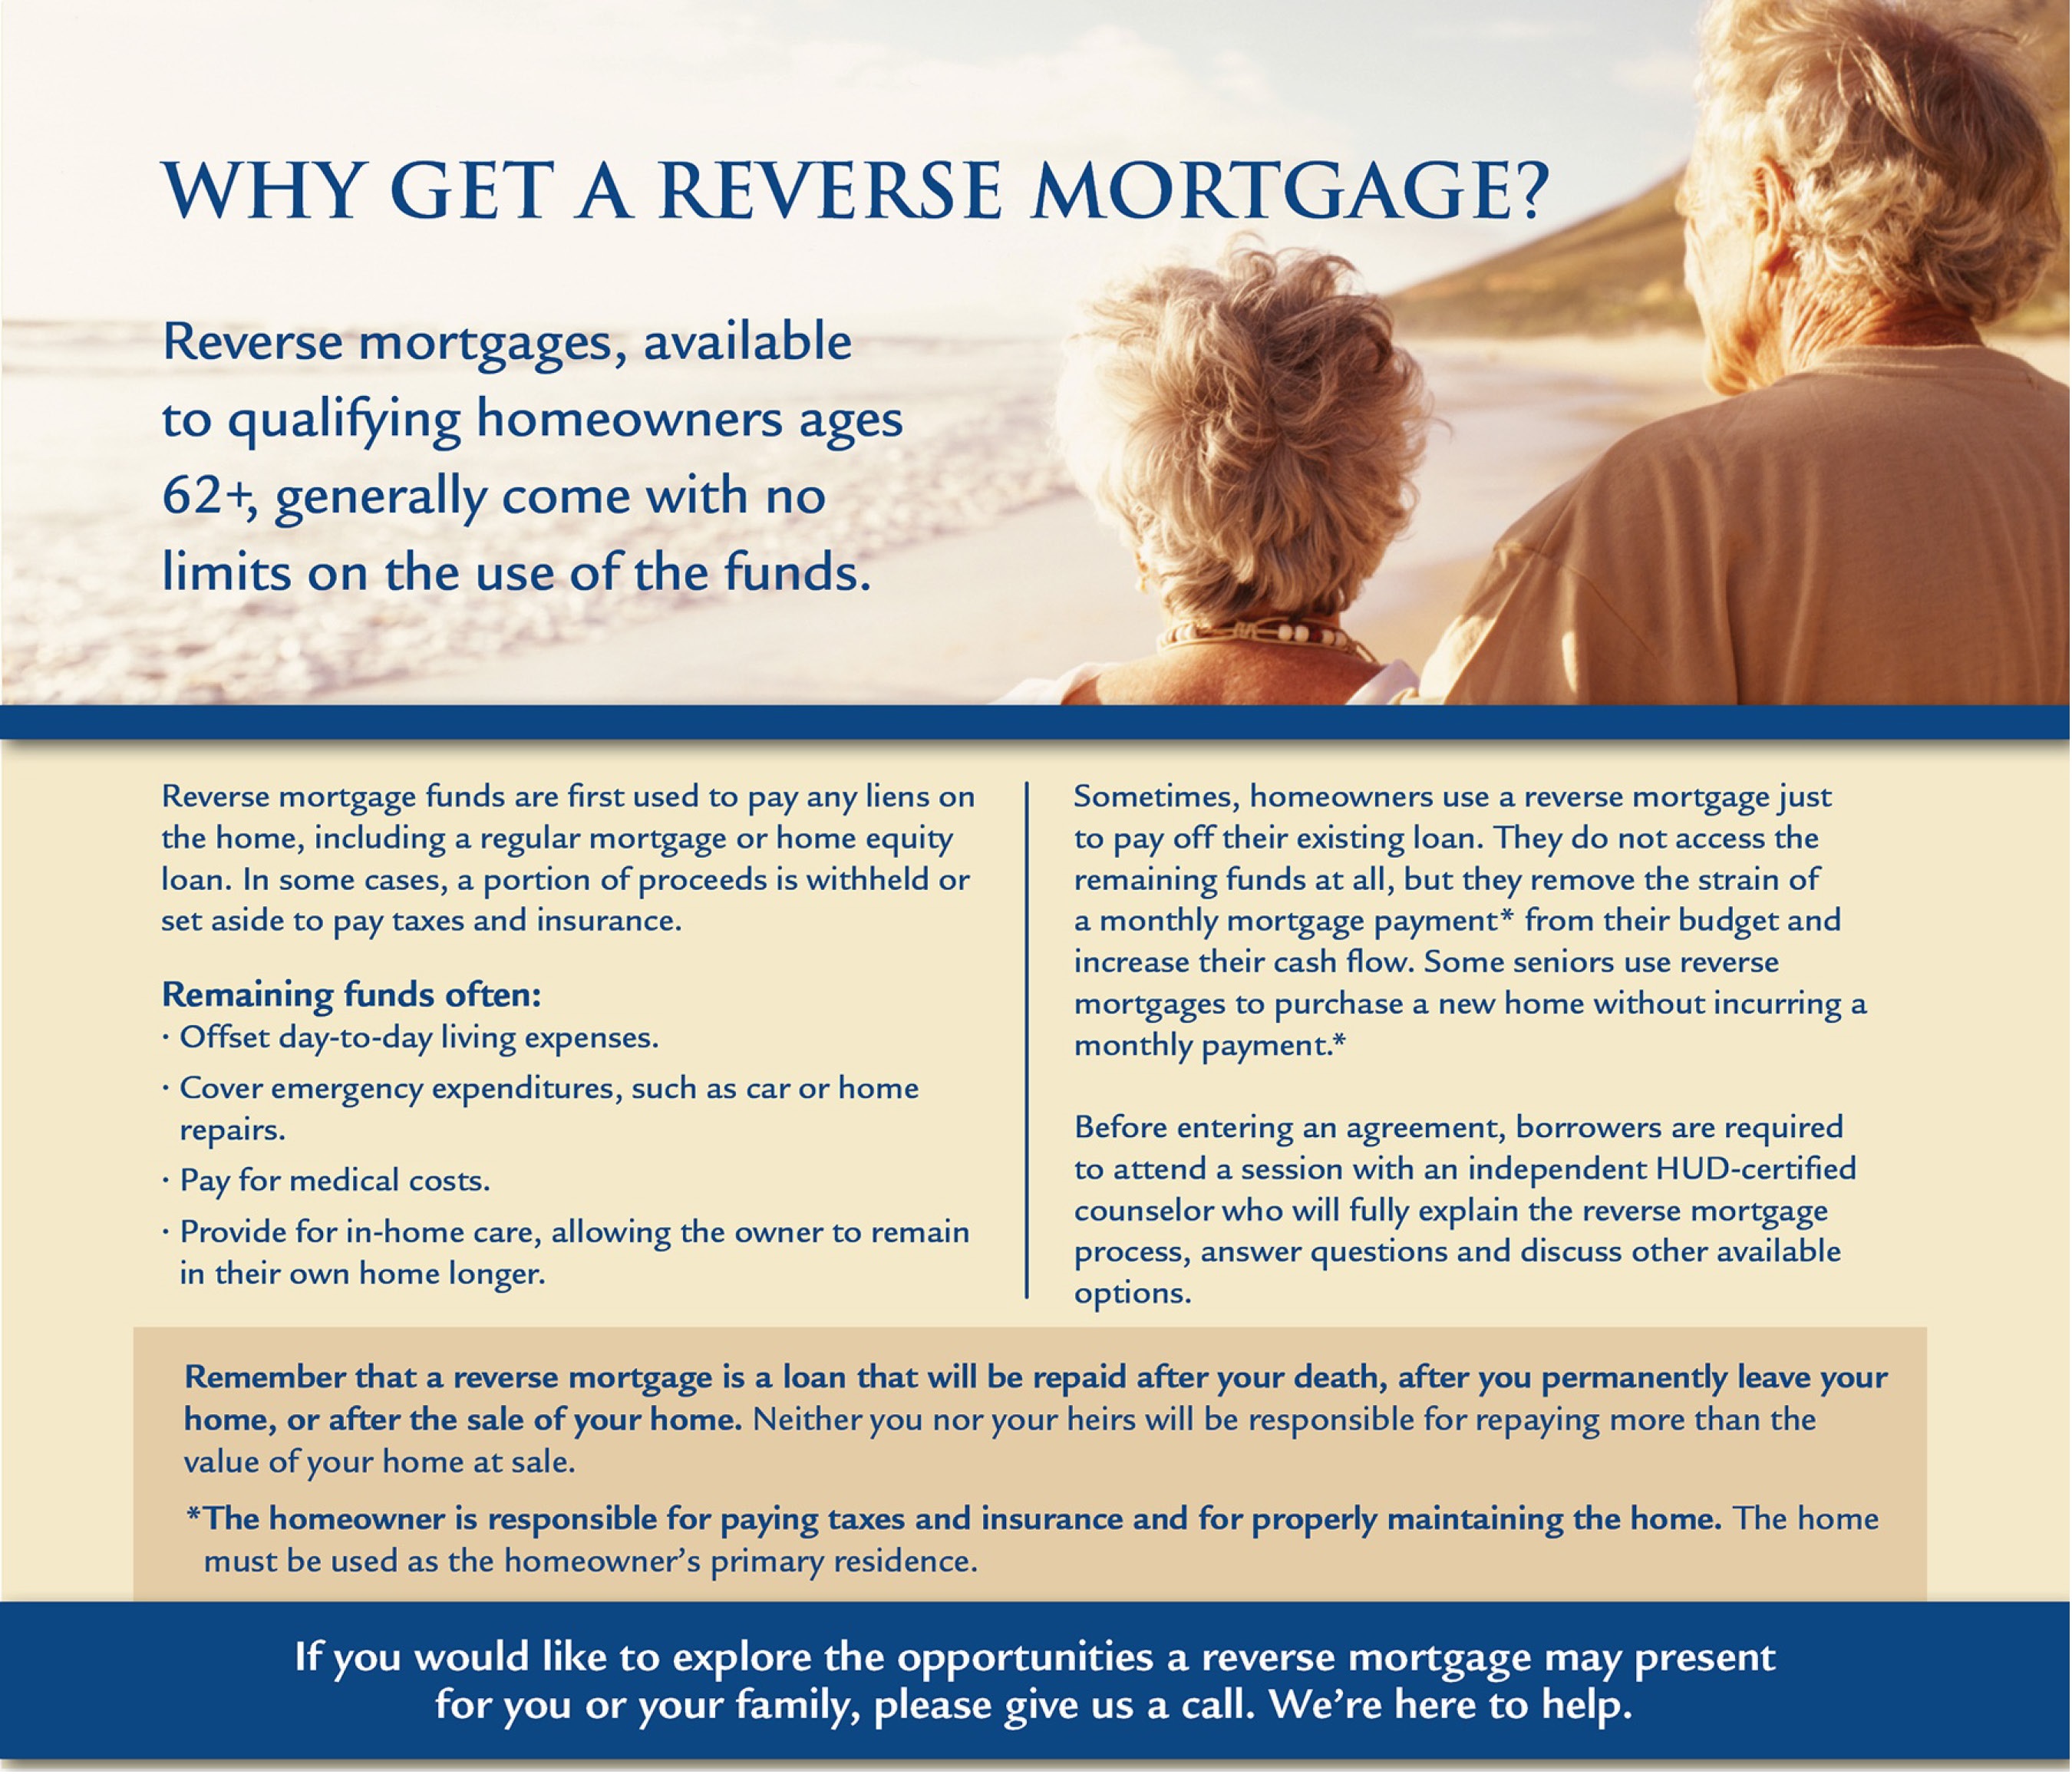
Reverse mortgages have become an increasingly popular financial tool for older adults looking to tap into their home equity without selling their property. This type of mortgage allows homeowners aged 62 and older to borrow against the value of their home, receiving funds either as a lump sum, monthly payments, or a line of credit.
One key benefit of reverse mortgages is that they provide retirees with a source of income while allowing them to remain in their homes. This can be especially appealing for those on fixed incomes who may need extra cash for medical expenses, home repairs, or other financial needs. Additionally, reverse mortgages do not require monthly repayments like traditional mortgages do. Instead, the loan is typically repaid when the borrower moves out of the home or passes away.
However, it’s important for potential borrowers to understand that reverse mortgages come with certain risks and considerations. Interest rates and fees associated with these loans can be higher than those of traditional mortgages. Borrowers also need to continue paying property taxes, insurance premiums, and maintenance costs on the home to avoid defaulting on the loan.
Before considering a reverse mortgage, individuals should consult with a financial advisor or housing counselor to fully understand the implications and determine if it’s the right option for their specific situation. While reverse mortgages can provide much-needed financial flexibility for some retirees, careful consideration and planning are essential to ensure that it aligns with long-term financial goals.