Maximizing Your 401(k): Key Strategies for Long-Term Financial Security
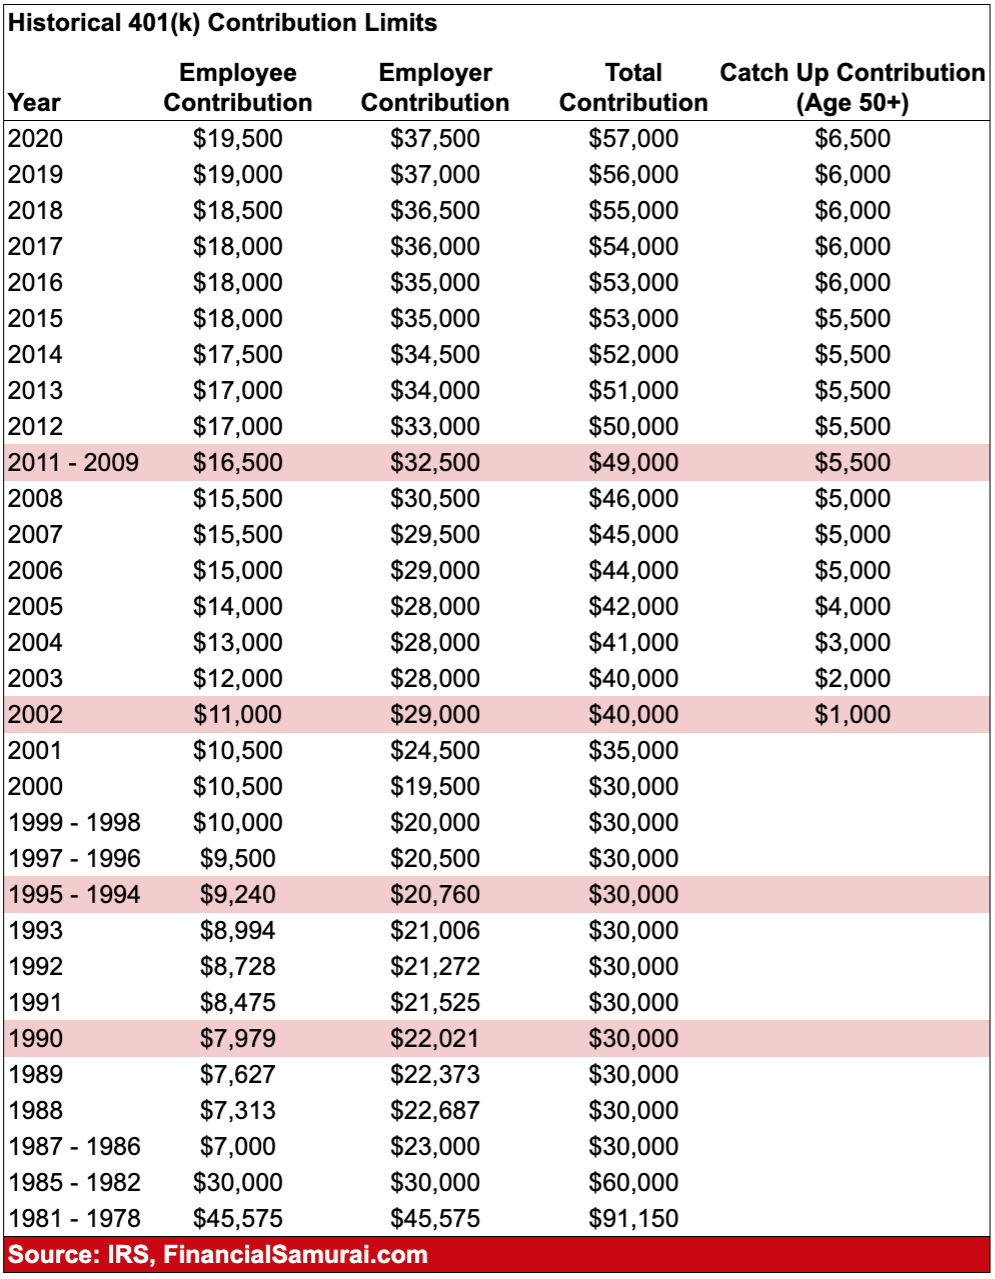
When it comes to planning for retirement, a 401(k) is a valuable tool that many individuals rely on to build their nest egg. There are several key considerations and strategies that can help individuals make the most of their 401(k) accounts. Let’s delve into various aspects of 401(k) plans and how they can be optimized for long-term financial security.
1. **Roth 401(k) vs Traditional 401(k):** One important decision when enrolling in a 401(k) plan is choosing between a Roth or Traditional account. In a Traditional 401(k), contributions are made with pre-tax dollars, reducing taxable income in the present but requiring taxes to be paid upon withdrawal in retirement. On the other hand, Roth 401(k) contributions are made with after-tax dollars, allowing for tax-free withdrawals in retirement. The choice between the two depends on individual circumstances such as current tax bracket and future retirement income expectations.
2. **Self-directed brokerage accounts within a 401(k):** Some employers offer self-directed brokerage accounts within their 401(k) plans, allowing participants to invest in individual stocks, bonds, or other securities beyond the traditional fund options provided by the plan. While this option offers more control over investment choices, it also comes with higher risk due to potential market volatility and requires more active management.
3. **Impact of inflation on 401(k) savings:** Inflation erodes the purchasing power of money over time, impacting the value of retirement savings held in a 401(k). It’s essential for investors to consider inflation when setting long-term financial goals and choose investments that have the potential to outpace inflation to maintain real returns.
4. **Catch-up contributions for individuals over 50:** Individuals aged 50 and older have the option to make catch-up contributions to their 401(k) accounts in addition to regular annual contribution limits set by the IRS. This provision allows older workers who may not have saved enough earlier in their careers to accelerate their savings as they approach retirement age.
5. **Employer matching contribution vesting schedules:** Many employers offer matching contributions as part of their employees’ benefits package; however, these employer contributions may be subject to vesting schedules that determine when employees become entitled to these funds based on years of service with the company.
6. **Impact of changing jobs on 401(K) accounts:** When changing jobs, individuals have several options for dealing with their existing employer-sponsored retirement account (e.g., rolling it over into an IRA or new employer’s plan). It’s crucial to weigh factors like investment options, fees, and convenience before making a decision about how best to manage old account balances.
7. **Using a 401(K) loan for emergencies:** While taking out loans from your own retirement savings should generally be avoided due to potential penalties and loss of growth opportunities if not repaid promptly or fully – some plans do allow participants facing financial hardship access through loans as an emergency measure under specific conditions which might need repayment within five years typically.
8 .**Tax implications of early withdrawals from a 410(K):** Withdrawing funds from your traditional (non-Roth), you’ll likely face taxes at ordinary income rates plus potentially an additional penalty if you’re under age fifty-nine-and-a-half unless exempted under certain conditions like disability or first-time home purchase up-to $10k lifetime maximum exemption etc.). Ensure you understand these implications before making any early withdrawal decisions
9 .**Fees associated with different investment options**: Various fees including administrative costs & fund expenses could impact returns especially concerning actively managed mutual funds whose higher expense ratios might eat away at gains compared against passive low-cost index-based investments typically found among target-date funds which aim balance exposure across multiple asset classes while automatically adjusting allocation towards less risky assets closer towards expected year-of-retirement date
10 .**Rollover Options For Old K Accounts**: Individuals leaving jobs where they contributed towards company-sponsored pension scheme often face decision whether rollover previous employer’s K-plan another institution take benefit better terms lower fees potentially enhanced investment choices via IRA offering wider array ETFs low-cost index fun…