Traditional vs. Roth IRAs: Which Retirement Savings Strategy is Right for You?
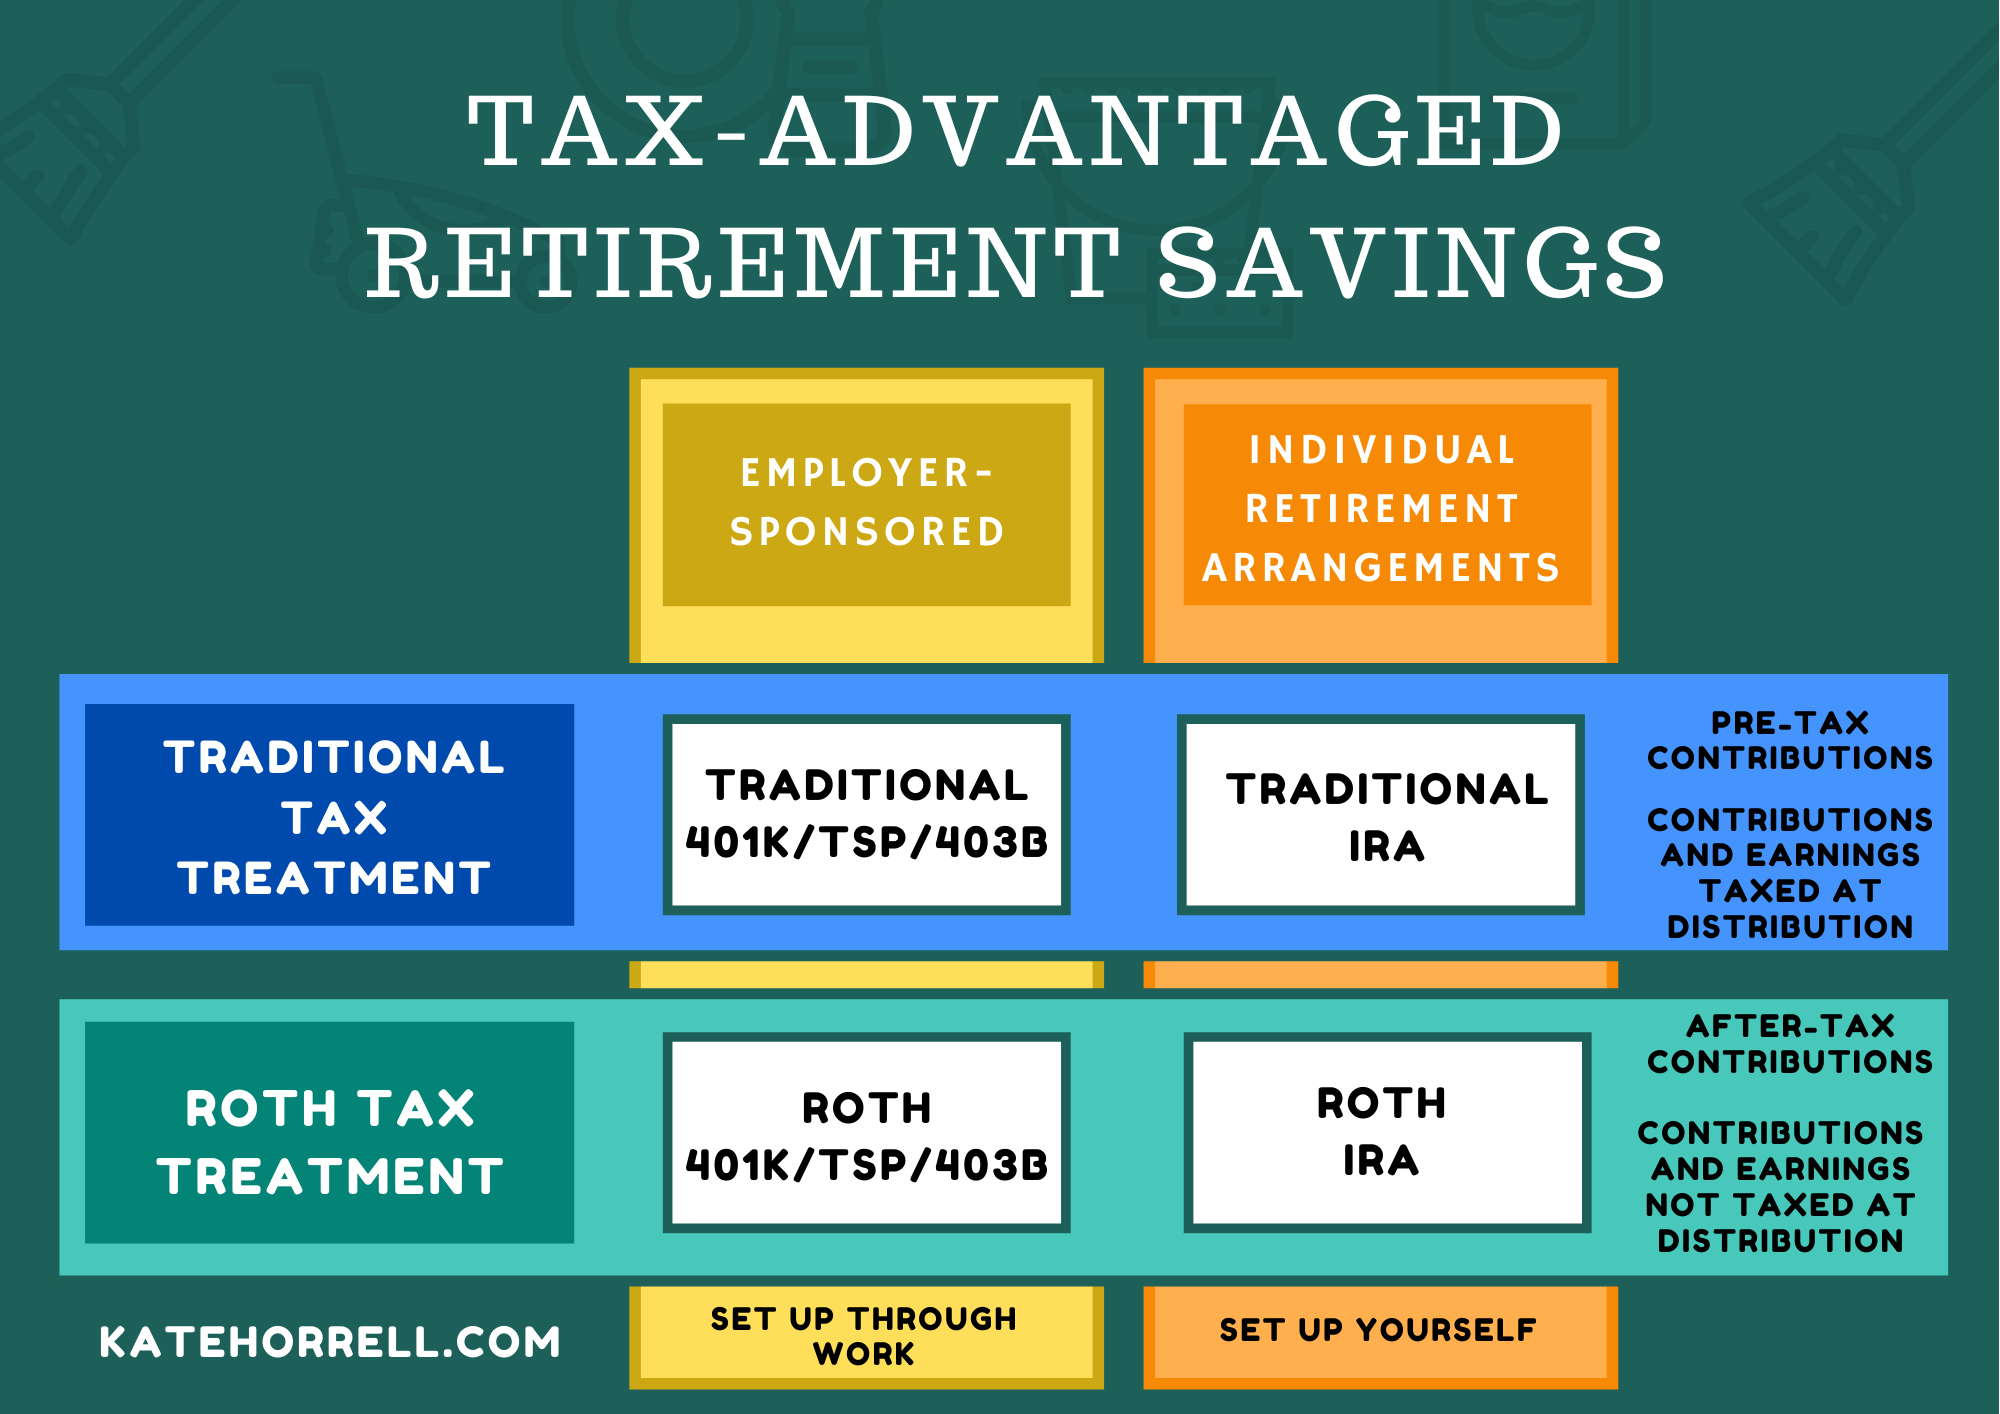
Individual Retirement Accounts (IRAs) are a popular choice for individuals looking to save for retirement in a tax-advantaged way. There are two main types of IRAs: Traditional and Roth. While both offer tax benefits, they differ in terms of when you receive those benefits. In this article, we will delve into the key differences between Traditional and Roth IRAs to help you decide which option may be best suited for your financial goals.
**Traditional IRA**
A Traditional IRA is a retirement account where contributions are made with pre-tax dollars, meaning that you can deduct your contributions from your taxable income in the year they were made. This can lower your current tax bill and allow your investments to grow tax-deferred until you start making withdrawals in retirement.
One of the major advantages of a Traditional IRA is immediate tax savings. By reducing your taxable income through contributions, you can potentially lower your overall tax liability each year while saving for retirement. Additionally, if you expect to be in a lower tax bracket during retirement than you are currently, a Traditional IRA may be advantageous as withdrawals will be taxed at your future, presumably lower rate.
However, it is important to note that withdrawals from a Traditional IRA are subject to ordinary income taxes at the time of distribution. Additionally, once you reach age 72 (as per current regulations), you must start taking Required Minimum Distributions (RMDs) from your Traditional IRA each year, regardless of whether or not you actually need the money.
**Roth IRA**
In contrast, a Roth IRA operates differently from its traditional counterpart. Contributions to a Roth IRA are made with after-tax dollars – meaning that there is no immediate tax deduction on contributions. However, one of the key benefits of a Roth IRA is that qualified withdrawals in retirement are completely tax-free.
By paying taxes upfront on contributions instead of at withdrawal like with a Traditional IRA, investors benefit from years of potential growth and compounding without having to worry about future taxes on their earnings or withdrawals.
Another advantage of a Roth IRA is that there are no RMD requirements during the account owner’s lifetime. This means that funds can continue growing tax-free for as long as desired and even passed down to heirs without being subject to distributions during the original account holder’s lifetime.
**Key Differences**
1. **Tax Treatment**: The primary difference between these two types of IRAs lies in how they handle taxes – with Traditional IRAs offering upfront deductions but taxing withdrawals later versus Roth IRAs taxing contributions but allowing for completely tax-free distributions down the line.
2. **Income Limits**: Another factor worth considering is income limits associated with contributing to each type of account. While anyone with earned income can contribute to an existing traditional or Roth account regardless of income level due by making non-deductible traditional contributions then converting them into Roths through what’s known as “backdoor” Roths – direct contribution limits do apply based on Modified Adjusted Gross Income levels.
3 . **Withdrawals**: Withdrawing funds early carries penalties under both types unless used toward specific exceptions such as first-time home purchases or certain medical expenses – though principal amounts contributed directly into Roths may generally be withdrawn penalty-free before age 59½ unlike earnings portions within five years post-conversion.
4 . **Required Minimum Distributions**: As mentioned earlier only traditional accounts mandate RMDs starting at age 72 currently rather than Roths which never require them during an original contributor’s life span.
5 . **Estate Planning Considerations**: For those intending their assets beyond themselves beneficiaries stand out more favorably receiving inherited Roths due since they have longer period avoid stretching taxation over time compared getting taxed upon receipt if inherited by non-spousal heirs via traditionals..
Ultimately choosing between these options depends heavily on individual circumstances including current versus anticipated future taxation rates personal risk tolerance investment strategies estate planning preferences among other factors so consider consulting certified financial planner prior shifting course toward either direction manage wealth effectively maximize returns come golden years..