The Evolution of Auto Loans: Shaping Car Ownership and the Industry
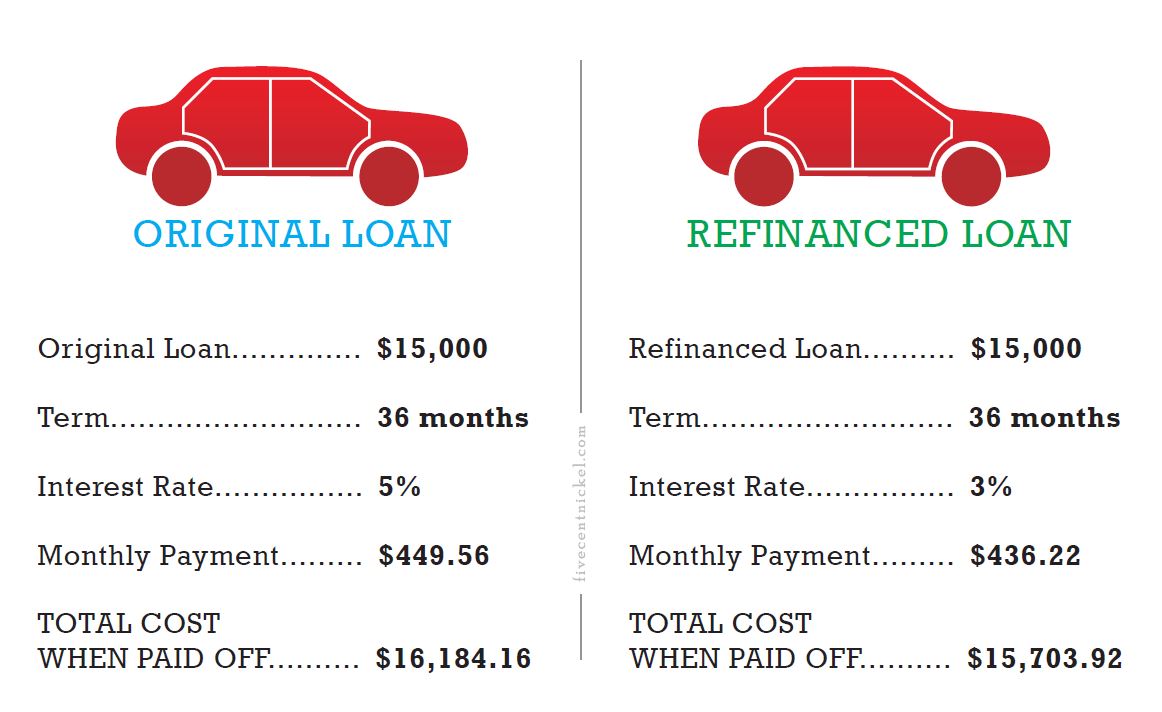
Auto loans have become a common method for individuals to finance their vehicle purchases, but this was not always the case. The concept of auto loans has evolved over time, shaping the way people buy cars and influencing the automotive industry as a whole.
In the early 20th century, when automobiles were first introduced to the masses, purchasing a car required paying in full upfront. This made owning a car inaccessible for many individuals, as the cost was often prohibitive. As demand for cars increased and manufacturers sought ways to make their products more affordable, financing options began to emerge.
General Motors was one of the pioneers in offering installment plans for car purchases in 1919 through its newly established financial services arm, General Motors Acceptance Corporation (GMAC). This allowed customers to pay for their cars over time through monthly payments, making car ownership more attainable for a broader range of consumers.
The widespread adoption of auto loans gained momentum in the post-World War II era when consumerism flourished, and owning a car became synonymous with the American dream. Banks and other financial institutions started offering auto loans with varying terms and interest rates to meet the growing demand from consumers looking to buy cars.
During this period, auto loans typically had shorter loan terms compared to today’s standards, often lasting three to four years. Interest rates were also higher due to economic conditions at the time. Despite these challenges, auto loans continued to gain popularity as more people embraced car ownership as essential rather than luxury.
The 1970s marked another significant shift in auto lending with the introduction of longer loan terms. As cars became more expensive due to advancements in technology and features, borrowers sought extended repayment periods to lower their monthly payments. Lenders responded by offering five-year and later seven-year loan terms – an approach that continues today.
The evolution of auto loans also saw changes in how they were structured. Balloon payment loans emerged during this period where borrowers paid lower monthly installments throughout most of the loan term but faced a large lump sum payment at its conclusion. While these types of loans offered initial affordability benefits, they also carried higher risks for borrowers who might struggle with balloon payments.
In recent years, there has been a trend toward longer loan terms exceeding seven years coupled with rising average loan amounts. While extended repayment periods can make buying a car more manageable on a month-to-month basis by spreading out costs over time; it also means paying more interest overall which increases the total cost of borrowing.
Despite these trends towards longer terms and larger amounts borrowed; it is important for consumers not lose sight of their financial well-being when taking out an auto loan. Understanding all aspects such as interest rates; fees involved; repayment schedules; potential impact on credit score are crucial before committing any long-term financial obligation like an auto loan
In conclusion; Auto loans have come a long way since their inception nearly a century ago.; They have transformed how people purchase vehicles making it accessible even those without substantial savings or immediate funds available.; However understanding evolving nature along with implications that come attached will enable better decision-making process while considering taking out such financing option