Navigating the Complexities of Building Net Worth: Key Factors to Consider
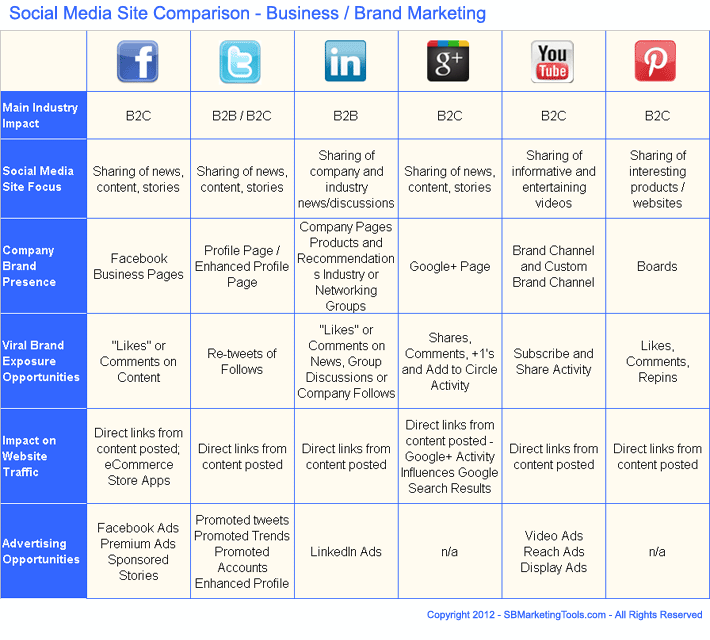
Social media has become an integral part of our daily lives, influencing how we perceive ourselves and others. The impact of social media on perceived net worth is significant as individuals often compare their lifestyles, possessions, and achievements to those they see online. This can lead to feelings of inadequacy or pressure to keep up with the perceived wealth displayed on social platforms.
The net worth implications of student loan debt are a growing concern for many young adults today. High levels of student debt can hinder one’s ability to build wealth over time as monthly payments eat into disposable income that could otherwise be invested or saved. Finding a balance between paying off student loans and saving for the future is crucial in improving one’s overall net worth.
Freelancers and gig workers face unique challenges when it comes to building their net worth. Fluctuating income streams, lack of employee benefits such as retirement plans or health insurance, and irregular work patterns can make it difficult to establish financial stability. Creating a budget, setting aside savings during high-earning periods, and diversifying income sources are key strategies for freelancers looking to increase their net worth.
Mental health can have a profound impact on one’s ability to build wealth. Issues such as anxiety, depression, or addiction can lead to overspending, impulse decisions, or difficulty holding down a job – all of which can negatively affect net worth. Seeking professional help when needed, creating healthy coping mechanisms, and staying organized with finances are essential steps in maintaining mental well-being and improving overall financial health.
Inheritance plays a significant role in determining an individual’s net worth. Receiving assets or funds from family members can provide a substantial financial boost and potentially set the stage for future wealth accumulation through investments or property ownership. However, inheritance should be viewed as a supplement rather than the sole foundation for building net worth.
Early retirees need to carefully consider how their lifestyle choices will impact their long-term financial security. With potentially decades of retirement ahead, managing expenses prudently and ensuring that savings last throughout retirement is crucial in maintaining a healthy net worth over time.
Gender disparities persist when it comes to net worth accumulation. Women typically earn less than men due to the gender pay gap and are more likely to take breaks from their careers for caregiving responsibilities – both factors that can hinder wealth-building opportunities. Addressing systemic inequalities through advocacy efforts and promoting equal pay policies are essential steps in bridging this gap.
Living in high cost-of-living areas presents challenges for individuals looking to grow their net worth. Higher housing costs, increased living expenses, and inflated prices on goods/services can strain budgets and limit opportunities for saving or investing money towards long-term goals. Downsizing living arrangements or exploring remote work options may help mitigate some of these challenges.
Career changes or job loss can have immediate consequences on one’s financial stability and overall net worth trajectory. Building an emergency fund, updating skills regularly through education/training programs, networking within industries/markets with growth potential are vital strategies in adapting successfully during times of transition while safeguarding one’s financial well-being.
Education level correlates strongly with higher earning potential which directly impacts an individual’s ability to grow their net worth over time if managed wisely.
Single parents face unique financial challenges due primarily because they shoulder the responsibility alone; however taking advantage government assistance programs (if available), seeking out affordable childcare options,
and prioritizing self-care helps alleviate some pressures allowing them focus more effectively managing their finances.
Financial infidelity erodes trust between partners affecting not only emotional but also financial well-being making open communication about money matters imperative.
Credit score significantly affects access credit terms/limits interest rates etc impacting how much you’d ultimately spend/save/grow your nest egg
Entrepreneurs/business owners must manage business & personal finances separately ensure adequate insurance coverage plan succession exits create emergency funds diligently track cash flow
Calculating true asset value involves documenting market values debts associated understanding taxes deductions depreciation costs involved resulting accurate assessment enabling informed decisions moving forward towards achieving desired objectives helping secure better future financially speaking