Navigating the Pros and Cons of Joint Accounts: A Guide to Shared Financial Management
Joint accounts can be a useful financial tool for individuals who want to share ownership and management of funds with another person, whether it’s a partner, roommate, family member, or business partner. They offer both advantages and disadvantages that should be carefully considered before opening one.
One of the main benefits of a joint account is the convenience it offers in managing shared expenses. It allows all account holders to deposit and withdraw money, making bill payments and budgeting easier. Additionally, joint accounts can facilitate transparency and accountability in financial matters between the account holders.
However, there are drawbacks to consider as well. Joint accounts can lead to conflicts if there are disagreements on how the funds should be used or managed. All account holders have equal access to the funds, which could potentially result in misuse by one party. Furthermore, if one account holder has poor credit or incurs debts, it could affect the other account holder’s credit score.
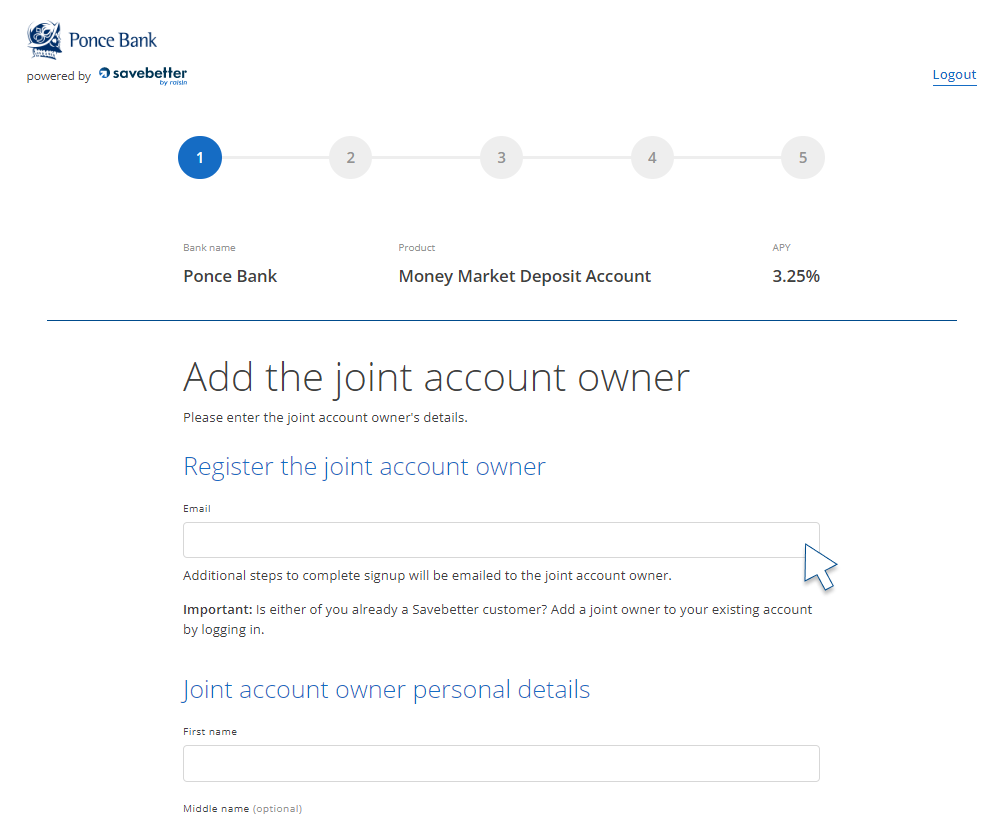
To open a joint account, all parties involved typically need to visit a bank or financial institution together and provide identification documents such as government-issued IDs and proof of address. The process may vary depending on the institution’s requirements.
Comparing joint accounts to individual accounts, joint accounts allow multiple people to manage finances together while individual accounts provide sole ownership and control over funds. Individual accounts may be more suitable for personal savings goals or maintaining financial independence.
Managing finances in a joint account requires open communication between all parties involved. Setting clear guidelines on how the funds will be used, establishing spending limits if necessary, and regularly reviewing transactions can help prevent misunderstandings or disputes.
When setting financial goals with a joint account, it’s important for all parties to align their objectives and priorities. Whether saving for a major purchase like a home or planning for retirement together, having shared goals can motivate everyone to work towards achieving them collectively.
Tips for successful joint account management include setting up regular meetings to discuss finances, using budgeting tools or apps to track expenses collaboratively, keeping each other informed about any significant transactions or changes in income/expenses, and being transparent about individual financial habits.
For couples considering a joint account as part of their relationship dynamics; it can promote trust and unity in managing shared finances but requires honesty about spending habits and long-term financial goals from both partners.