Mastering Credit Limits: The Key to Financial Health
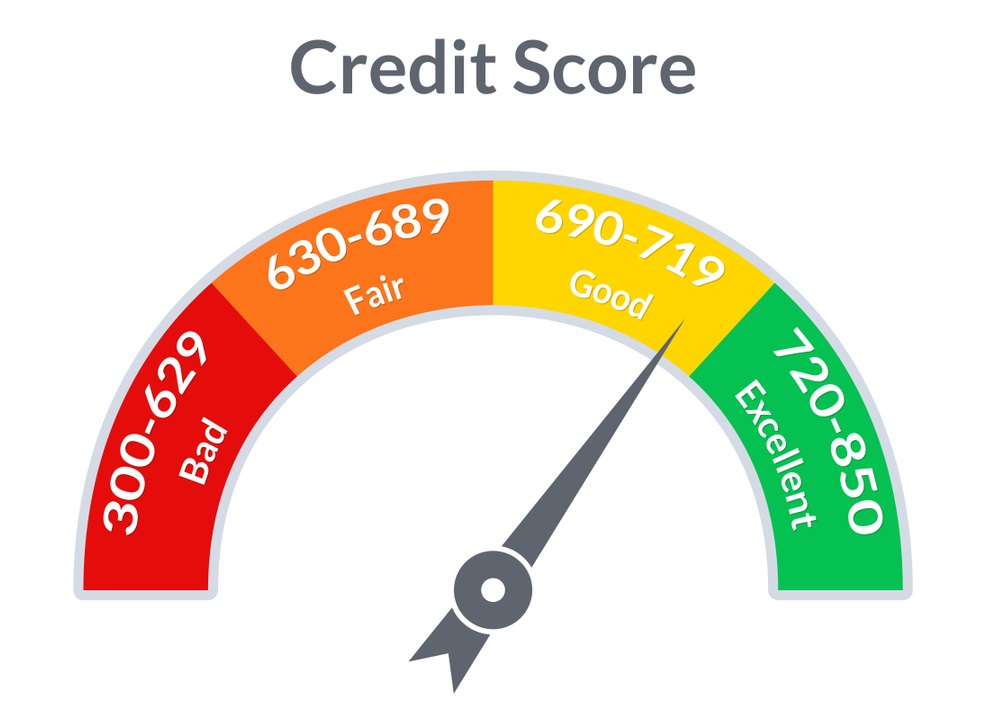
When it comes to managing your finances and building a healthy credit profile, understanding how credit limits are determined is crucial. Your credit limit is the maximum amount of money that a financial institution is willing to extend to you on a revolving line of credit, such as a credit card. This limit is based on various factors and can have significant implications for your overall financial health.
Factors That Can Affect Your Credit Limit:
1. Credit Score: One of the most important factors that determine your credit limit is your credit score. Lenders use this three-digit number, which reflects your creditworthiness based on your credit history and current financial situation, to assess the risk of lending to you. Generally, individuals with higher credit scores are more likely to qualify for higher credit limits.
2. Income: Your income plays a key role in determining your credit limit because it indicates your ability to repay any borrowed funds. Lenders typically consider both your annual income and other sources of revenue when assessing how much credit they can comfortably extend to you.
3. Credit History: Your past borrowing behavior also influences the determination of your credit limit. Lenders look at factors such as whether you’ve made timely payments on previous debts, how long you’ve had accounts open, and the types of accounts you currently hold.
4. Debt-to-Income Ratio: Lenders evaluate your debt-to-income ratio by comparing how much debt you have relative to your income level. A lower ratio suggests that you have more disposable income available for repaying new debts, which may result in a higher credit limit being offered.
5. Employment Status: Stable employment demonstrates financial stability and may positively impact the determination of your credit limit.
Tips for Increasing Your Credit Limit:
If you’re looking to increase your existing credit limit or secure a higher one when applying for new lines of credits, consider these tips:
1. Improve Your Credit Score: Work on enhancing your payment history, reducing outstanding debt levels, and maintaining old accounts in good standing – all actions that can boost your score over time.
2. Request an Increase: Contacting the card issuer directly and asking for a higher limit can sometimes yield positive results if there have been improvements in your financial situation since initially setting up the account.
3. Monitor Your Spending Habits: Responsible usage of existing lines of credits – consistently paying bills on time and keeping balances low relative to available limits – can signal responsible borrower behavior and potentially lead issuers to increase limits proactively or upon request.
The Impact Of Credit Utilization On Your Credit Limit:
Credit utilization refers to how much of available revolving account balances (such as those from cards) consumers are using at any given point in time compared against total available limits across accounts combined—a metric used by lenders when evaluating risk profiles.
A high utilization rate often signals potential financial strain or overspending habits; hence keeping this figure under 30% across all active accounts helps maintain favorable scoring models.
Understanding The Relationship Between Credit Score And Credit Limit:
Your FICO score impacts not only eligibility but also terms like interest rates associated with opening new lines—higher scores indicate better repayment probabilities whereas lower ones trigger tighter conditions including lower amounts sanctioned.
Managing Multiple Credit Limits Effectively:
Juggling multiple cards involves meticulous budgeting skills ensuring each balance stays within manageable thresholds while meeting respective due dates promptly—avoids accruing interest charges while preventing negative impacts towards future loan applications.
Importance Of Staying Within Your Credit Limit:
Exceeding set spending caps triggers penalties ranging from fees imposed by issuing banks through interest rates escalating upwards alongside adverse effects registered against individual ratings—prudent monitoring wards off detrimental consequences affecting personal finance standings.
Strategies For Negotiating A Higher Credit Limit With Issuers:
Review current spending patterns showcasing responsible handling coupled with increased income streams warranting upward adjustments—advocating prudent reasons supported by solid track records could sway decisions favorably toward expanded allowances.
How To Request A Credit Limit Increase Online Or Over The Phone:
Common Misconceptions About Credt Limits:
Popular myths include beliefs stating frequent increases harm scores or accepting pre-approved raises automatically benefits holders without downsides—inaccuracies necessitating clarification among consumers seeking effective management techniques.
Difference Between Hard And Soft Inquiries For Increases:
Checking Current Credt Limits:
Risks Of Exceeding Credt Limits:
Credit Card Issuers With Flexible Or Adjustable Credt Limits:
Setting A Responsible Personal Credt Limt:
Connection Between Income And Credt Limts:
Using Balance Transfers To Manage Overall Available Crdit:
Impact Of Missed Payments On Current And Future Crdt Limts:
Crdit Building Strategies For Those With Low Initial Limts :
Understanding Relationships Between Different Account Types: