Mastering Money: The Art of Creating a Budget
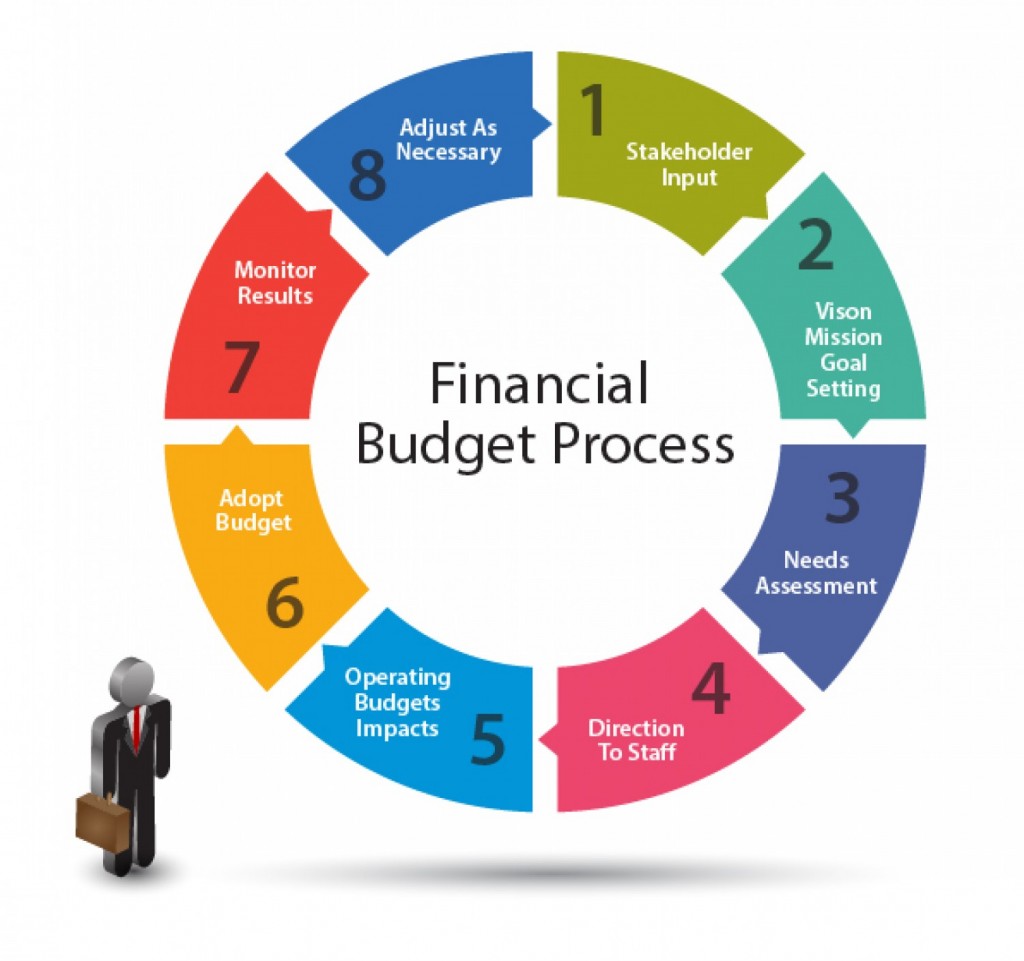
Creating a Budget
What is a budget?
A budget is essentially a financial plan that outlines your income and expenses over a specific period. It helps you understand where your money is coming from, where it’s going, and how you can manage it more effectively.
Why is creating a budget important?
Creating a budget is crucial for several reasons:
1. **Financial Awareness:** A budget gives you a clear picture of your finances, helping you make informed decisions.
2. **Goal Setting:** It enables you to set financial goals and track your progress towards achieving them.
3. **Control Spending:** By tracking expenses, you can identify areas where you may be overspending and adjust accordingly.
4. **Emergency Preparedness:** Having a budget allows you to allocate funds for emergencies or unexpected expenses.
How do I create a budget?
1. **Calculate Your Income:** Start by determining all sources of income, including salaries, bonuses, investments, etc.
2. **List Your Expenses:** Categorize your expenses into fixed (rent/mortgage) and variable (groceries, entertainment).
3. **Set Financial Goals:** Decide what you want to achieve financially – saving for a house, paying off debt – and prioritize these goals in your budget.
4. **Track Your Spending:** Keep track of every expense using apps or spreadsheets to ensure accuracy.
5. **Adjust as Needed:** Regularly review your budget to see if adjustments are necessary based on changes in income or expenses.
Tracking Expenses
Why should I track my expenses?
Tracking expenses is vital because it helps:
1- Identify spending patterns
2- Control impulse purchases
3- Stay within budget limits
4- Plan future expenditures effectively
How can I track my expenses effectively?
1- Use Apps: There are numerous finance-tracking apps like Mint or YNAB that sync with bank accounts for real-time updates.
2- Save Receipts: Keep receipts organized by category so they’re easy to reference when recording transactions.
3- Monitor Regularly: Set aside time each week to review your spending and see where adjustments are needed.
Setting Financial Goals
What are financial goals?
Financial goals are specific objectives related to money management that an individual sets for themselves.
Why should I set financial goals?
Setting financial goals provides direction and motivation as they help:
1- Prioritize Spending
2- Measure Progress
3- Build Long-Term Wealth
4- Prepare for Retirement
How do I set financial goals?
1 – Define Objectives: Be clear about what you want to achieve – be it saving for retirement or buying a home
2 – Quantify Goals: Attach specific amounts and timelines to each goal – e.g., save $10k for emergency fund within 12 months
3 – Break Down Into Steps: Divide larger objectives into smaller milestones; this makes them more achievable
Emergency Funds
What is an emergency fund?
An emergency fund serves as a safety net providing immediate cash during unexpected situations like job loss or medical emergencies
Why do I need an emergency fund?
Having an emergency fund prevents resorting to high-interest loans or credit cards during crises
How much should my emergency fund be?
Financial experts recommend saving 3–6 months’ worth of living expenses in an emergency fund
Saving Strategies
How can I save money efficiently?
Implement the following strategies
Automate Savings : Set up automatic transfers from checking account into savings
Cut Unnecessary Costs : Review subscriptions/services not being used
Meal Prep : Cooking meals at home instead of eating out saves significant money
Debt Management
Why should I manage debt effectively?
Managing debt ensures better credit score & reduces stress associated with owing money
How can I manage debt successfully?
Follow these practices
Pay More Than Minimum Payment : Reduces overall interest paid
Prioritize High-interest Debt : Focus on debts with highest interest rates first
Seek Professional Help If Needed : Consult credit counselors if overwhelmed by debt
Credit Card Usage
Are credit cards beneficial or harmful?
Depends on use; benefits include rewards & convenience while misuse leads to debt accumulation
How can I use credit cards wisely?
Pay Balance Monthly : Avoid accruing high-interest charges
Monitor Spending Closely : Ensure not exceeding monthly budget
Utilize Rewards Wisely : Redeem points/cashback sensibly
Retirement Planning
When should retirement planning start?
Ideally early as possible but definitely before mid-career stage
Which retirement plans exist usually ?
401(k), IRA (Traditional/Roth), Pension Plans
Investing Basics
Is investing necessary ?
Yes ,to grow wealth faster than just relying on savings accounts
Where can one invest generally ?
Stock market , Mutual Funds , Real Estate
Insurance Coverage
Which insurances are essential ?
Health Insurance , Auto Insurance , Homeowners Insurance
Housing Costs
Should rent/mortgage exceed certain %age of income ?
Rule-of-thumb suggests housing costs shouldn’t exceed 30% of gross income
Transportation Expenses
Should transportation cost include car maintenance/repairs too ?
Yes ; account not only fuel costs but also maintenance/repair bills
Food & Dining Budgeting
Best ways reduce food/dining costs ?
Meal prepping , limiting dining out frequency
Entertainment Spending
Can entertainment budgets be flexible ?
Yes ; allocate reasonable amount but adjust based on overall financial situation
Travel Budgeting Tips
Tips travel affordably ?
Plan trips well advance , look discounts/offers
Health & Wellness Costs
Should health insurance cover gym memberships/yoga classes etc.?
Some policies offer wellness benefits but confirm details with insurer
Education Expenses
Best way plan/save education costs ?
Start college savings account early; consider 529 plans
Budgeting For Special Occasions
Special occasion budgets different regular months expenditure ?
Allocate extra funds few months prior special event
Pet Care Costs
Pet care expensive ; any tips lowering costs ?
Regular vet visits prevent costly illnesses later
Charity And Donations
Importance giving back even tight budgets ?
Even small donations impactful ; set aside fixed amount monthly
In conclusion:
Effective personal finance management involves creating budgets tailored around individual circumstances while setting realistic short-term & long-term monetary objectives . Tracking daily expenditures closely ensures staying within assigned limits aiding achieving preset targets expediently . Proper planning empowers individuals meet unforeseen contingencies smoothly thus ensuring comprehensive fiscal stability always upheld .
Remember—financial discipline today secures prosperous tomorrows!