Navigating the Mobile Home Mortgage Maze: Finding the Right Financing Fit
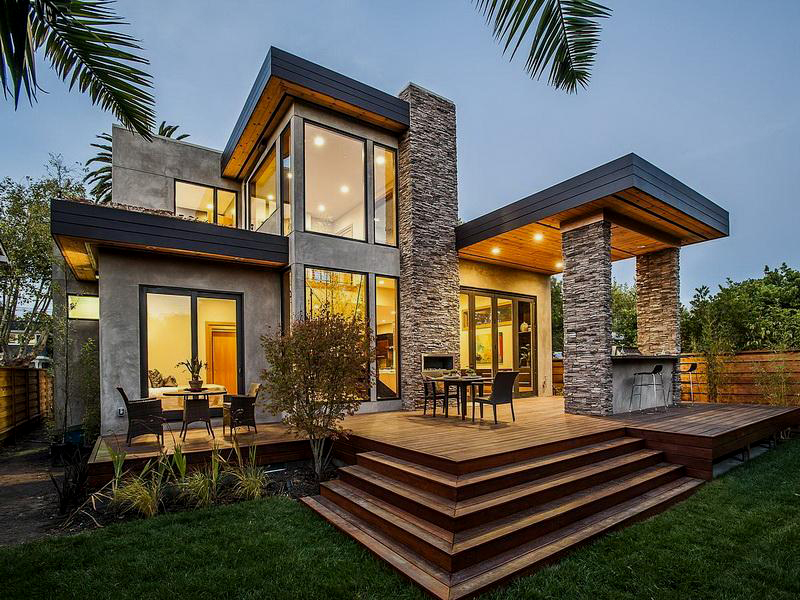
Mobile homes have come a long way from the stereotypical image of cramped and outdated living spaces. Today, modern mobile homes offer affordability, flexibility, and an opportunity for homeownership that appeals to many individuals and families. With their lower costs compared to traditional houses, mobile homes are becoming an increasingly popular choice for those looking to enter the housing market or downsize without sacrificing comfort.
One of the key considerations when purchasing a mobile home is financing. Just like with traditional houses, there are various mortgage options available to help make owning a mobile home more attainable. Let’s explore some of these options in more detail:
Adjustable-rate mortgages (ARMs) vs. fixed-rate mortgages:
When it comes to financing your mobile home purchase, one of the first decisions you’ll need to make is whether to opt for an adjustable-rate mortgage (ARM) or a fixed-rate mortgage. With an ARM, your interest rate can fluctuate over time based on market conditions, while a fixed-rate mortgage locks in your interest rate for the duration of the loan.
For those who plan to stay in their mobile home for only a few years or expect interest rates to decrease in the future, an ARM may initially offer lower monthly payments. However, it’s important to consider potential rate increases down the line that could impact your ability to afford your payments.
On the other hand, a fixed-rate mortgage provides stability and predictability since your monthly payments will remain consistent throughout the loan term. This can be advantageous if you prefer knowing exactly how much you’ll owe each month and want protection against rising interest rates.
Second-chance mortgages after foreclosure or bankruptcy:
If you’ve experienced financial setbacks such as foreclosure or bankruptcy in the past but are now back on track financially, you may still be able to qualify for a second-chance mortgage on a mobile home. These programs are designed specifically for individuals who have faced challenges in the past but have demonstrated improved financial responsibility since then.
While these loans may come with higher interest rates or stricter eligibility requirements than conventional mortgages, they provide an opportunity for individuals to rebuild their credit and achieve homeownership once again.
Bridge loans as a short-term mortgage solution:
Bridge loans can be useful tools for those looking to purchase a new mobile home before selling their current property. These short-term loans bridge the gap between buying a new home and selling an existing one by providing funds upfront that can later be repaid once your previous property is sold.
This type of financing can be particularly beneficial in competitive real estate markets where securing a new home quickly is essential. However, it’s important to carefully consider repayment terms and any associated fees before opting for a bridge loan.
Mortgages for investment properties and rental income:
For those interested in purchasing a mobile home as an investment property rather than as their primary residence, there are specific mortgage options tailored to this scenario. Investors can secure financing based on potential rental income from tenants occupying the property.
Lenders typically assess factors such as expected rental revenue and occupancy rates when evaluating loan applications for investment properties. Additionally, investors may need to meet specific criteria related to their financial standing and experience with rental properties.
In conclusion,
Choosing the right mortgage option when purchasing a mobile home requires careful consideration of your financial goals and circumstances. Whether you’re exploring ARMs versus fixed-rate mortgages or seeking second-chance financing after past difficulties, there are solutions available that can help make owning a mobile home achievable.