Harnessing the Power of Compound Interest: A Path to Wealth Accumulation
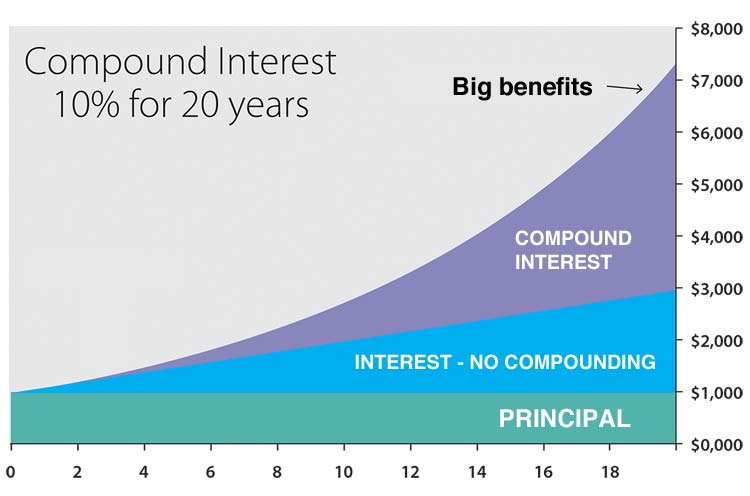
Compound interest is a powerful financial concept that can significantly impact your wealth over time. One of the key principles related to compound interest is the Rule of 72. The Rule of 72 is a simple formula used to estimate how long it will take for an investment to double at a fixed annual rate of interest. By dividing 72 by the annual rate of return, you can get an approximate number of years it will take for your investment to double.
For example, if you have an investment with an annual return of 6%, using the Rule of 72, it would take approximately 12 years (72 divided by 6) for your money to double. This rule highlights the power of compounding – as your money earns returns, those returns themselves earn more returns over time.
The power of compounding lies in reinvesting earnings and allowing them to generate even more earnings. Unlike simple interest, which only calculates interest on the principal amount, compound interest includes both the initial principal and any previously earned interest. This exponential growth can lead to significant wealth accumulation over long periods.
Investing early is crucial when it comes to maximizing the benefits of compound growth. The longer your money has time to grow and compound, the greater your overall returns will be. Even small amounts invested consistently over time can grow into substantial sums due to compounding.
Different investments offer various compounding frequencies such as daily, monthly or annually. The more frequent the compounding period, the faster your investment grows since you are earning returns on a more regular basis.
Online compound interest calculators are valuable tools that allow you to visualize how your investments can grow over time with compounded returns. By inputting variables such as initial investment amount, annual contribution, interest rate and compounding frequency, these calculators give you a clear picture of how wealth accumulates through compounding.
Historical examples demonstrate how compound interest has played a significant role in building fortunes. For instance, Warren Buffett’s vast wealth largely stems from his investments benefiting from decades-long compounded growth in companies like Berkshire Hathaway.
Inflation’s impact on compound interest cannot be ignored either – while investing offers potential for high returns through compounding, inflation erodes purchasing power over time if not accounted for in investment decisions.
Retirement accounts like IRAs and 401(k)s utilize compound interest to help individuals save for their golden years efficiently. By starting early and consistently contributing while taking advantage of employer matches or tax benefits offered by these accounts, individuals can harness the power of compounding for retirement planning.
Strategies like diversification across asset classes and industries help maximize gains from compound interest while minimizing risk associated with individual investments’ volatility.
Reinvesting dividends is another way investors benefit from compound growth – instead of cashing out dividend payments received from stocks or mutual funds; reinvesting them allows those earnings also to generate additional earnings over time.
Understanding the concept of time value of money emphasizes that receiving money today is worth more than receiving it in future due terms like inflation eroding its value
Real estate investments also benefit from compounded growth through property appreciation coupled with rental income reinvestment strategies.
Leveraging Compound Interest towards achieving financial independence involves strategic planning around savings rates and expected rates
Risk plays into any decision regarding investments aiming at harnessing Compound Interest gains- Higher-risk ventures may promise higher ROI but could lead losses too
Tax implications should always be considered when dealing with Compound Interest especially depending on different types assets being held
Behavioral finance comes into play when emotional decision-making affects one’s ability follow long-term investing plans aimed at reaping Compound Interest rewards
Debt repayment following Compounded Interest logic requires timely repayments avoiding accrued interests eating away payments made
Long-term financial goals require understanding Compounded Interests mechanisms ensuring optimal plans set up yielding maximum results
In conclusion,Ccompoundinterest remains an invaluable tool in accumulating wealth regardless offinancial goals pursued.!