Navigating the Maze of Student Loans: Tips for Responsible Borrowing
Student loans are a common way for individuals to finance their education, whether it be undergraduate or graduate studies. These loans can come from the federal government or private lenders, and they provide financial support to cover tuition, books, and living expenses while pursuing higher education.
Federal student loans typically offer more favorable terms compared to private loans. They usually have lower interest rates and more flexible repayment options. There are various types of federal student loans available, such as Direct Subsidized Loans, Direct Unsubsidized Loans, and Direct PLUS Loans. The amount you can borrow will depend on your year in school and whether you are considered a dependent or independent student.
Private student loans, on the other hand, are provided by banks, credit unions, or online lenders. These loans may have higher interest rates compared to federal loans and often require a cosigner if the borrower has limited credit history or income. It’s essential to compare different loan options before deciding which one is best suited for your needs.
When taking out student loans, it’s crucial to understand the terms of the loan agreement thoroughly. Make sure you know the interest rate, fees associated with the loan, repayment schedule, and any deferment or forbearance options available. Being informed about these details can help you make responsible borrowing decisions and avoid financial hardship in the future.
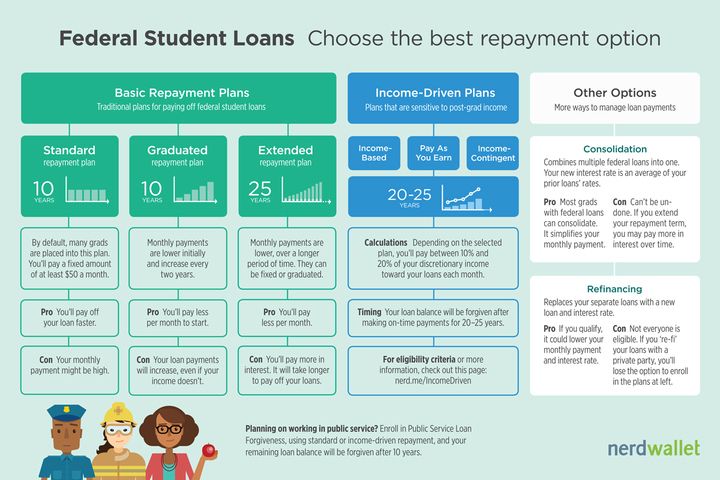
One significant advantage of federal student loans is that they offer various repayment plans tailored to borrowers’ financial situations. Income-Driven Repayment Plans allow borrowers to make payments based on their income level, making it easier to manage monthly expenses while repaying their debt. Public Service Loan Forgiveness (PSLF) is another program that forgives remaining debt after working in qualifying public service jobs for a certain period.
If you’re struggling to make your student loan payments due to financial difficulties or unforeseen circumstances like job loss or illness, don’t hesitate to reach out to your loan servicer for assistance. They may be able to offer options such as deferment or forbearance temporarily pause your payments until you get back on track financially.
It’s important not to ignore your student loan debt as defaulting on your loans can have severe consequences such as damaged credit score, wage garnishment, and even legal action taken against you by lenders. If you’re facing challenges with repayment after exploring all available options through your loan servicer without success consider seeking advice from a reputable credit counselor who can provide guidance on managing debt effectively.
In conclusion…