Bridging the Wealth Gap: Global Financial Challenges and Solutions
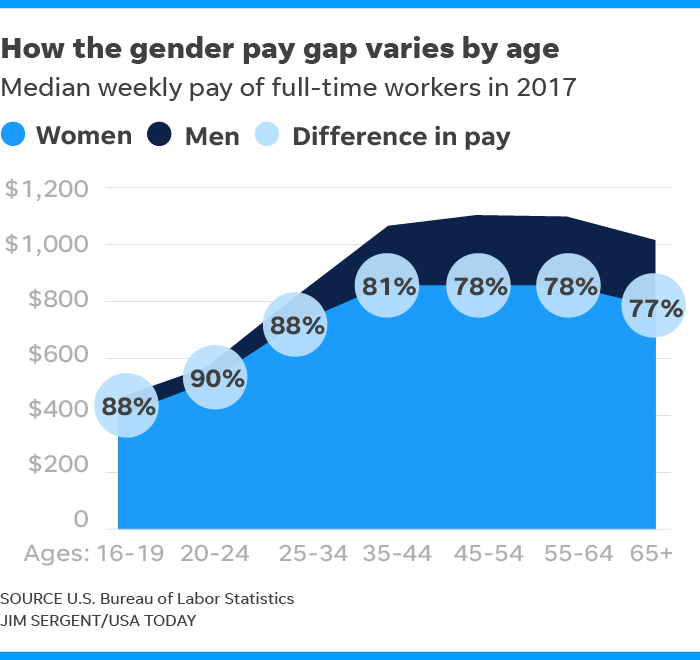
Gender pay gap in the United States remains a significant issue despite decades of progress towards gender equality. On average, women earn about 82 cents for every dollar earned by men, with the gap being even wider for women of color. Factors such as occupational segregation, discrimination, and lack of family-friendly policies contribute to this disparity. Efforts to address the gender pay gap include advocating for equal pay legislation, promoting salary transparency, and encouraging companies to conduct regular pay equity audits.
In Canada, there is a noticeable racial wealth gap that disproportionately affects Indigenous peoples and visible minorities. Historical injustices such as colonization and systemic racism have hindered wealth accumulation within these communities. Initiatives focusing on financial education and entrepreneurship support are crucial in bridging this wealth divide and creating more equitable opportunities for all Canadians.
Access to financial education in Mexico is limited, particularly in rural areas and among marginalized populations. Lack of basic financial knowledge hinders individuals from making informed decisions about savings, investments, and debt management. Improving access to financial literacy programs can empower citizens to take control of their finances and work towards economic stability.
In Brazil, homeownership disparities exist due to income inequality and limited access to affordable housing options. The government has implemented social housing programs to address this issue; however, challenges persist in providing adequate housing solutions for all Brazilians. Closing the homeownership gap requires comprehensive policies that prioritize affordable housing initiatives and support low-income families in achieving homeownership.
Indigenous communities in Australia face higher poverty rates compared to the general population due to historical marginalization and ongoing socio-economic challenges. Addressing poverty among Indigenous Australians necessitates targeted interventions that focus on improving access to education, healthcare, employment opportunities, and social services tailored to their specific needs.
Income inequality is a pressing concern in South Africa with a large wealth gap between the affluent minority and the majority of low-income earners. Structural barriers such as high unemployment rates, insufficient skills training programs, and limited access to quality education perpetuate this inequality. Policy interventions aimed at promoting inclusive economic growth through job creation strategies can help reduce income inequality over time.
Financial inclusion initiatives are essential in India where a significant portion of the population remains unbanked or underbanked. By expanding access to banking services, credit facilities, insurance products,and digital payment platforms especially among marginalized communities empowerment can be fostered leadingto greater financial security ultimately contributing towards overall economic development.
Japan faces challenges related specifically todiscrimination against womeninthe workplace affecting their career advancement opportunitiesand earning potential.Despite advancementsin gender equality laws,gaps still existwithin corporate culturesleadingto unequal treatmentof female employees.Promoting diversityandinclusion practicesas well as implementing transparent hiringand promotion processescan help addressgender discrimination issues within Japanese workplaces fosteringa more equitable working environmentforall employees regardless of gender identity
Wealth distributionin South Koreais heavily skewedwitha concentrationof wealthamongthe top percentile while manystrugglewithfinancial insecurity.Increased taxationonthe wealthy,social welfare reforms,and investment inseconomic redistributionprogramscan help narrowingthegapbetween therichandpoorpromoting amoreequitable societyfor allcitizensregardless offinancial status
Retirement savingschallengesare prevalentin Chinawithan agingpopulationandasavingsratesnotkeeping pacewithlong-term retirementneeds.Policiesencouragingearlyretirement planningincreased pension contributionlimits,andexpandingaccess tonon-traditional retirement savingoptionslikeinvestmentfundsorannuitiescanhelp individualssaveadequatelyfortheir future retirementsenhancingfinancial securityamong elderlypopulationsacross China
Housing affordabilityissuespersistinthe United Kingdomespecially indensely populated urbanareaswherehousing costsoutpaceincomegrowth.Market regulationsto prevent speculativeinvestments,rural developmentinitiativesfor balancedgeographicaldistributionoffordablehousingstocksinvestmentincouncil housingschemes,togetherwithfirst-time buyersupportprogramsarekeymeasures neededtomakehomeownershipmoreattainableforall residentsregardlessofincomelevelorsocialstatus
The Student LoanDebt Crisisremainsa majorconcerninthe United Statesasincreasing numbersof graduatesfaceoverwhelmingstudent loanburdenspost-graduation.Implicationsinclude delayedhomeownership,career choices,andoverallfinancialwell-being.Advocatingforgovernment interventionsto lowerinterest rates,increasegrant-based financing,options,restructurepaymentplans,forgivecertaindebtamountsbasedonqualifyingcriteriaarecritical stepstowardalleviatingthesestudent loanrelatedchallengesfacilitatingabetterfinancialfuturefor borrowersacrossthe country