Decoding the Income-Credit Score Connection: Key Insights for Financial Success
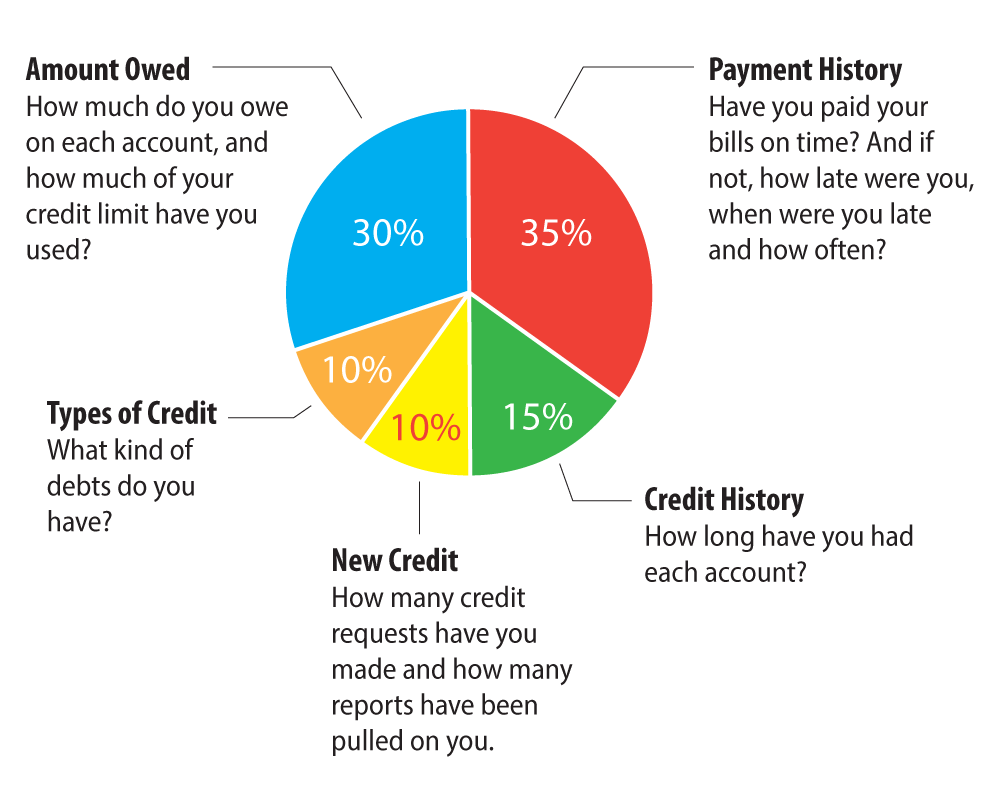
Understanding the relationship between income and credit scores is crucial for managing personal finances effectively. While income does play a role in determining creditworthiness, it is not the sole factor that influences your credit score. Here are 10 key points to consider when examining how income impacts credit scores:
1. **Income Verification**: Lenders may consider your income when evaluating your ability to repay debts. Higher incomes can indicate a greater capacity to handle debt responsibly.
2. **Credit Utilization Ratio**: This ratio compares your total outstanding credit card balances to your total available credit limit. Keeping this ratio low, regardless of income level, can positively impact your credit score.
3. **Payment History**: Your track record of making on-time payments carries significant weight in determining your credit score, regardless of how much you earn.
4. **Credit Mix**: Having a diverse mix of credit accounts, such as mortgages, car loans, and credit cards, can demonstrate responsible financial behavior irrespective of income.
5. **Length of Credit History**: The length of time you’ve been using credit also factors into your score calculation and may have more influence than current income levels.
6. **Debt-to-Income Ratio (DTI)**: This ratio compares your monthly debt payments to your gross monthly income and is often used by lenders to assess risk when extending new lines of credit or loans.
7. **Stable Income Sources**: Consistent and verifiable sources of income can provide reassurance to lenders about your ability to repay debts on time.
8. **Employment History**: A steady employment history demonstrates stability and may positively impact both loan approvals and interest rates offered by lenders.
9. **Ability to Save**: While not directly impacting credit scores, having savings can help prevent financial emergencies that could lead to missed payments affecting one’s score negatively.
10. **Financial Responsibility Matters Most**: Ultimately, what matters most in building good credit is practicing sound financial habits like paying bills on time, keeping debt levels manageable relative to income, and monitoring for errors on one’s report regularly.
By understanding these nuances in the relationship between income and credit scores, individuals can make informed decisions regarding their financial health while working towards achieving better overall financial well-being.