Navigating the Best CD Rates Across the United States: A Comprehensive Guide
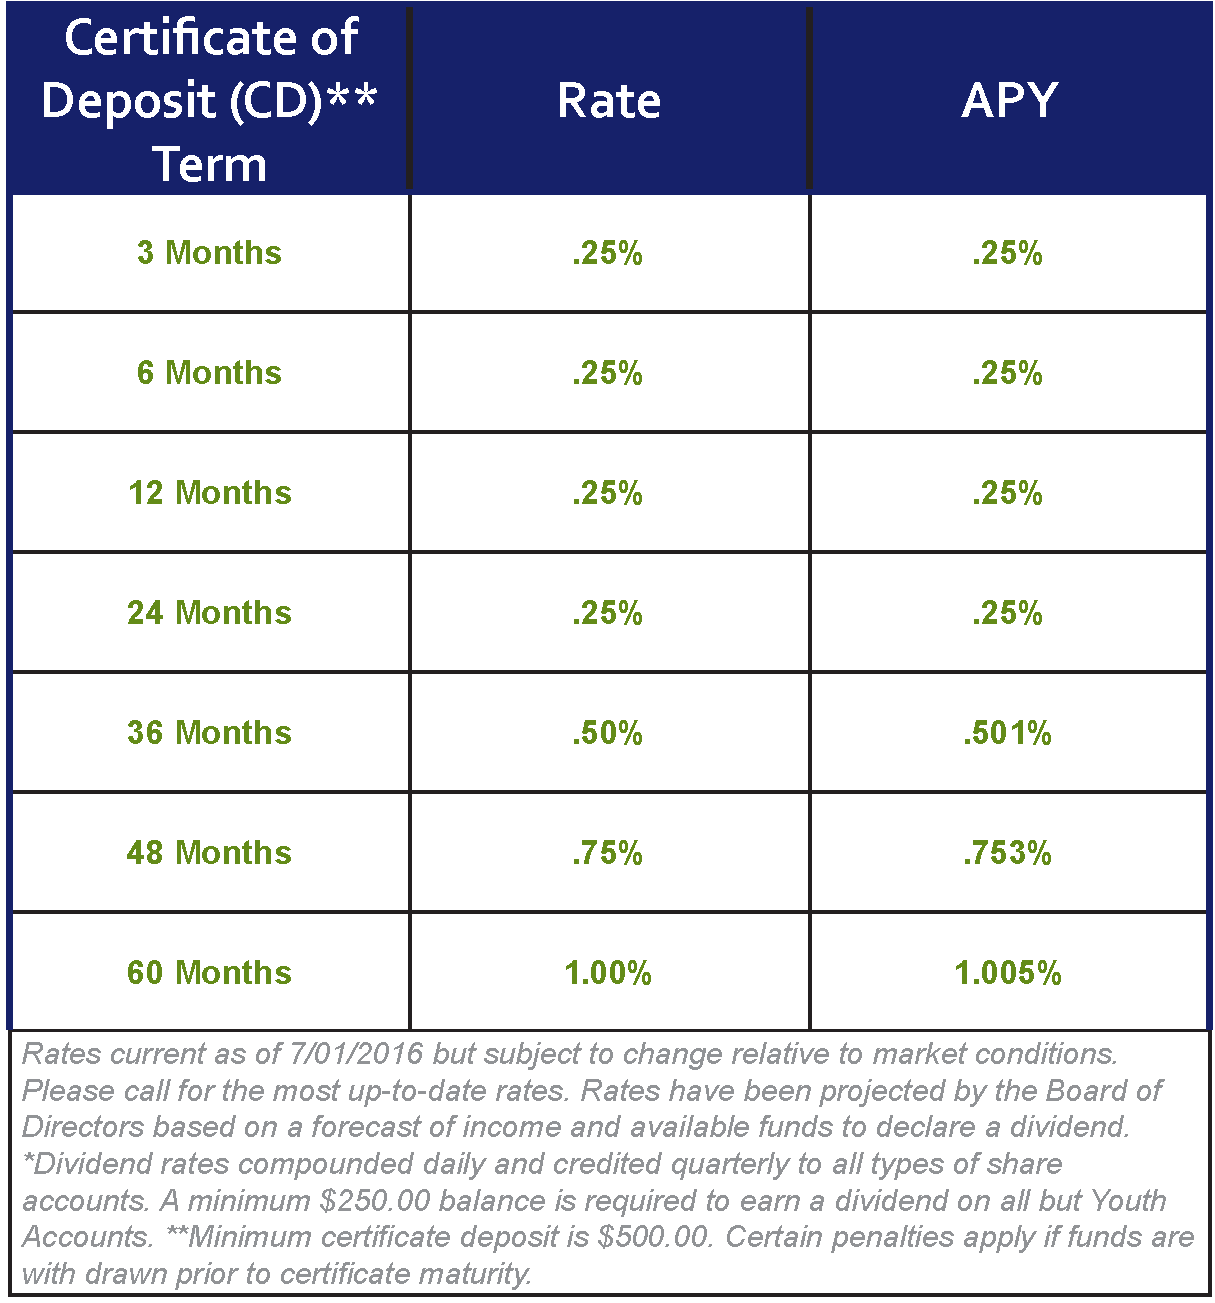
When it comes to finding the best CD rates in the United States, there are several factors to consider before making a decision. Different states may offer varying options and terms for CDs, so it’s essential to do thorough research before opening an account.
In California, some of the top CD options include large national banks like Wells Fargo and Bank of America, as well as local credit unions that may offer competitive rates. Residents can choose from traditional CDs with fixed interest rates or opt for bump-up CDs that allow them to increase their rate if market rates go up.
New York residents have a wide range of CD account options to compare, from online banks like Ally Bank to traditional institutions like Chase. It’s important to look at the terms and conditions carefully, including minimum deposit requirements and early withdrawal penalties.
In Texas, investing in CDs can provide benefits such as guaranteed returns and FDIC insurance on deposits up to $250,000 per account. This low-risk investment option is ideal for individuals looking to diversify their portfolio and earn steady interest income over a set period.
Opening a CD in Florida is a straightforward process that typically involves choosing a bank or credit union, deciding on the term length (such as 6 months, 1 year, or longer), and funding the account with the required minimum deposit amount. Some financial institutions may require proof of identity and address during the application process.
Illinois residents should be aware of common CD terms and conditions such as maturity dates (when funds can be withdrawn penalty-free), automatic renewal policies, and grace periods for making changes to the account before it renews.
Ohio offers competitive CD interest rates at various banking institutions across the state. It’s essential for investors to compare rates from different banks to find the best option that suits their financial goals.
Pennsylvania residents interested in investing in CDs can benefit from secure returns while minimizing risk. By researching different banks’ offerings and comparing interest rates and terms, individuals can make informed decisions about where to open their accounts.
Georgia provides various CD maturity options ranging from short-term CDs (3-6 months) to long-term CDs (5 years or more). Investors should consider their financial goals when choosing between these options based on liquidity needs and interest rate expectations.
North Carolina residents looking into understanding CDs should take note of how they work – essentially locking in funds for a fixed period at an agreed-upon interest rate. Early withdrawals may incur penalties depending on each bank’s policy.
Michigan offers different types of CDs such as jumbo CDs (for larger deposits), IRA CDs (for retirement savings), and liquid or no-penalty CDs which allow early withdrawals without penalties under certain conditions – offering flexibility based on individual needs.
Residents in Virginia need to be aware of potential CD penalties & fees when considering this investment option – these could include early withdrawal penalties if funds are accessed before maturity date or maintenance fees charged by some financial institutions.
Washington residents aiming at building wealth through investments might find investing in CDs beneficial due its security & higher yields compared with regular savings accounts – helping grow capital steadily over time.
Massachusetts investors must weigh risks vs rewards when considering investing in Certificates of Deposit – while offering stable returns & FDIC insurance protection against loss; inflation risks reducing purchasing power gradually over time.
For those looking into utilizing a ladder strategy for diversification with their investments – spreading out money among multiple certificates maturing at different intervals helps maximize returns while maintaining liquidity over time.
Tax implications related with earning interests on Certificates Of Deposits must be considered by investors – these earnings are generally subject federal taxes hence affecting overall gains accrued overtime
International investors seeking global opportunities could explore international Certificate Of Deposit Options available through offshore banking entities providing both growth potential & diversification benefits outside one’s home country
It’s crucial weigh effects inflation has on Certificate Of Deposit Returns – since nominal fixed interests earned might not keep pace rising cost living decreasing real gains eventually
Choosing right bank securing Certificate Of Deposit requires evaluating factors including reputation stability customer service & competitiveness offered interest rates ensuring maximum returns safety invested funds
Incorporating Certificates Of Deposits within one’s financial plan demands careful consideration personal goals risk tolerance timelines enabling optimal use this conservative investment tool maximizing wealth accumulation
This comprehensive guide sheds light various aspects surrounding Certificates Of Deposits aiding readers better understand utilize this popular investment vehicle effectively meeting diverse financial objectives