Exploring Depreciation Methods: From Units of Production to Hybrid Approaches
Depreciation is a key concept in accounting and finance that reflects the decrease in value of an asset over time. There are several methods used to calculate depreciation, each with its own set of rules and considerations. In this article, we will explore various depreciation methods, tax implications, and other important factors related to asset depreciation.
Units of Production Method:
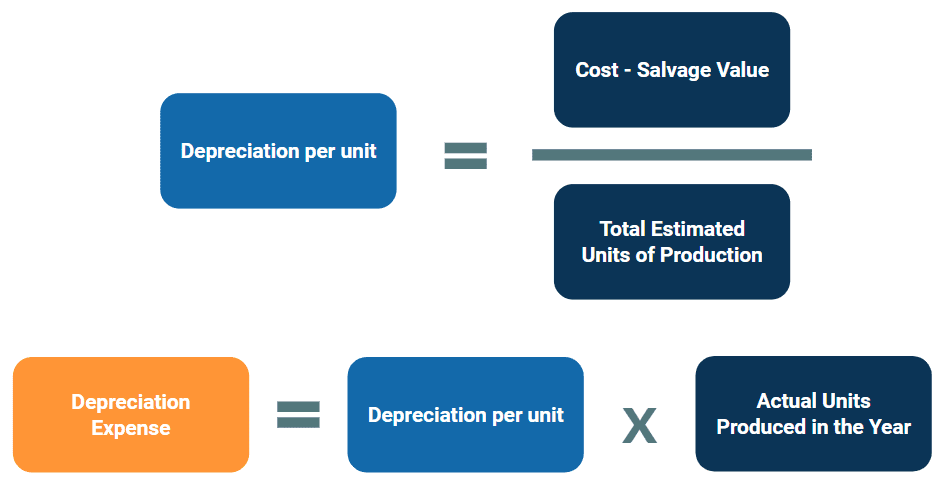
The Units of Production Method is a depreciation method that calculates the depreciation expense based on the actual usage or production output of the asset. This method is useful for assets like machinery or equipment where usage can vary significantly from one period to another. The formula for calculating depreciation under this method is:
Depreciation Expense = (Cost – Salvage Value) x (Units Produced / Total Expected Units)
Component Depreciation:
Component Depreciation involves breaking down a complex asset into its individual components and depreciating each component separately. This method allows for more accurate tracking of each component’s value over time, especially when different components have different useful lives.
Group Depreciation:
Group Depreciation combines multiple similar assets into a single group for depreciation purposes. Instead of depreciating each asset individually, they are grouped together and depreciated as a whole. Group Depreciation simplifies the calculation process for assets that are similar in nature and have similar useful lives.
Composite Depreciation:
Composite Depreciation is similar to Group Depreciation but involves grouping assets together based on their total cost rather than their similarity or useful lives. This method is commonly used when individual assets are small in value compared to the total value of all assets combined.
Tax Depreciation Methods:
For tax purposes, businesses often use accelerated depreciation methods allowed by tax regulations to reduce taxable income in earlier years. Some common tax depreciation methods include MACRS (Modified Accelerated Cost Recovery System), Double Declining Balance Method, Sum-of-the-Years’-Digits Method, and Straight Line Method with bonus depreciation rules also factored in.
Hybrid Depreciation Methods:
Hybrid Depreciation Methods combine elements from different traditional methods to create a customized approach tailored to specific business needs or regulatory requirements. These methods can be more complex but offer flexibility in reflecting the economic reality of asset usage and wear-and-tear.
MACRS Recovery Periods:
MACRS assigns specific recovery periods for different types of assets based on their classification under IRS guidelines. These recovery periods range from 3 to 39 years depending on the type of property being depreciated.
Double Declining Balance Method:
The Double Declining Balance Method is an accelerated depreciation method that charges higher amounts of depreciation expenses during the early years of an asset’s life compared to straight-line depreciation.