Unveiling the Crucial Role of Amortization in Personal Finance and Business
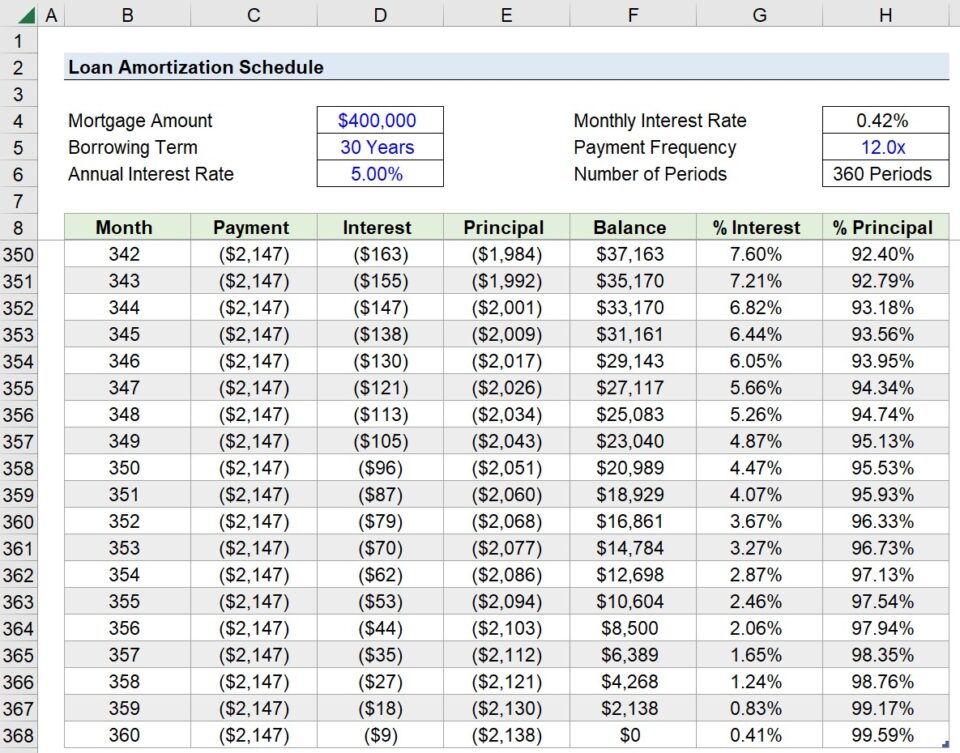
Amortization is a crucial concept in personal finance and business that involves the gradual repayment of a loan or the reduction of an intangible asset’s value over time. Let’s delve into various aspects of amortization to understand its significance in financial management.
Mortgage amortization is the process of paying off a home loan through regular monthly payments. With each payment, a portion goes towards both the principal amount borrowed and the interest charged by the lender. This ensures that by the end of the loan term, typically 15 to 30 years, the entire debt is repaid.
Auto loan amortization functions similarly to mortgage amortization but on a shorter timeline due to the shorter lifespan of vehicles. Student loans also follow an amortization schedule, allowing borrowers to make manageable payments towards their educational expenses over several years.
Credit card debt amortization involves paying down high-interest revolving credit balances systematically to eliminate debts efficiently. Personal loans and business loans are also subject to amortization schedules based on agreed-upon terms between borrowers and lenders.
An amortization schedule outlines each payment’s allocation between principal and interest, helping borrowers track their progress towards debt repayment. Accelerated amortization involves making extra payments towards the principal balance to shorten the loan term and reduce overall interest costs.
Negative amortization can occur when minimum payments on certain types of loans do not cover all accrued interest, leading to an increase rather than a decrease in outstanding balances. It is essential for borrowers to be aware of this risk when considering financing options.
Fixed-rate mortgages offer stable monthly payments throughout the loan term, while adjustable-rate mortgages (ARMs) may have fluctuating rates impacting monthly payment amounts. Balloon payment structures involve lower initial payments with a large final payment due at maturity, requiring careful planning for successful repayment.
Loan refinancing can impact amortization by changing interest rates or extending/reducing the loan term. Borrowers should evaluate potential savings against any associated costs before deciding whether refinancing aligns with their financial goals.
In personal finance, assets like vehicles or equipment can be depreciated through systematic allocation of costs over their useful lives using methods such as straight-line or declining balance depreciation. Intangible assets like patents or trademarks undergo similar treatment known as asset amortization.
Goodwill arising from acquisitions represents an intangible asset subject to periodic impairment testing and potential write-downs if its value decreases over time. Tax implications related to asset depreciation/amortization must be considered for accurate financial reporting and compliance purposes.
Understanding how interest rates influence loan repayments is vital for managing cash flow effectively during periods of economic fluctuation. Higher rates lead to increased borrowing costs, impacting overall debt servicing capabilities for individuals and businesses alike.
By grasping these diverse facets of amortization within personal finance and business contexts, individuals can make informed decisions regarding borrowing strategies, investment opportunities, and long-term financial planning initiatives tailored to their specific needs and objectives.