Mastering Your Money: The Ultimate Guide to Budgeting Success
Creating a Budget:
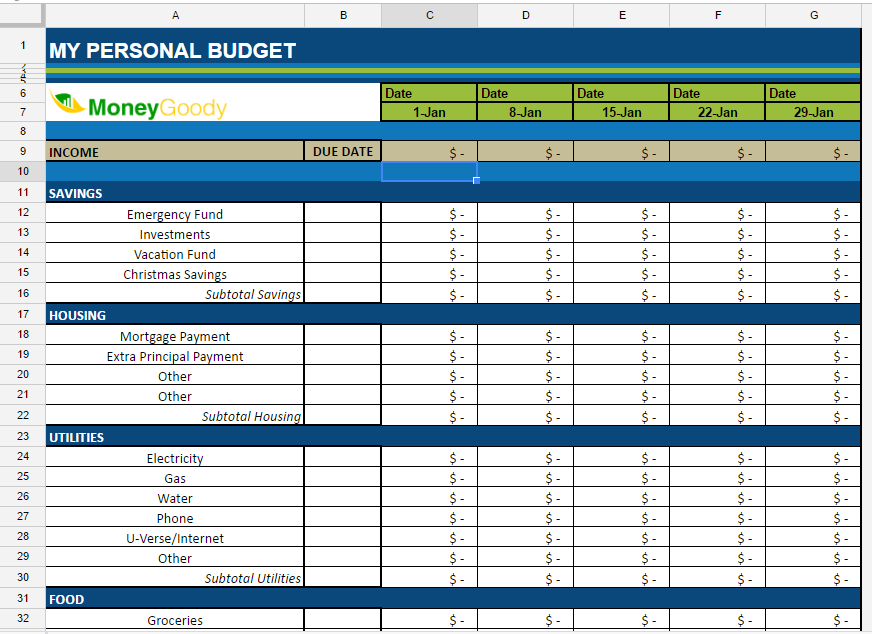
One of the most crucial steps in managing your finances effectively is creating a budget. A budget serves as a roadmap for your financial journey, helping you track your income and expenses to ensure that you are living within your means. To create an effective budget, start by listing all your sources of income, including salaries, bonuses, freelance work, or any other money coming into your household each month.
Next, list all your expenses. This includes fixed expenses like rent or mortgage payments, utilities, insurance premiums, and loan repayments. Additionally, include variable expenses such as groceries, dining out, entertainment, transportation costs, and any other discretionary spending. Be thorough in categorizing your expenses to get a clear picture of where your money is going.
Once you have a comprehensive list of both income and expenses laid out before you, it’s time to compare the two. Ideally, you should aim to allocate a portion of your income towards savings and investments after covering all essential expenses. Adjusting spending habits may be necessary if there is little room for saving or investing in the initial draft of the budget.
Tracking Expenses:
Tracking expenses is key to staying on top of your budgeting goals. There are various methods available for tracking expenses – from traditional pen-and-paper methods to modern digital tools and apps that automate the process for you. By diligently recording every purchase – whether big or small – you can identify patterns in your spending behavior and make informed decisions about where cuts can be made.
Setting Financial Goals:
Financial goals provide direction and purpose to your budgeting efforts. Whether it’s saving for a down payment on a house or planning for retirement early on in life – having specific financial objectives can motivate you to stick to your budget and make wise choices with money management.
Emergency Funds:
Building an emergency fund is essential for weathering unexpected financial storms without resorting to high-interest debt or derailing progress on long-term goals like saving for retirement or buying a home. Experts recommend setting aside three to six months’ worth of living expenses in an easily accessible account as an emergency fund cushion.
Saving for Retirement:
Saving for retirement should start as early as possible due to the power of compounding interest over time. Take advantage of employer-sponsored retirement plans like 401(k)s or IRAs (Individual Retirement Accounts) with tax advantages that can help grow wealth efficiently over the years until retirement age.
Investing Strategies:
Beyond saving in traditional accounts like savings accounts or CDs (Certificates of Deposit), consider exploring investment opportunities such as stocks, bonds,
mutual funds,
real estate,
or exchange-traded funds (ETFs). Diversifying investments across different asset classes can help manage risk while potentially earning higher returns compared
to standard savings vehicles alone.
Debt Management:
Managing debt responsibly plays a significant role in achieving financial wellness.
Start by prioritizing high-interest debts first
and consider consolidating multiple debts into one more manageable payment if feasible.
Make consistent payments above minimum requirements whenever possible
to reduce interest charges
and pay off debts quicker.
Credit Scores:
Your credit score impacts various aspects
of personal finance,
such as loan approvals,
interest rates offered,
or even job applications.
Monitor credit reports regularly from major bureaus Equifax,
Experian,
and TransUnion
for accuracy;
take steps necessary
to improve scores through timely bill payments
Frugal Living Tips:
Adopt frugal living practices such as meal prepping at home instead
of dining out frequently;
utilize public transportation rather than owning multiple cars;
buy second-hand items when feasible;
participate in free community events instead
Budgeting Apps & Tools:
Leverage technology with popular budgeting apps like Mint,
You Need A Budget (YNAB),
or Personal Capital that sync with bank accounts automatically.
These tools offer insights into spending habits,
goal tracking features,
and customizable budgets tailored
Budgeting For Travel:
When planning trips,
budget considerations should include airfare/train tickets;
accommodation costs;
meal budgets; sightseeing activities; souvenirs; travel insurance.
Budgeting For Groceries:
Grocery shopping constitutes a significant portion
of monthly expenditures.
Plan meals ahead based on sales flyers; use coupons effectively; buy generic brands over name brands when quality isn’t compromised
Budgeting For Entertainment:
Entertainment budgets cover movies;
concerts;
dining out experiences;
subscriptions services like Netflix/Hulu/Spotify.
Limit outings by choosing low-cost/free entertainment options occasionally
Budgeting For Housing Costs:
Housing costs encompass rent/mortgage payments; property taxes; homeowners/renters insurance premiums maintenance fees utilities repairs/upgrades Consider downsizing space/home if housing costs dominate monthly budgets
Budgetin…
By incorporating these tips into their daily lives along with utilizing helpful resources such as mobile apps designed specifically around personal finance management individuals will find themselves better equipped To not only reach but exceed their financial goals ensuring lasting stability And peace Of mind In this ever-changing world Of economic uncertainty