Unlocking the Value of Intangible Assets: A Deep Dive into Balance Sheet Components
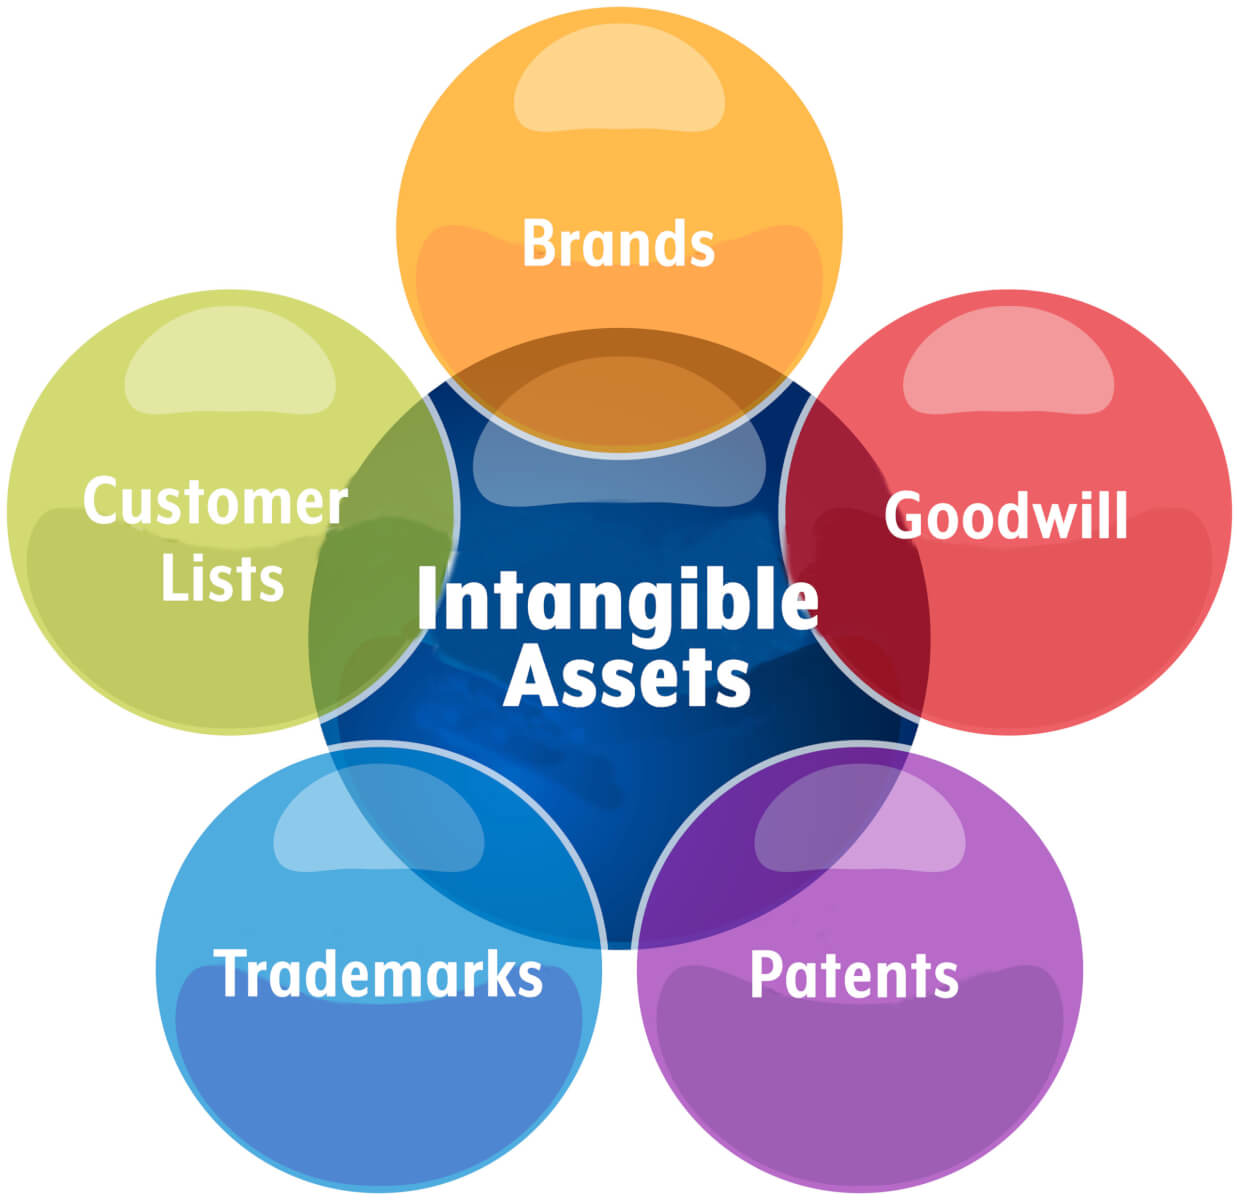
Intangible assets are a crucial component of a company’s balance sheet, representing non-physical assets that lack a physical form but hold significant value. These assets include items such as patents, trademarks, copyrights, goodwill, and brand recognition. Intangible assets are typically categorized into two main types: identifiable and unidentifiable.
Identifiable intangible assets have specific characteristics that can be separated from the entity and sold independently. Examples of identifiable intangible assets include patents, trademarks, customer lists, and software. These assets are recorded at cost on the balance sheet and are amortized over their useful life.
On the other hand, unidentifiable intangible assets do not have a specific lifespan or separable value from the business as a whole. Goodwill is an example of an unidentifiable intangible asset that arises when a company acquires another business for more than the fair market value of its net assets. Goodwill represents the reputation and relationships built by the acquired company over time.
Prepaid expenses represent payments made in advance for goods or services that will be received in the future. Examples of prepaid expenses include rent payments, insurance premiums, and subscription services paid upfront. Prepaid expenses are initially recorded as an asset on the balance sheet and gradually recognized as expenses over time as they are consumed or utilized.
Accumulated depreciation is a contra-asset account that reflects the total depreciation expense recognized on tangible assets since their acquisition. Depreciation is an accounting method used to allocate the cost of tangible assets over their useful lives to match revenue generation with related expenses accurately.
Contingent liabilities are potential obligations that may arise in future events depending on certain outcomes or circumstances. These liabilities are not recorded on the balance sheet but disclosed in footnotes to financial statements due to their uncertain nature. Examples of contingent liabilities include lawsuits, warranties, and environmental claims.
Operating lease obligations represent commitments made by companies to lease equipment or property for a specified period without transferring ownership rights at the end of the lease term. Operating leases allow businesses to use assets without assuming ownership risks associated with ownership.
Capital leases differ from operating leases as they transfer substantial risks and rewards of ownership to lessees during lease terms effectively making them akin to owning an asset without legal title transfer initially reflected on both lessee’s balance sheets depreciating leased items while paying off capital amounts similar finance arrangement via loans often called capital expenditures among companies
Deferred tax assets/liabilities arise when temporary differences exist between taxable income reported on tax returns versus financial statements leading deferred taxes recognizing these discrepancies deferred tax liability if taxable income exceeds pretax financial income & vice versa creating deferred tax asset if pretax income surpasses taxable one
Goodwill refers excess purchase price paid acquired entity solely based expected synergy benefits premium book values net identifiable tangible/intangible recognized part transaction conducted standard current accounting rules considered immaterial impairments occur requiring write-downs carrying values goodwill less impaired valuations
Minority interest occurs parent corporation owns less half voting stock subsidiary consolidated financial statements reporting requirements present minority investors equity stake separate line item within shareholders’ equity section reflecting portion subsidiary attributed outsiders control interests providing clear distinction majority shareholding positions
Cash equivalents highly liquid short-term investments readily convertible cash examples treasury bills money market funds commercial paper easily translates cash balances minimal risk default usually mature three months less available immediate disposal meet urgent funding needs maintaining liquidity levels essential operations avoiding unnecessary liquidity risk exposuresRestricted cash set aside particular purpose restricted usage restrictions ease regulatory compliance debt covenants external agreements reserve security collateral purposes safeguarding stakeholders’ interests ensuring adequate provision ongoing operational necessitiesOther comprehensive income OCI encompasses gains losses affecting stockholders’ equity traditional profit/loss fluctuations arising transactions adjustments derive prior period changes pension plan obligations currency translation adjustments unrealized securities investment gains/losses distinguished net earnings tracking comprehensive performance indicatorsPension liabilities obligations employers provide retirement benefits employees service rendered estimated costs retirement plans fund adequately meeting anticipated obligations contributing employees covering shortfall contribution rates fluctuate economic conditions impacting solvency ratiosAsset impairment declines recoverable amount exceeding carrying numerical difference indicates impairment loss writing down values matching lower realizable worth adjusting books realistic assessments reduce inflated valuations reflecting true economic substanceDebt covenants agreements lenders borrowers outlining terms conditions lending arrangements ensure timely repayments stipulating restrictive clauses prevent excessive leveraging actions protect lender interests maintain borrower credibility trustworthiness managing debt profiles prudentlyOff-balance sheet financing entities engage activities recording disclosures expose full extent contractual obligations hidden undisclosed nature representing potential risks defaults insolvency uncertainties impacting overall stability transparency corporate governance practicesFair value adjustments reflect changes valuation techniques reassessing market prices securities investments periodically aligning current fair values reporting standards alter perceptions accuracy reliability information presented accurate representation underlying economic realitiesEquity method investments equities held corporations significant influence decision-making processes exerted acquiring shares cases resulting joint ventures strategic alliances recognizing proportional earnings holdings contributed investing entities consolidating group accountsDerivative financial instruments contracts derive inherent values underlying variables futures options swaps forwards commodities currencies interest rates hedging speculative trading purposes complex sophisticated products requiring specialized knowledge expertise manage effectively mitigate associated risksStock options warrants entitle holders acquire underlying stocks predetermined exercise prices granting rights purchasing shares specified periods acting incentives retaining key personnel rewarding performance enhancing shareholder relations aligning interests parties concerned mutual prosperity growth opportunities