Unveiling the Intricacies of Amortization: From Accelerated to Negative, Exploring Finance’s Key Tool
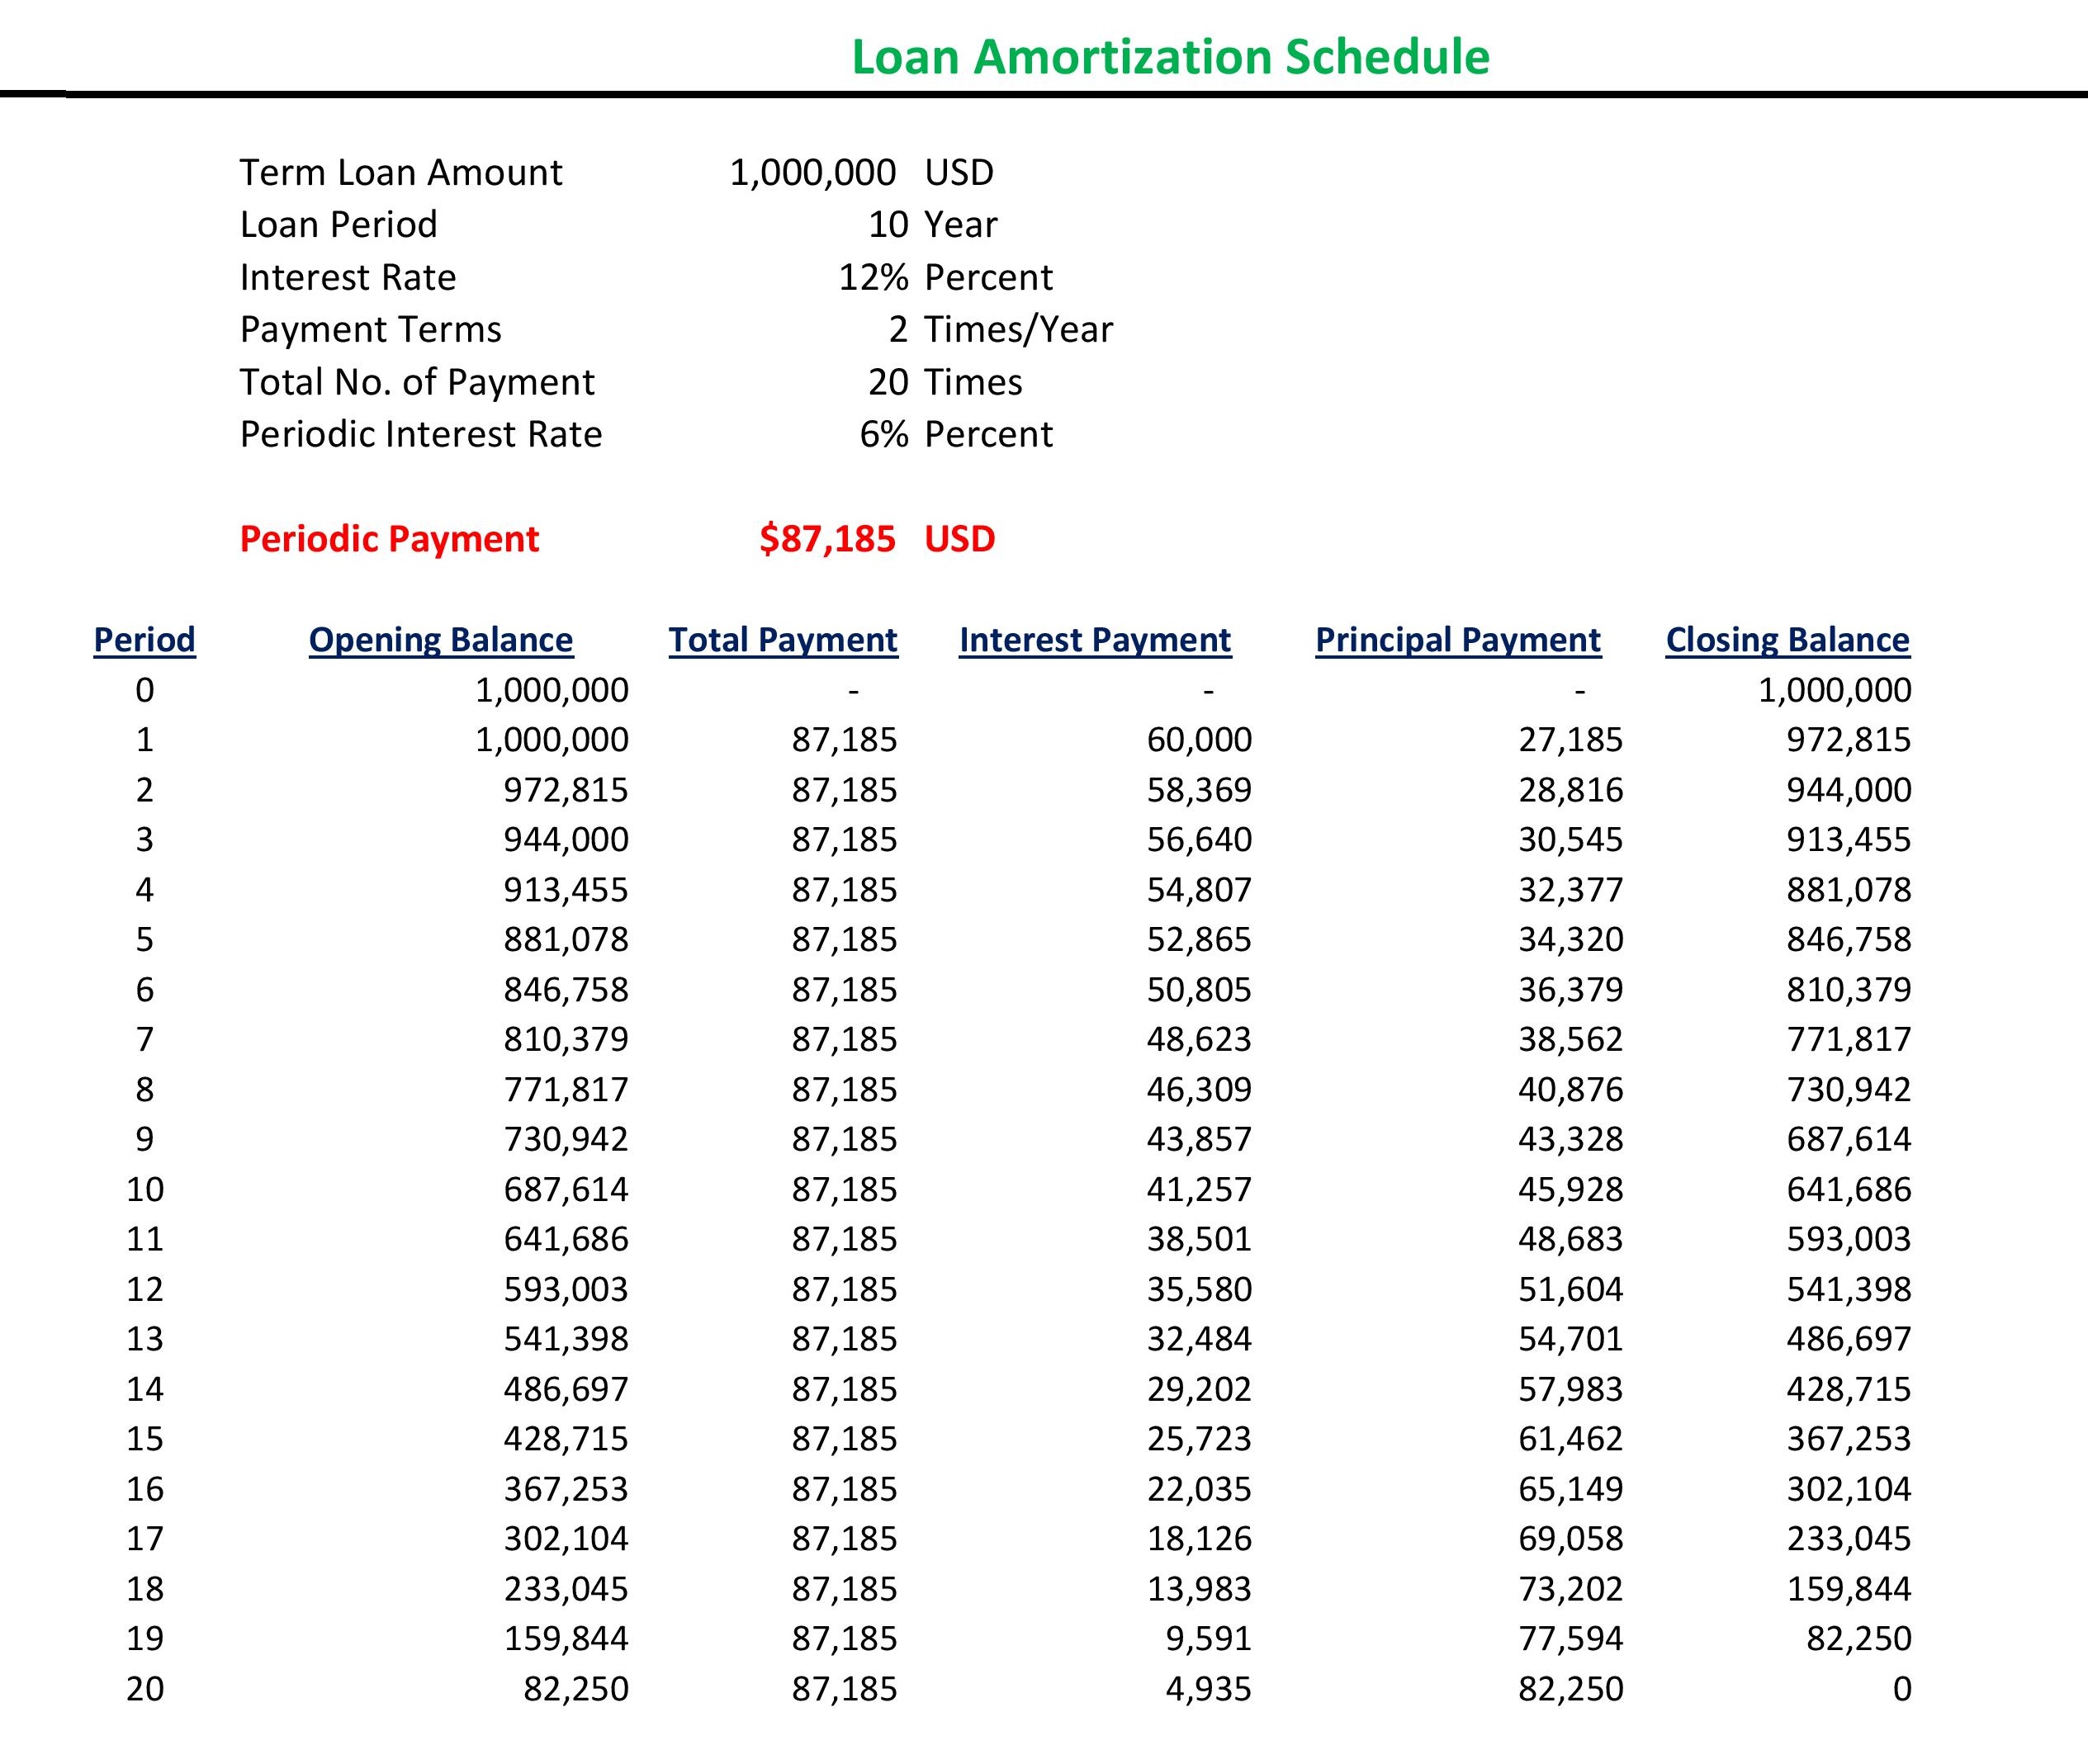
In the world of finance and accounting, amortization plays a crucial role in spreading out the cost of an intangible asset over its useful life. Let’s delve into various aspects of amortization to better understand its significance and applications.
Accelerated amortization involves paying off a loan or debt quicker than the set schedule. This can help save on interest costs and shorten the overall repayment period, benefiting borrowers in the long run.
An amortization schedule is a table that outlines periodic loan payments, including both principal and interest amounts. It provides a clear overview of how each payment contributes to reducing the outstanding balance over time.
Negative amortization occurs when a borrower’s monthly payments are insufficient to cover the interest due, leading to an increase in the loan balance rather than its decrease. This can result in higher future payments or even default if not managed effectively.
Straight-line amortization evenly spreads out the cost of an asset over its useful life, making it simpler to calculate and track depreciation expenses for accounting purposes.
The effective interest method calculates interest expense based on the carrying amount of a liability at the beginning of each period. This results in a more accurate representation of interest costs over time compared to simple methods like straight-line amortization.
The declining balance method applies a fixed percentage rate to reduce the book value of an asset each period. This leads to higher depreciation expenses early on, reflecting greater wear and tear in earlier years.
Loan amortization involves paying off a loan through regular installments that cover both principal and interest portions. Over time, more of each payment goes towards reducing the principal amount owed.
Mortgage amortization follows a similar concept as loan amortization but specifically refers to repaying home loans through scheduled payments until fully paid off or refinanced.
An amortization calculator helps individuals estimate their loan repayments by factoring in variables such as loan amount, interest rate, term length, and payment frequency.
Balloon payment amortization involves making lower initial payments followed by one large final payment at the end of the term. This can be risky for some borrowers who may struggle with sudden lump-sum repayments.
Fixed-rate mortgage amortizations feature stable monthly payments throughout the loan term, providing predictability for homeowners budgeting their expenses.
Adjustable-rate mortgage (ARM) amortizations have fluctuating interest rates that can impact monthly payments periodically based on market conditions. Borrowers should be prepared for potential increases in their repayment amounts over time with ARMs.
Prepaid expenses are costs paid in advance but gradually expensed over multiple accounting periods through systematic allocation known as prepaid expenses’ amortization
Depreciation vs Amortisation: Both methods allocate costs over time but depreciation is typically used for tangible assets like equipment or buildings while amortisation is primarily applied to intangible assets like patents or trademarks
Amortising loans require regular paydowns where both principal & interests are covered whereas Interest-only loans only require covering interests till maturity date
Capitalised Interest during construction phase allows companies delay recognition until project completion aiding financial statement accuracy
Loan modification & re-amoritisation help restructure terms offering relief easing burden on struggling borrows ensuring timely repayments
Deferred financing cost amoritistion eases immediate impact allowing gradual recognition aiding financial health
Software subscription revenue recognition via amotisation ensures revenue earned matches service provided offering fair presentation benefits users
Amortized cost accounting method entails monitoring securities at acquisition price adjusting downwards post impairment ensuring true worth reflected
There you have it – from accelerated to negative amoritzation techniques there is much depth within this topic influencing finances across various sectors!