Unraveling the Intrigues of 401(k) Plans: Key Aspects and Quirky Facts
Welcome to the world of 401(k) plans – a financial tool that can help you save for retirement while potentially lowering your tax bill. Let’s dive into some key aspects and quirky facts about 401(k) plans.
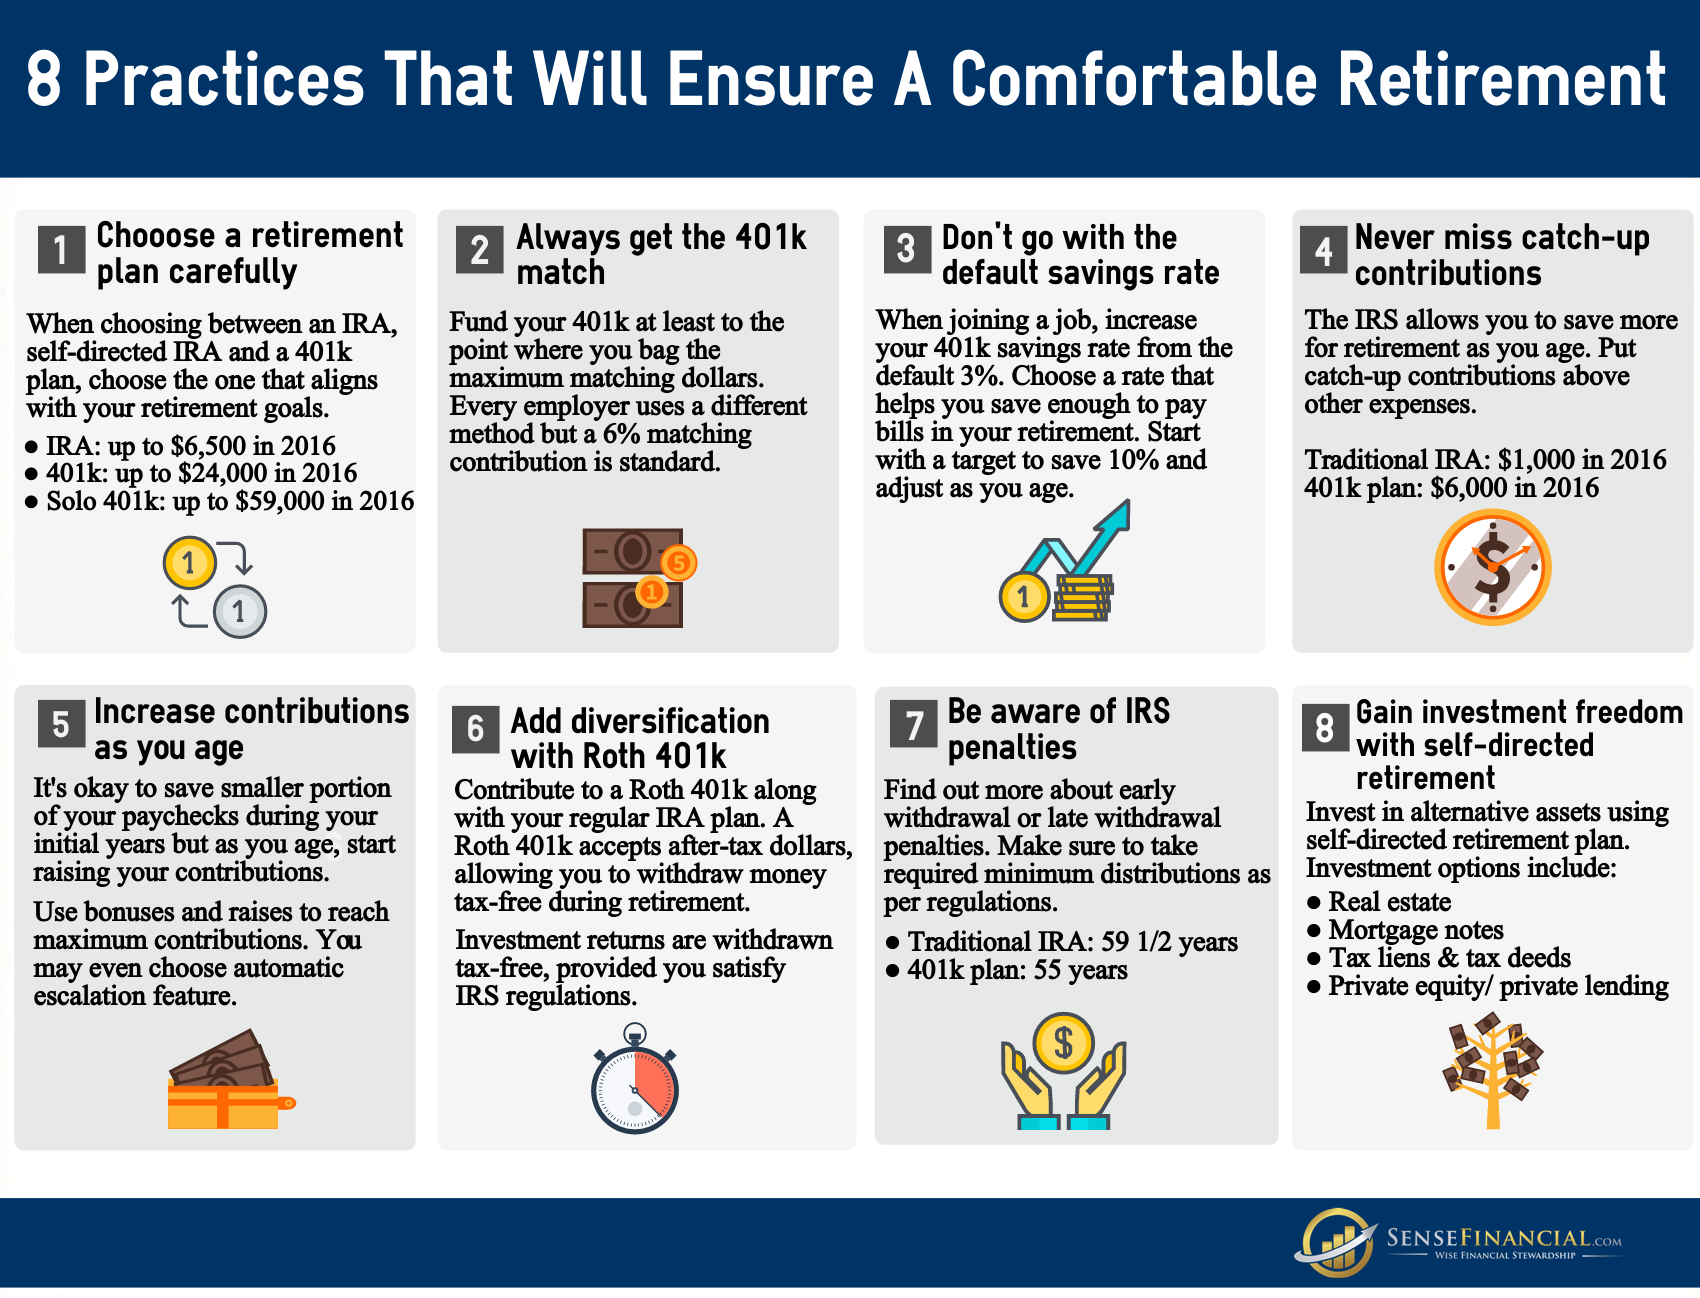
First up, Roth 401(k) vs Traditional 401(k). The main difference between these two lies in how they are taxed. With a Traditional 401(k), contributions are made pre-tax, reducing your taxable income for the year. In contrast, Roth 401(k) contributions are made after taxes but withdrawals in retirement are tax-free.
If you’re looking for more control over your investments, self-directed 401(k) plans might be right up your alley. These plans allow you to invest in alternative assets like real estate or precious metals within your retirement account.
For solo entrepreneurs or freelancers, a Solo 401(k) can be a great option. It allows you to contribute as both an employer and employee, potentially maximizing your savings potential.
Employer matching contributions strategies can significantly boost your retirement savings. Make sure to take full advantage of any match offered by your employer – it’s essentially free money!
In-service withdrawals and distributions allow you to access funds from your 401(k) before retirement age under certain circumstances but may come with penalties or restrictions.
Non-discrimination testing ensures that highly compensated employees don’t disproportionately benefit from a company’s 401(k) plan compared to other employees.
Changing jobs? Don’t forget about your old employer’s 401(k). You can roll it over into an IRA or new employer’s plan without facing immediate taxes or penalties.
Thinking of taking out a loan from your 401(k)? Proceed with caution and only do so if absolutely necessary since unpaid loans could trigger early withdrawal penalties.
Early withdrawal penalties generally apply if you withdraw funds from your 401(k) before age 59½ unless you qualify for one of the exceptions like disability or specific hardships.
Tax implications of distributions in retirement vary based on whether they come from traditional or Roth accounts. Understanding these implications can help you better plan for taxes in retirement.
Rolling over a 401 (k) into an IRA gives you more investment options and control over fees than leaving it with an old employer’s plan which may have limited choices and higher costs.
Catch-up contributions allow individuals aged over fifty to contribute additional amounts beyond the standard limits each year towards their retirement savings.
Vesting schedules determine when employer-matched contributions become fully owned by employees; understanding vesting rules is crucial when changing jobs.
Investment options within a
Rebalancing periodically helps maintain the desired risk level within one’s portfolio; reviewing asset allocation regularly is key especially during market fluctuations.
Fees associated with managing one’s account should not be overlooked; comparing fee structures among different providers could save money in the long run.
Beneficiary designations are essential components of estate planning; keeping them updated ensures assets go where intended upon passing away.
Utilizing financial advisors could provide valuable guidance on making informed decisions regarding optimizing one’s account for future needs.
As we navigate through these nuances together, remember that preparing for retirement doesn’t have to be boring – let’s make saving fun!