Mastering Personal Finance: Key Concepts for Financial Success
Emergency funds are a crucial aspect of financial planning that often gets overlooked until it’s too late. Having an emergency fund in place can provide a cushion during unexpected life events such as job loss, medical emergencies, or home repairs. Financial experts recommend setting aside at least three to six months’ worth of living expenses in a separate savings account for emergencies.
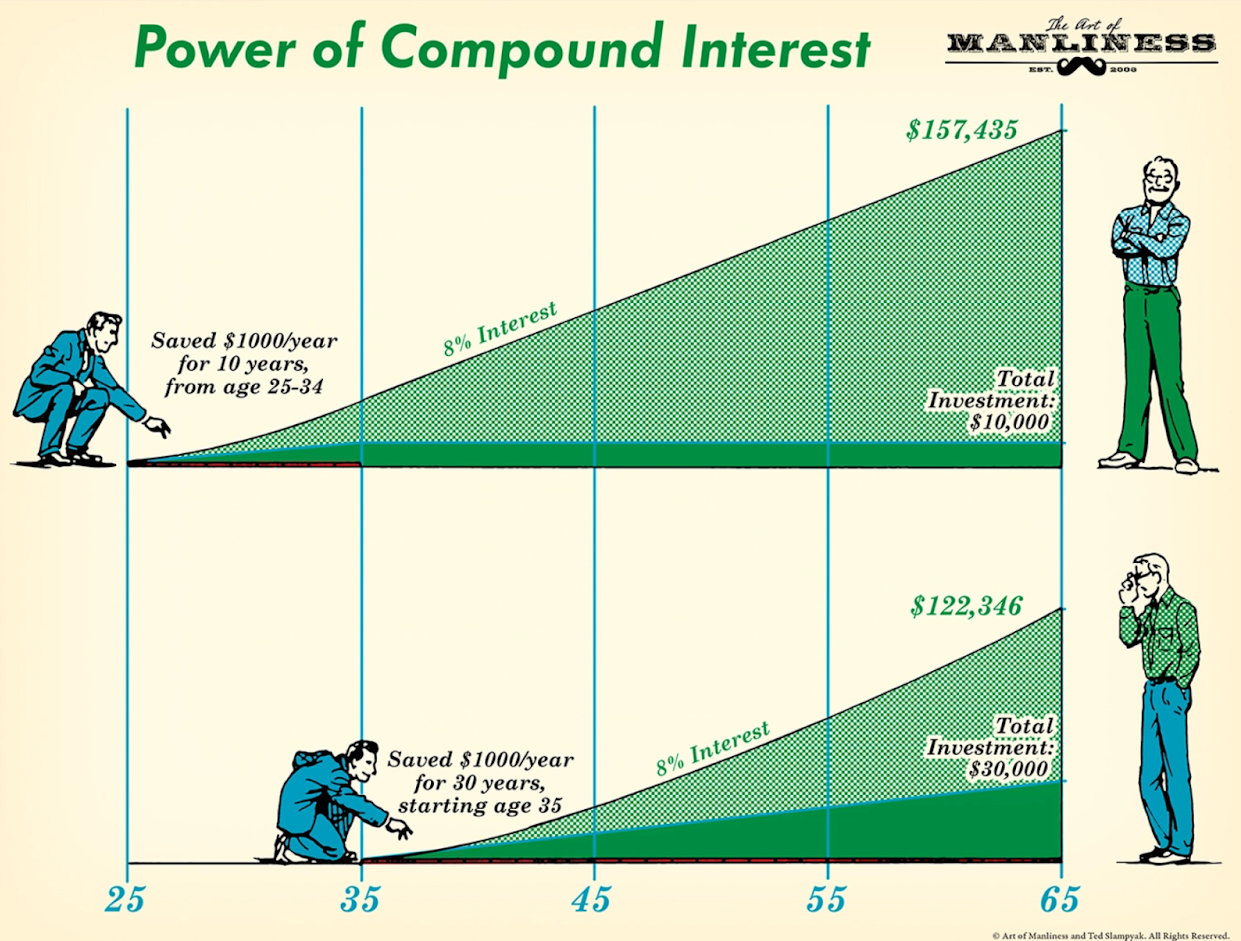
Understanding compound interest is essential when it comes to building wealth over time. Compound interest allows your money to grow exponentially by earning interest on both the initial principal and the accumulated interest. The earlier you start investing, the more time your money has to compound and grow.
Exploring different types of investment accounts can help you maximize your returns while minimizing risks. Common investment accounts include Individual Retirement Accounts (IRAs), 401(k) plans, brokerage accounts, and health savings accounts (HSAs). Each type of account has its own tax advantages and contribution limits, so it’s important to choose the right mix based on your financial goals.
Inflation can erode the purchasing power of your savings over time. It’s important to consider inflation when setting financial goals and choosing investment strategies that outpace inflation rates. Investing in assets like stocks, real estate, or Treasury Inflation-Protected Securities (TIPS) can help hedge against inflation risk.
Diversifying your portfolio across different asset classes can help reduce overall risk and increase potential returns. By spreading investments across stocks, bonds, real estate, and alternative assets, you can minimize the impact of market fluctuations on your portfolio.
Tax implications play a significant role in determining which investment strategies are most suitable for your financial situation. Traditional IRAs offer tax-deferred growth but require distributions to be taxed upon withdrawal, while Roth IRAs allow tax-free withdrawals in retirement.
Setting realistic financial goals is key to achieving long-term success. Whether it’s saving for retirement, buying a home, or starting a business, having clear objectives helps motivate disciplined saving and investing habits.
Robo-advisors are automated investment platforms that use algorithms to create diversified portfolios based on individual risk tolerance and financial goals. While robo-advisors offer low fees and hassle-free investing solutions, they may lack personalized advice compared to traditional human advisors.
Socially responsible investing focuses on generating positive social or environmental impact alongside financial returns. Investors can align their values with their investment choices by supporting companies with sustainable practices or ethical standards.
Dividend investing involves purchasing shares of companies that pay dividends regularly. Reinvesting dividends can accelerate wealth accumulation through compounding returns over time.
Understanding spending habits is crucial for maintaining healthy finances. Behavioral economics suggests that emotions often drive spending decisions more than rational thinking does; being mindful about impulse purchases and budgeting accordingly can help curb unnecessary expenses.
Credit scores reflect individuals’ creditworthiness based on their borrowing history and repayment behavior. Monitoring credit reports regularly helps identify errors or fraudulent activities that could negatively impact credit scores if left unchecked.
Negotiating better rates with lenders requires research and preparation before approaching them with requests for lower interest rates or fees on loans or credit cards; demonstrating good payment history may strengthen negotiation positions.
Risk tolerance refers to an individual’s comfort level with market volatility; assessing one’s risk tolerance helps determine appropriate asset allocation strategies aligned with long-term financial objectives.
Creating alternative income streams beyond traditional employment offers additional sources of cash flow; rental properties,
side gigs freelancing projects,
or passive income from investments diversify revenue streams
and provide greater stability against economic uncertainties.
Budgeting strategies tailored for irregular income earners involve forecasting monthly expenses,
prioritizing essential payments
and setting aside variable income amounts into emergency funds;
tracking spending patterns helps manage cash flows effectively despite fluctuating earnings.
Lifestyle inflation occurs when rising incomes lead to higher discretionary spending levels;
resisting lifestyle inflation preserves long-term financial health
by directing additional earnings towards savings,
investment opportunities
or debt repayment instead.
In conclusion,
navigating personal finance requires understanding various concepts such as emergency funds,
compound interest,
investment accounts,
inflation impacts,
diversification benefits
tax implications goal-setting strategies;
evaluating robo-advisor pros cons socially responsible investing options dividend maximization approaches psychological spending habits credit reporting negotiations risk-tolerance assessment alternate income sources budgeting techniques lifestyle-inflation dangers enhances overall fiscal literacy decision-making abilities strategic wealth management skills career advancement prospects ultimately leading improved quality life future generations benefit well-informed comprehensive approach managing finances wisely securely today tomorrow.