Navigating the Maze of Individual Retirement Accounts: Unconventional Options and Strategies for a Secure Retirement
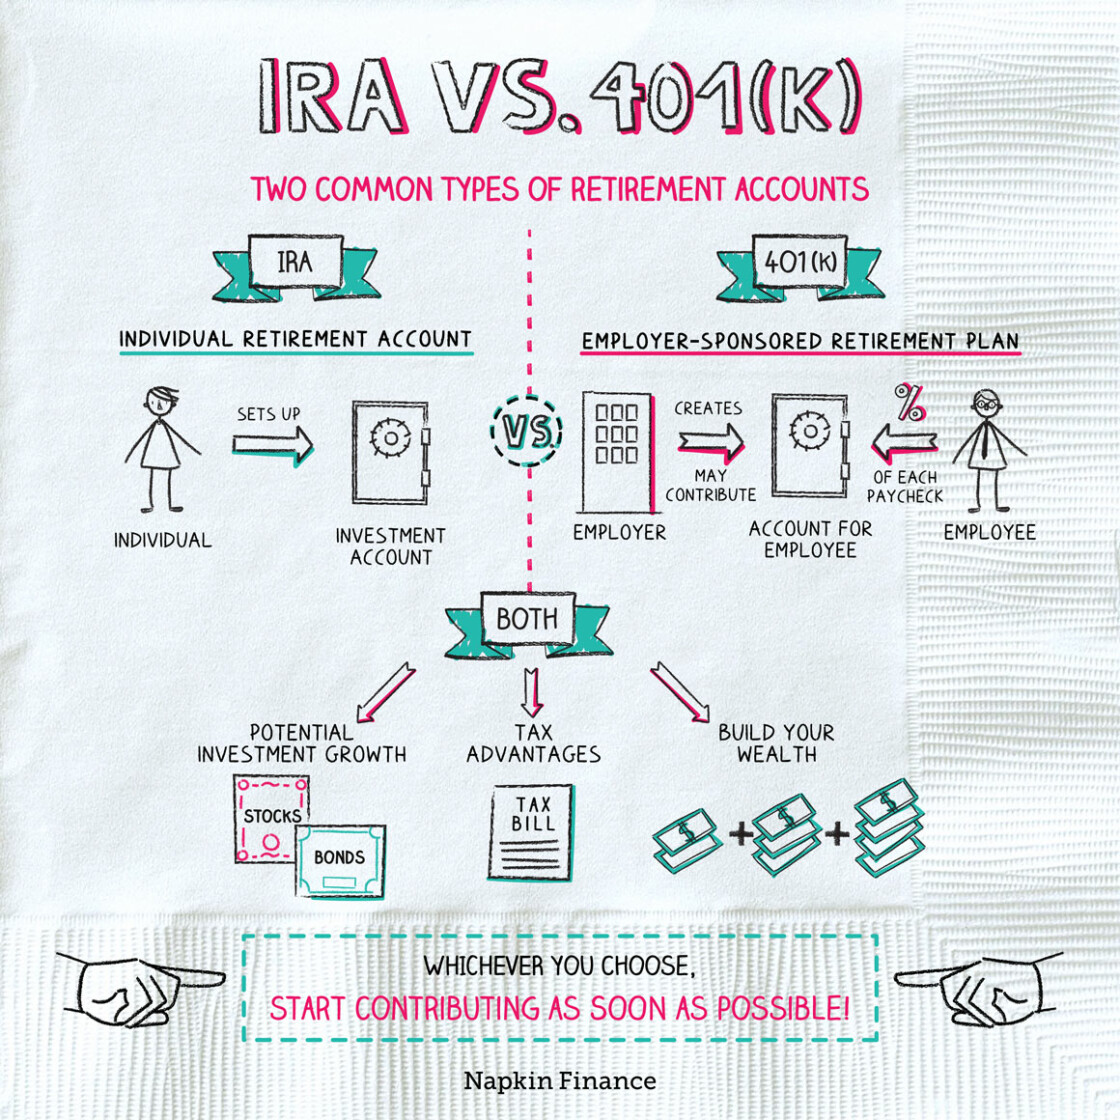
When it comes to planning for retirement, individual retirement accounts (IRAs) offer a variety of options to help individuals save and grow their wealth over time. Understanding the different types of IRAs and their unique features is crucial in making informed decisions about your retirement savings strategy. In this comprehensive critique, we will delve into various types of IRAs, including some unconventional options, tax implications, investment strategies, and considerations for early withdrawals.
1. **Backdoor Roth IRA**
The Backdoor Roth IRA is a strategy used by high-income earners who are not eligible to contribute directly to a Roth IRA due to income limits. By making nondeductible contributions to a traditional IRA and then converting it to a Roth IRA, individuals can take advantage of the benefits of tax-free growth and withdrawals in retirement.
2. **Spousal IRA**
A Spousal IRA allows non-working spouses to contribute to an IRA based on the working spouse’s income. This can be beneficial for couples looking to maximize their retirement savings as both partners can build up their own nest egg through separate accounts.
3. **Stretch IRA**
A Stretch IRA was once a popular estate planning tool that allowed beneficiaries to stretch out distributions over their lifetime after inheriting an IRA. However, recent legislation has limited the use of stretch IRAs for many beneficiaries.
4. **Self-Directed IRA**
Self-Directed IRAs enable account holders to invest in alternative assets such as real estate, precious metals, cryptocurrencies, and more beyond traditional stocks and bonds. While offering greater investment flexibility, self-directed IRAs come with added complexity and risk that investors must carefully navigate.
5. **Inherited IRA**
Inherited IRAs are created when someone inherits an account from a deceased owner. Rules governing Inherited IRAs vary depending on the relationship between the beneficiary and the original account holder but generally require specific distribution schedules based on the beneficiary’s age.
6. **SIMPLE & SEP IRAs**
SIMPLE (Savings Incentive Match Plan for Employees) and SEP (Simplified Employee Pension) IRAs are designed for small businesses or self-employed individuals seeking easy-to-administer retirement plans with potential tax advantages compared to traditional 401(k)s.
7. **Roth 401(k) vs. Roth IRA**
Both Roth 401(k)s offered by employers and Roth IRAs have similar tax treatment – contributions are made after-tax with tax-free withdrawals in retirement – yet they differ in contribution limits, employer matches (for 401(k)s), investment options available, fees structure among other factors which could influence one’s choice between them.
8-12: *Mega Backdoor Roth*, *Non-deductible Traditional Contributions*, *Solo 401(k)*: These provide additional avenues for high-income earners or self-employed individuals like freelancers or contractors looking at maximizing their contributions through advanced strategies tailored towards specific circumstances.
13: **Health Savings Account (HSA) as an Investment Vehicle**
Using HSAs can serve dual purposes – helping cover current medical expenses while also acting as supplemental retirement savings tool due its triple-tax advantages if utilized properly.
14: **Qualified Charitable Distributions**
QCDs allow individuals aged 70½ or older who don’t need all their required minimum distributions from traditional IRAS or qualified plans give up $100k annually directly from these accounts without having it included in taxable income.
15-16: *Gold/Precious Metals* & *Real Estate Investments within an IRS*: Investing in gold/precious metals or real estate via an IRS offers diversification but comes with complexities like custodial fees & adherence regulations given restrictions placed on permissible investments
17-18: Cryptocurrency Investments & Unconventional Assets
Including cryptocurrencies within an IRS adds volatility risks along regulatory concerns; unconventional assets bring opportunity diversification but demand thorough understanding around rules set forth by IRS
19-20: Early Withdrawals Impacts & Conversion Tax Implications
Withdrawing funds prematurely may attract penalties while converting traditional into Roths involves weighing current versus future taxes owed
Understanding these varied types of Individual Retirement Accounts along with associated nuances expands one’s arsenal when strategizing long-term financial goals ensuring alignment with individual circumstances whilst optimizing returns within defined boundaries set forth by laws guiding these vehicles meant towards securing one’s golden years comfortably.