Navigating Early Withdrawal Penalties: What You Need to Know
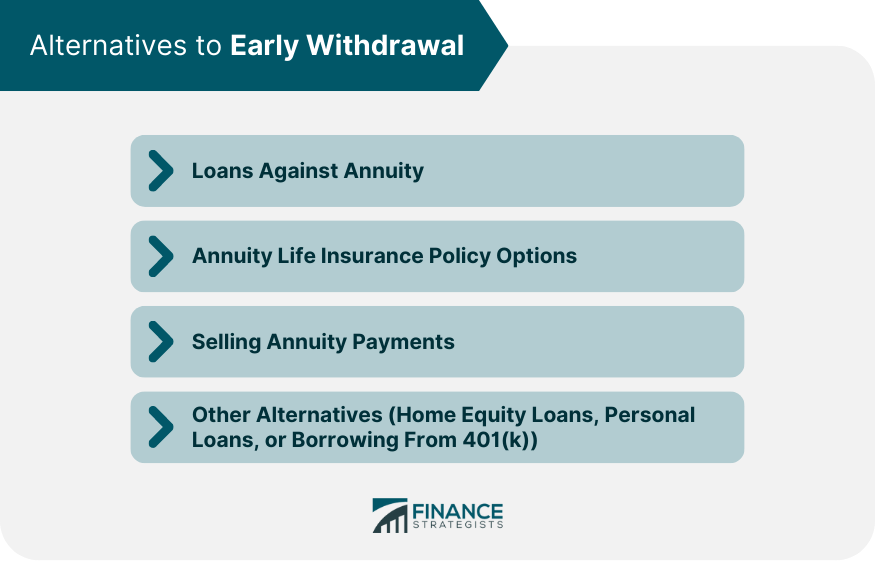
Early withdrawal penalties are a common feature in many financial products, such as retirement accounts, certificates of deposit (CDs), and certain investment accounts. These penalties are put in place by financial institutions to discourage account holders from withdrawing funds before a specified period or maturity date.
One of the most well-known examples of early withdrawal penalties is seen in retirement accounts like 401(k)s and IRAs. In these accounts, individuals typically face a penalty if they withdraw funds before reaching the age of 59 ½. The penalty for early withdrawal from retirement accounts is usually around 10% of the withdrawn amount on top of any applicable taxes.
The purpose of imposing an early withdrawal penalty on retirement accounts is to incentivize individuals to save for their future and not tap into those funds prematurely. By penalizing early withdrawals, financial institutions aim to protect individuals’ long-term financial security and encourage responsible saving habits.
Certificates of deposit (CDs) are another type of financial product where early withdrawal penalties come into play. CDs are time deposits that require account holders to keep their money locked away for a fixed term, typically ranging from three months to five years. If an individual withdraws funds from a CD before its maturity date, they will likely incur an early withdrawal penalty.
The specific terms and conditions surrounding early withdrawal penalties for CDs can vary depending on the issuing institution and the length of the CD term. Generally, the penalty for withdrawing funds from a CD prematurely is calculated as a percentage of the interest earned or sometimes as a flat fee.
It’s crucial for individuals considering opening a CD to carefully review and understand the terms related to early withdrawals before committing their funds. Being aware of potential penalties can help account holders make informed decisions about when it may be appropriate to access their money without facing significant financial consequences.
In addition to retirement accounts and CDs, certain investment vehicles like annuities may also impose early withdrawal penalties under specific circumstances. Annuities are insurance products that provide regular payments over time either immediately or at some point in the future.
If an individual decides to withdraw funds from an annuity before reaching a certain age or within a specified timeframe known as the surrender period, they may be subject to an early withdrawal penalty imposed by the insurance company issuing the annuity. This penalty could result in forfeiting part of the principal amount invested or facing charges based on surrender fees outlined in the contract terms.
Understanding how early withdrawal penalties work across various types of financial products is essential for individuals looking to manage their money effectively while avoiding unnecessary fees or setbacks. By familiarizing themselves with these penalties upfront, account holders can make more strategic decisions about when it’s appropriate to access their funds without triggering additional costs.