Closing the Retirement Savings Gap: Tackling Racial Disparities in Wealth Building
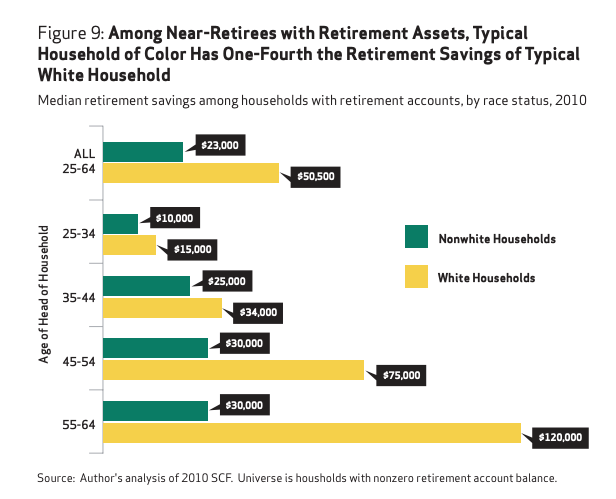
Racial disparities in retirement savings have long been a critical issue that affects the financial security and well-being of individuals from marginalized communities. While retirement savings should ideally serve as a safety net for all Americans in their later years, the reality is that people of color often face significant obstacles in building adequate nest eggs compared to their white counterparts. This disparity is rooted in historical and systemic factors that have perpetuated wealth inequality along racial lines.
One of the key reasons behind the racial disparities in retirement savings is the persistent wage gap between different racial groups. Studies consistently show that Black and Hispanic workers earn less than their White counterparts for similar work, leading to lower disposable income available for saving and investing. The impact of this wage gap is further exacerbated by occupational segregation, where people of color are more likely to be concentrated in lower-paying jobs with limited access to employer-sponsored retirement plans such as 401(k)s.
Moreover, access to workplace retirement benefits also varies significantly by race. According to data from the Economic Policy Institute, only 54% of Black workers and 38% of Hispanic workers have access to an employer-sponsored retirement plan, compared to 62% of White workers. This lack of access not only limits the ability of people of color to save for retirement but also deprives them of valuable employer contributions and tax advantages that come with such plans.
Another factor contributing to the racial disparities in retirement savings is homeownership rates. Homeownership has traditionally been a primary source of wealth accumulation for American families, allowing them to build equity over time through mortgage payments and property appreciation. However, historical discriminatory practices such as redlining have systematically excluded people of color from accessing affordable housing options and accumulating home equity at the same rate as White households.
As a result, many Black and Hispanic households have lower homeownership rates compared to White households, which directly impacts their ability to build wealth for retirement through property ownership. Without home equity as a cushion or asset they can tap into during their later years, individuals from marginalized communities may find themselves financially vulnerable when they retire.
In addition to these structural barriers, cultural factors also play a role in shaping attitudes towards saving and investing among different racial groups. For example, studies suggest that mistrust towards financial institutions stemming from historical exploitation and discrimination can deter some individuals from seeking out professional financial advice or engaging with traditional banking systems.
Furthermore, language barriers or lack of culturally competent financial education programs may hinder access to information about retirement planning options or prevent individuals from fully understanding complex investment products like mutual funds or individual retirement accounts (IRAs). These challenges can contribute to lower levels of financial literacy among certain racial groups, impacting their ability to make informed decisions about saving for retirement effectively.
To address these entrenched disparities in retirement savings along racial lines, policymakers must take proactive steps towards creating more equitable opportunities for all Americans regardless of race or ethnicity. One potential solution could involve expanding access to workplace retirement plans by incentivizing employers – especially those with large minority workforces –to offer automatic enrollment features or matching contributions that encourage employees’ participation.
Additionally, efforts should be made at both the federal and state levels…