Navigating Inflation: Real vs. Nominal Interest Rates Explained
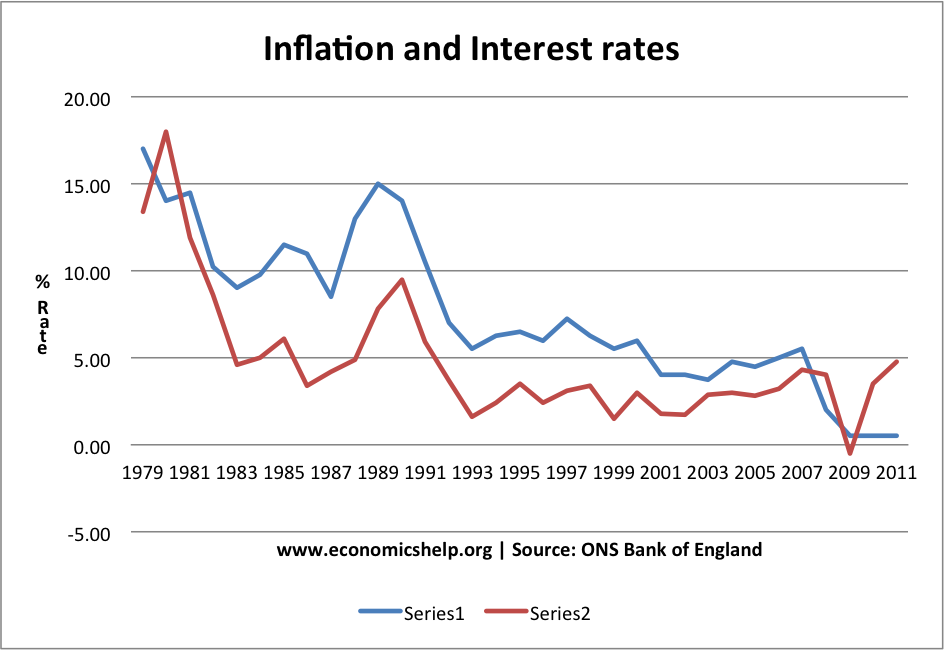
Inflation is a significant factor that can impact the economy, financial markets, and personal finances. It refers to the increase in prices of goods and services over time, leading to a decrease in the purchasing power of money. When inflation occurs, it affects interest rates as well, particularly real and nominal interest rates. Understanding the difference between these two types of interest rates is crucial for individuals looking to make informed financial decisions during inflationary periods.
Nominal Interest Rates:
Nominal interest rates are straightforward and easy to understand. They represent the actual rate at which your investment grows or your debt accumulates without taking into account the impact of inflation. For example, if you have a savings account with an annual interest rate of 5%, that is your nominal interest rate. Similarly, if you borrow money at an annual percentage rate (APR) of 8%, that would be your nominal interest rate on the loan.
Inflation erodes the purchasing power of money over time. Therefore, when calculating nominal interest rates during inflationary periods, it’s essential to consider how much prices are rising annually as this will impact the real value of your investments or debts.
Real Interest Rates:
Real interest rates take inflation into account to provide a more accurate picture of how much your investments are actually growing or how fast your debts are accumulating in terms of purchasing power. Real interest rates reflect the true return on an investment after adjusting for inflation.
To calculate real interest rates, you simply subtract the inflation rate from the nominal interest rate. For instance, if you have an investment with a nominal return of 6% and the current inflation rate is 2%, then your real return would be 4%. This means that after factoring in inflation, your investment has effectively grown by 4%.
Impact on Investments:
During times of high inflation, understanding real vs. nominal interest rates becomes crucial for investors. Nominal returns may appear attractive on paper but might not be so appealing once adjusted for inflation.
For example, suppose you invest in a bond offering a fixed annual return of 7%. If inflation is running at 5% per year simultaneously when calculating real returns using our formula (real = nominal – inflation), we find that your actual gain after adjusting for price increases would only be around 2%. In such cases where real returns are low due to high levels of inflation compared to nominal returns; investors might want to explore alternative investment options better suited for preserving their wealth against rising prices.
Impact on Borrowing:
On borrowing side during high-inflation environments; borrowers benefit from lower effective borrowing costs when considering real vs.n ominal interests
When taking out loans or mortgages during times when prices are increasing rapidly due primarily due because lenders charge highernomina linterestsratesto offset declining valueofrepaidfunds,inflationsignificantlyaffectstheeffectivecostborrowersfaceoverthelongterm
However,nomina linterestratesmightappearhighduringinflationbutonceadjustedforpurchasingpowererosionbyinflation,youmayfindthattheactualcostofborrowingismuchloweronarealbasis.Thisisimportantinformationwhenmakingdecisionsabouttakingonnewdebtduringperiodsofincreasedpricehikes
Practical Implications:
Being awareoftherealandnominalinterestratedistinctioncanhelpyoumakebetterfinancialdecisionssuchasinvestmentsandloansthroughoutdifferenteconomiccyclesUnderstandinghowinflationspecificallyimpactsthesekeyfinancialmetricshelpsinformingyourstrategiesfordiversifyingportfolios,minimizingrisk,andmaximizingreturnsOncetheconceptisgrasped,youcanevaluatetherisksandrewardsassociatedwithvariousfinancialproductsaccuratelyandmakeinformedchoicesbasedonyourfinancialgoalsandneedsFinalThoughts:Inaninflationaryenvironment,knowingthedifferencebetweenrealandnominalinterestratesisparamounttomakingwell-informedinvestmentandborrowingdecisionsByunderstandinghowinflationalterstheseeconomicindicators,youcanmitigaterisksexposure,maximizereturnsandprotectyourwealthagainsttheravagesofrisingprices