Navigating the Complex World of Interest Rates: Trends, Risks, and Opportunities
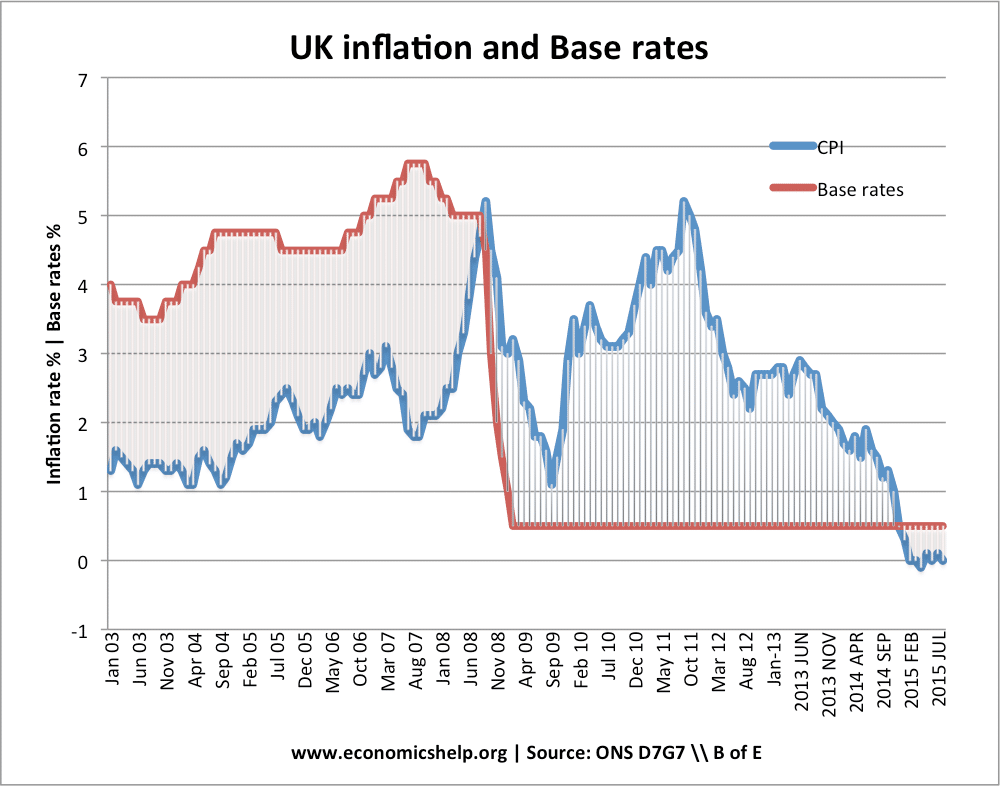
Interest rates play a crucial role in the world of finance and economics, affecting everything from borrowing costs to investment decisions. In recent years, we have witnessed some unique developments in interest rate policies that have had significant implications for individuals and businesses alike.
Negative interest rates, once considered unconventional, became a reality as central banks in several countries adopted this strategy to stimulate economic growth. This meant that instead of earning interest on deposits, depositors had to pay banks for holding their money. While negative interest rates aimed to encourage spending and investing, they also posed challenges for financial institutions and savers looking for returns on their savings.
Interest rate caps are another tool used by regulators to protect borrowers from excessive interest rate fluctuations. These caps limit how much lenders can increase the interest rates on adjustable-rate mortgages or other loans, providing borrowers with some stability and protection against rising rates. However, these caps can also limit the profitability of lenders during periods of high-interest rates.
Adjustable-rate mortgages (ARMs) have been popular among homebuyers seeking lower initial mortgage payments than fixed-rate mortgages offer. With ARMs, the interest rate adjusts periodically based on market conditions, which can lead to either higher or lower monthly payments for borrowers. While ARMs offer flexibility and potentially lower upfront costs, they also carry the risk of increased payments if interest rates rise significantly.
Peer-to-peer lending platforms emerged as an alternative source of financing outside traditional banks. These platforms connect individual investors with borrowers looking for loans at competitive interest rates. By cutting out intermediaries like banks, peer-to-peer lending has provided opportunities for both lenders seeking better returns on their investments and borrowers looking for more accessible financing options.
Inflation plays a vital role in determining real interest rates—the nominal rate minus inflation—which reflects the true cost of borrowing or return on investments after accounting for inflation’s erosion of purchasing power over time. Central banks closely monitor inflation levels when setting monetary policy and adjusting key interest rates accordingly to maintain price stability while supporting sustainable economic growth.
Understanding the different types of interests—nominal versus real—can help individuals make informed financial decisions based on accurate cost calculations over timeframes affected by inflationary pressures.
Interest rate risk management strategies are critical tools employed by individuals and businesses alike to mitigate exposure to adverse movements in prevailing market rates that could impact investment portfolios or debt servicing obligations negatively.
Central banks serve as key players in setting benchmark interest rates within economies through monetary policy tools such as open market operations or reserve requirement adjustments with mandates aimed at maintaining stable prices while fostering sustainable economic growth.
Forecasting techniques enable analysts and policymakers alike to anticipate future trends in interests influenced by various macroeconomic factors like GDP growth projections or employment data releases shaping expectations around future changes impacting markets globally.
The transition away from LIBOR—a widely used benchmark underpinning trillions worth derivatives contracts—to alternative reference standards poses challenges requiring careful planning across industries adapting smoothly without disruption towards more robust frameworks ensuring financial stability.
Shadow banking activities operate beyond traditional regulatory oversight influencing credit availability impacting broader economies often facing scrutiny amidst concerns surrounding systemic risks warranting closer monitoring addressing potential vulnerabilities effectively.
Behavioral economics studies provide insights into decision-making processes underlying individual choices concerning interests highlighting psychological biases impacting behaviors guiding policymakers crafting tailored interventions aligning incentives driving desired outcomes promoting greater financial literacy awareness empowering better-informed decisions collectively enhancing overall well-being economically.
Islamic finance principles adhere strictly prohibiting interests promoting profit-sharing models emphasizing ethical considerations social responsibility aligning business practices harmoniously benefiting communities holistically fostering inclusive development sustainably enriching lives positively.
Credit card issuers apply varying interests reflecting individual profiles assessing creditworthiness charging fees corresponding default risks managing profitability effectively balancing consumer needs expectations responsibly safeguarding against potential delinquencies prudently.
Student loan programs extend credits offering affordable education opportunities enabling learning prospects promising brighter futures students pursuing academic excellence navigating tuition expenses systematically easing burdens equitably cultivating talents nurturing aspirations constructively.
Auto loan providers supply finances facilitating vehicle purchases expanding mobility affording transportation conveniences enabling access goods services enhancing lifestyles efficiently meeting diverse needs preferences accommodating different budgets aptly tailoring terms suitably optimizing affordability individually.
Small business owners seek funding sources sustaining operations expanding ventures fueling innovations driving entrepreneurship forward stimulating job creation fostering economic growth catalyzing prosperity elevating societies inclusively serving communities harmoniously engendered collaborative partnerships synergistically creating value collectively.
In conclusion…