Unlocking the Power of Health Savings Accounts: Maximizing Benefits and Tax Advantages
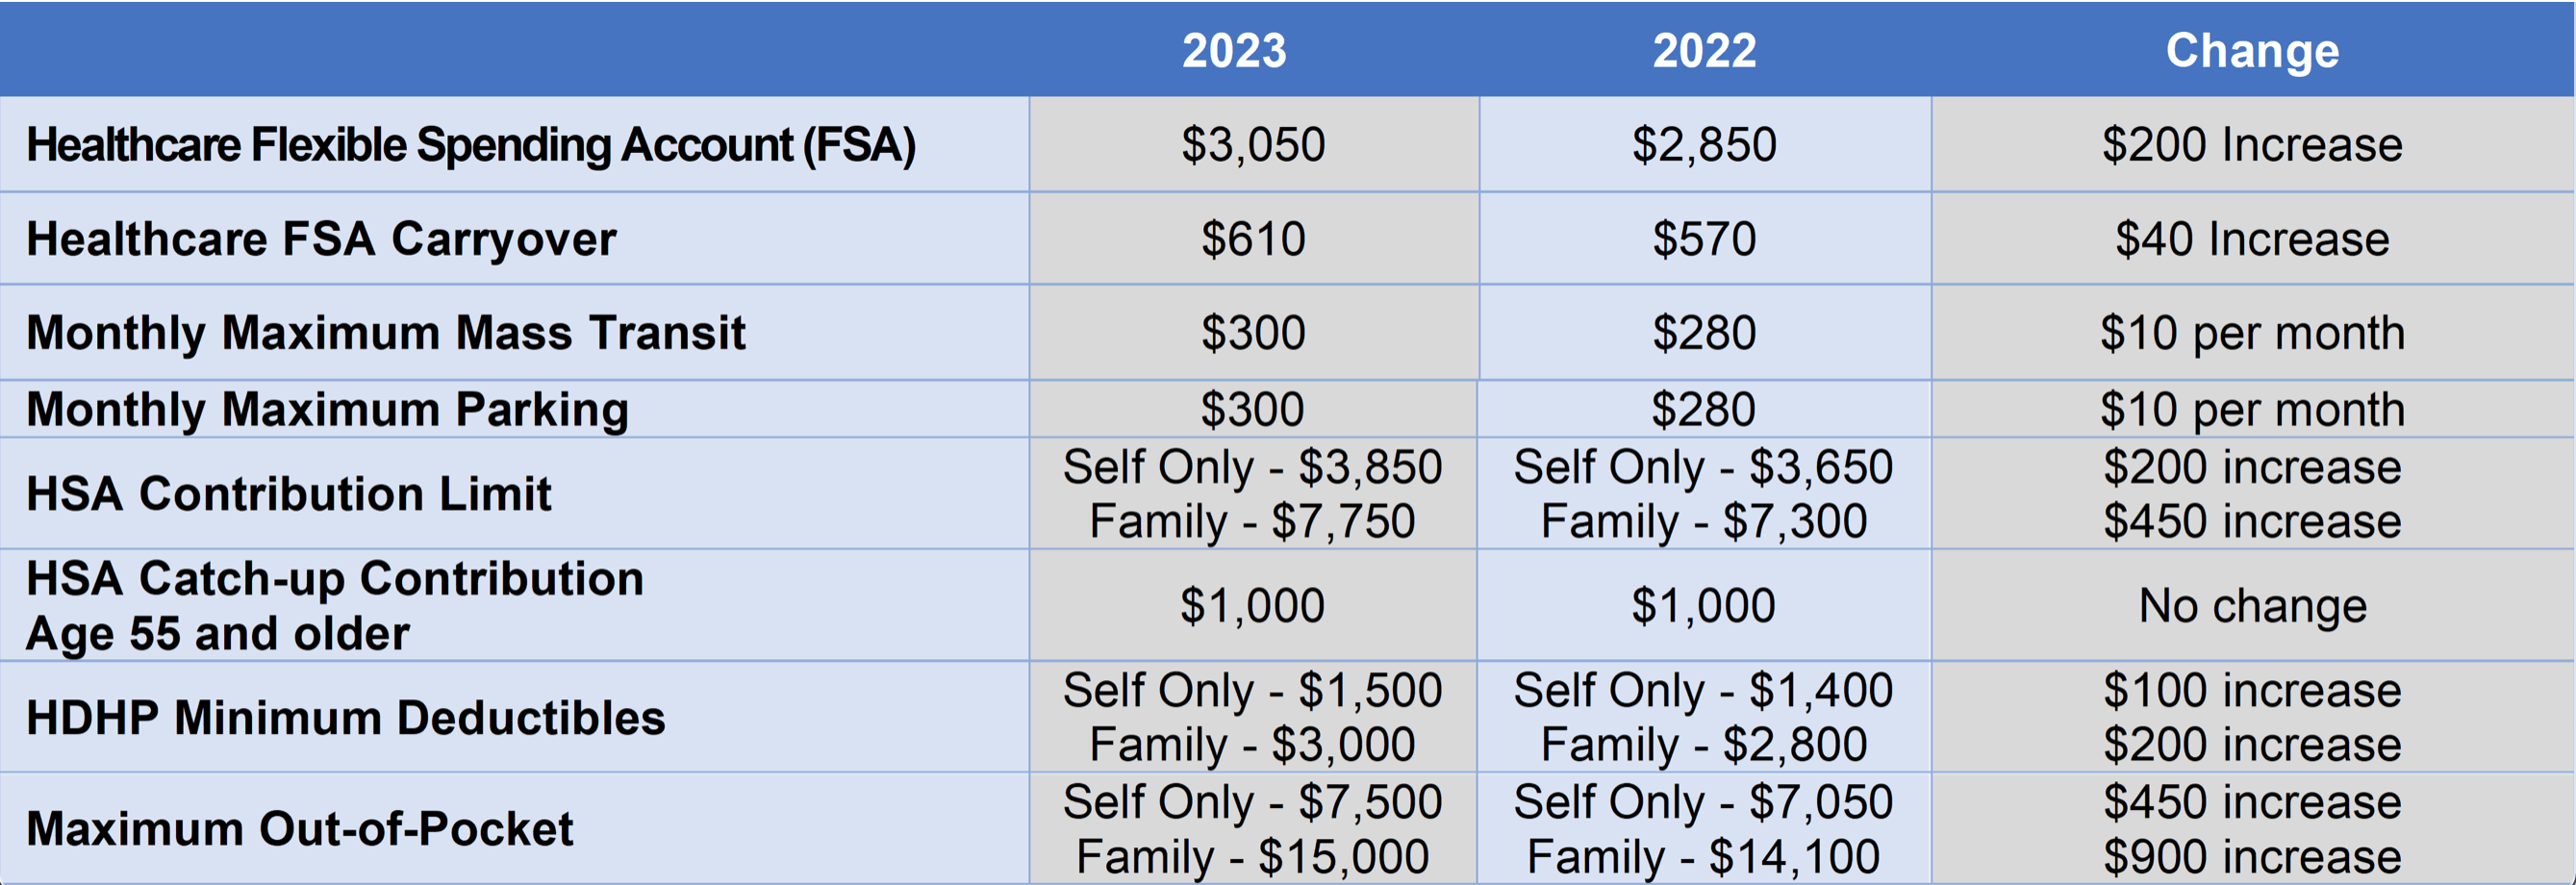
Health savings accounts (HSAs) are a powerful tool for managing healthcare expenses while also providing potential tax advantages. These accounts are designed to help individuals with high-deductible health plans save money for medical costs that may not be covered by their insurance.
One of the key benefits of an HSA is the ability to make contributions that can be deducted from your taxable income. In this post, we will discuss in detail how HSA contributions work, contribution limits, eligibility requirements, and some strategies for maximizing the benefits of these accounts.
**How HSA Contributions Work**
HSA contributions can come from several sources, including you, your employer, or a combination of both. If you contribute to your HSA through payroll deductions at work, those contributions are typically made on a pre-tax basis, meaning they are not subject to federal income tax or Social Security and Medicare taxes.
If you make contributions outside of work or choose to add more funds beyond what your employer contributes, those additional contributions may be tax-deductible when you file your annual income taxes. This provides a valuable opportunity to reduce your taxable income while saving specifically for future medical expenses.
It’s important to note that there are annual limits set by the IRS on how much you can contribute to an HSA each year. For 2021, the contribution limit for individuals with self-only coverage is $3,600 and $7,200 for those with family coverage. These limits are subject to change annually based on inflation adjustments.
**Eligibility Requirements**
To be eligible to contribute to an HSA, you must meet certain criteria:
1. You must be covered by a high-deductible health plan (HDHP). For 2021, this means an individual plan with a deductible of at least $1,400 or a family plan with a deductible of at least $2,800.
2. You cannot have any other non-HDHP health coverage (with some exceptions like dental or vision coverage).
3. You cannot be enrolled in Medicare.
4. You cannot be claimed as a dependent on someone else’s tax return.
Meeting these requirements allows you to open and fund an HSA account either through your employer’s chosen financial institution or through another provider offering these types of accounts.
**Maximizing Your Contributions**
Contributing the maximum allowed amount each year can help you take full advantage of the benefits offered by HSAs. By doing so consistently over time and investing those funds wisely within your account options (such as mutual funds), you may build up significant savings that can cover future medical expenses tax-free.
Here are some strategies for maximizing your HSA contributions:
– Contribute regularly: Setting up automatic payroll deductions or making regular monthly contributions can help ensure that you reach the annual limit without having to scramble at year-end.
– Take advantage of catch-up contributions: Individuals aged 55 or older can make additional “catch-up” contributions each year ($1,000 in 2021) above the standard limit.
– Use investment options wisely: Some HSAs offer investment choices beyond basic savings accounts—consider diversifying your portfolio within allowable guidelines based on risk tolerance and long-term goals.
– Save receipts for reimbursement later: Unlike flexible spending accounts (FSAs), there is no deadline for using funds in an HSA; keeping receipts now enables reimbursement years down the line if needed.
– Consider using other resources first: If possible without jeopardizing financial stability down the road,
pay current medical costs out-of-pocket and let saved funds grow over time; this strategy could allow larger amounts available later when needed most
In conclusion,
Health savings accounts present unique opportunities
for individuals who qualify under IRS guidelines
to save specifically earmarked monies intended
strictly towards future qualified healthcare expenditures;
maximizing consistent annual funding helps create
a valuable asset base available whenever necessary,
all while enjoying potential tax advantages along
the way—making HSAs an appealing option worth exploring further