Maximizing Financial Clarity: The Power of Straight-Line Depreciation
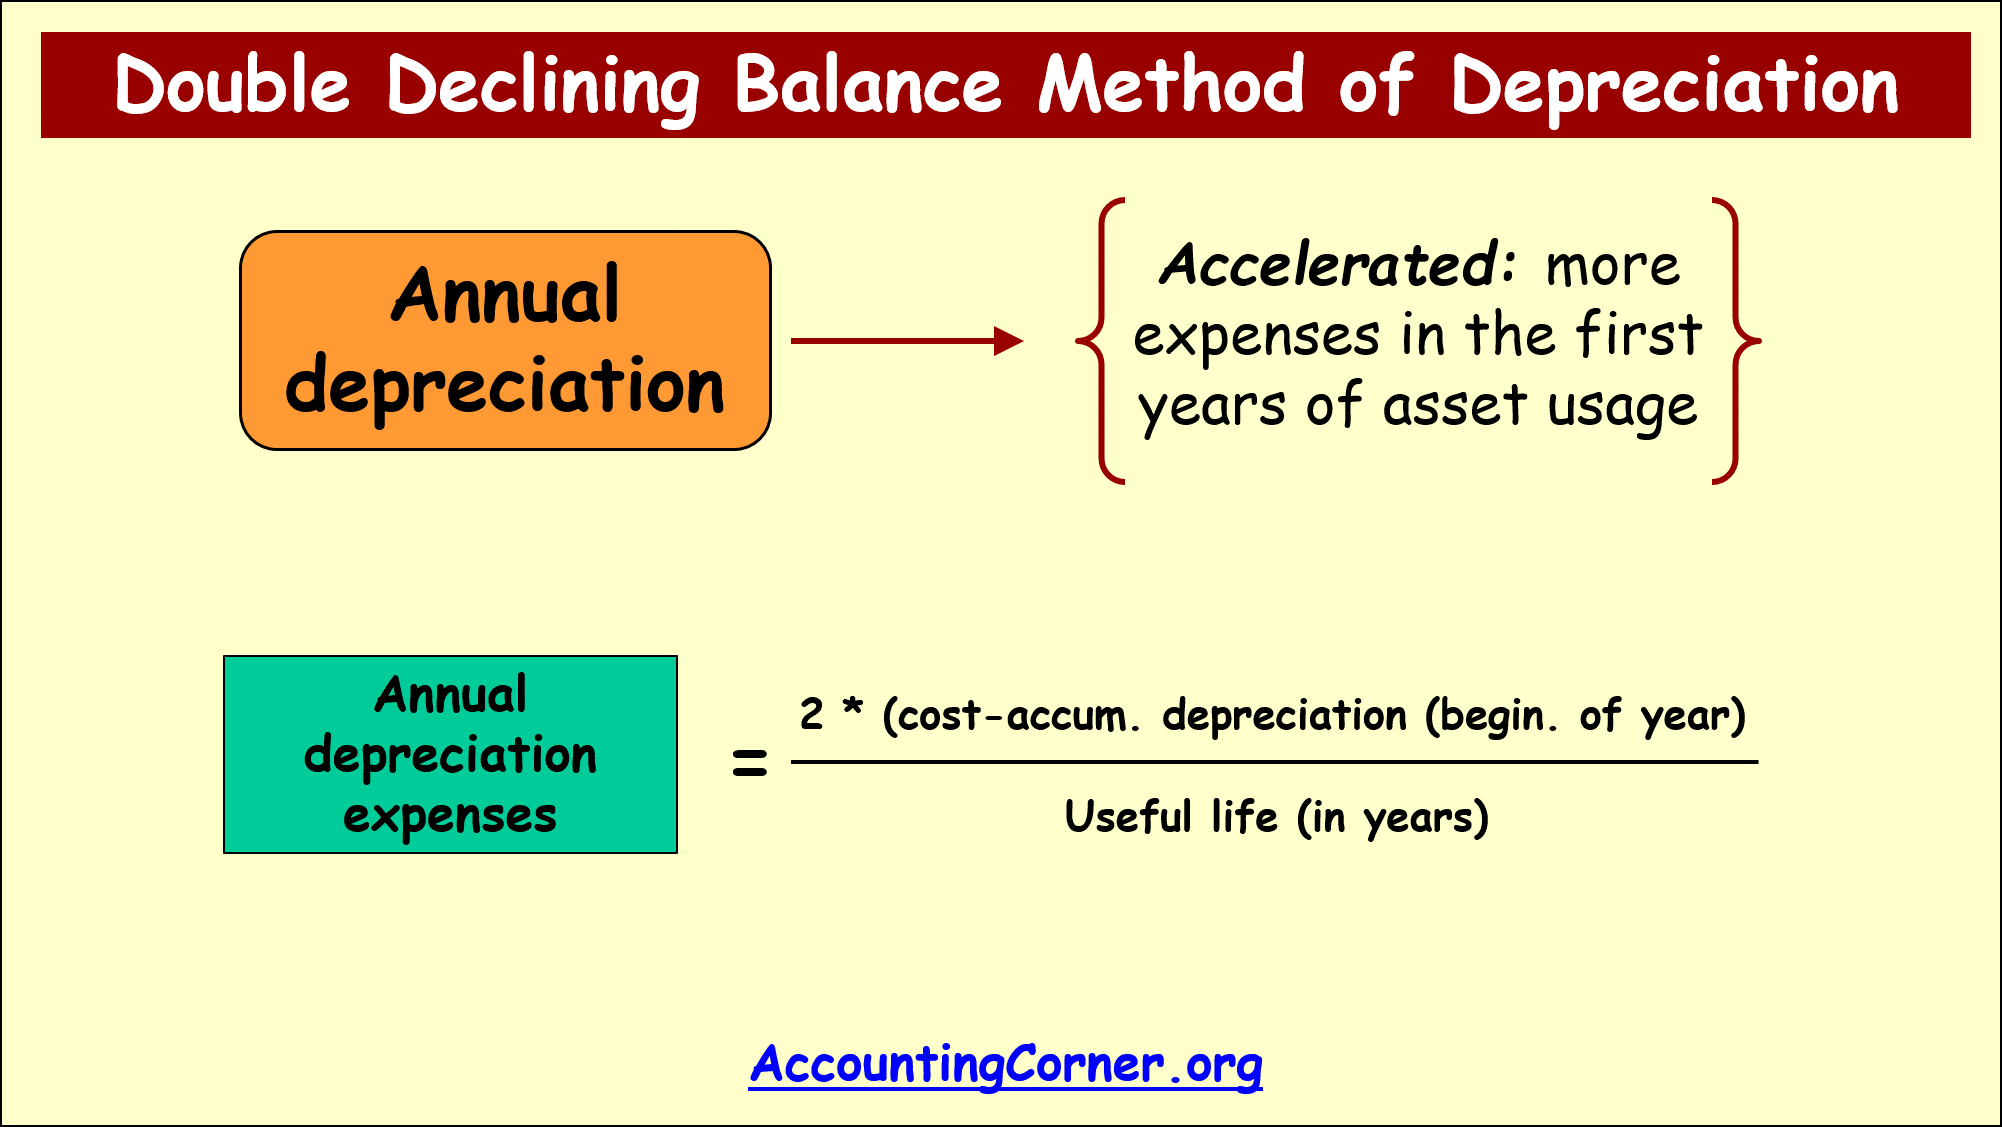
When it comes to managing finances and understanding the basics of accounting, depreciation is a concept that plays a crucial role. Depreciation refers to the decrease in value of an asset over time due to wear and tear, obsolescence, or other factors. Straight-line depreciation is one of the most commonly used methods for calculating this decrease in value.
Straight-line depreciation is a simple and widely accepted method for allocating the cost of an asset over its useful life. This method assumes that an asset depreciates by an equal amount each year until it reaches its salvage value (the estimated resale or scrap value). The formula for straight-line depreciation is straightforward: (Cost of Asset – Salvage Value) / Useful Life.
Let’s break down this formula further:
1. Cost of Asset: This refers to the initial purchase price of the asset. It includes not only the purchase price but also any additional costs incurred to get the asset ready for use, such as installation or transportation fees.
2. Salvage Value: The salvage value is an estimate of how much the asset will be worth at the end of its useful life. It serves as a basis for determining how much value has been consumed during each year of use.
3. Useful Life: The useful life represents how long the company expects to use the asset before disposing of it or replacing it with a new one. This can vary depending on the type of asset and industry standards.
By dividing the depreciable cost (Cost of Asset – Salvage Value) by the useful life, we can determine how much depreciation expense should be recorded each year under straight-line depreciation.
One key advantage of using straight-line depreciation is its simplicity and ease of calculation. Since it spreads out depreciation expenses evenly over time, it provides a clear and consistent picture of how much value an asset loses each year.
Moreover, straight-line depreciation helps in matching expenses with revenues more accurately. By spreading out the cost of an asset evenly over its useful life, businesses can reflect more realistic financial statements that align with their operations’ actual performance.
However, there are some limitations to consider when using straight-line depreciation. One drawback is that it does not account for accelerated wear and tear on assets that may occur in reality. As assets often lose more value in their earlier years compared to later ones, using straight-line depreciation may not fully capture this pattern.
Additionally, changes in market conditions or technological advancements may render certain assets obsolete before their expected useful life ends. In such cases, using straight-line depreciation could result in overstating an asset’s remaining value on financial statements.
In conclusion, while straight-line depreciation offers simplicity and consistency in allocating costs over time, businesses should also consider other methods like accelerated depreciation if they want a more accurate reflection of their assets’ true economic impact on their financial statements.